In this guide
- Paid collection score result finder
- What actually happens after you pay off a collection?
- What should a paid collection look like on your credit report?
- Does paying off collections improve your credit score?
- FICO vs. VantageScore: how paid collections are treated
- How much will my credit score increase after paying off collections?
- How long after paying off collections does your credit score improve?
- Why didn’t my credit score go up after paying off collections?
- Does a paid collection still hurt your credit score?
- Why is a paid collection still on your credit report?
- Does paying a collection restart the seven-year reporting period?
- Are paid medical collections different?
- What should you check after paying off a collection?
- Sources
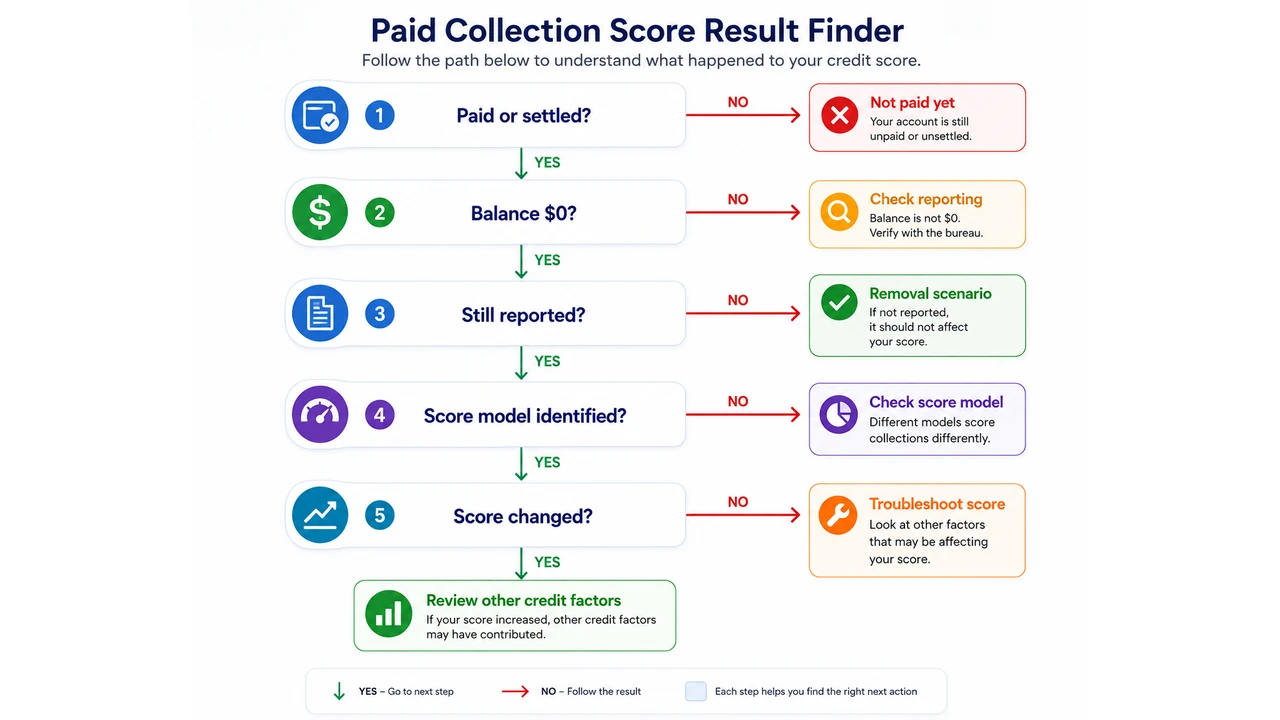
Paid collection score result finder
Use the collection entry on your credit report to choose a next step. The result is educational and cannot predict a point increase or a lender’s decision.
View the collection-payment decision chart
What actually happens after you pay off a collection?
After you pay off a collection account, several separate things can happen before you see any change in your credit score. Paying the debt, updating the collection on your credit reports, calculating a new credit score, and removing the collection are not the same event.| Step | What happens | What it means for your credit score |
|---|---|---|
| 1. You pay or settle the collection | The debt is paid in full or resolved under the settlement agreement. | Payment alone does not guarantee an immediate score change. |
| 2. The collection account is updated | If the collection is being reported, updated information may be furnished to the credit bureaus. A paid or settled debt should generally be reflected with a $0 balance. | Your score cannot reflect the updated collection information until the credit report used to calculate that score contains the new data. |
| 3. Your credit report reflects the update | Check the balance, account status, and last-updated date on the report you are reviewing. | A $0 balance does not automatically mean your score will increase. |
| 4. A new credit score is calculated | The scoring model evaluates the information in the credit report available at that time. | The result depends on the scoring model and the rest of your credit file. |
| 5. The collection may remain on the report | Paying an accurate collection does not automatically delete it from your credit report. | A collection can remain visible on a credit report even when some scoring models no longer treat the paid collection the same way as an unpaid one. |
What should a paid collection look like on your credit report?
After a collection is paid or settled and the updated information reaches your credit report, the account should generally show a $0 balance. The collection itself may still appear on the report, and the exact status wording can vary depending on the credit bureau and the company reporting the account.To check whether the collection was updated correctly, focus on the balance, account status, and last-updated date rather than looking for one specific phrase such as “Paid Collection.”Example: Before and after paying a collection
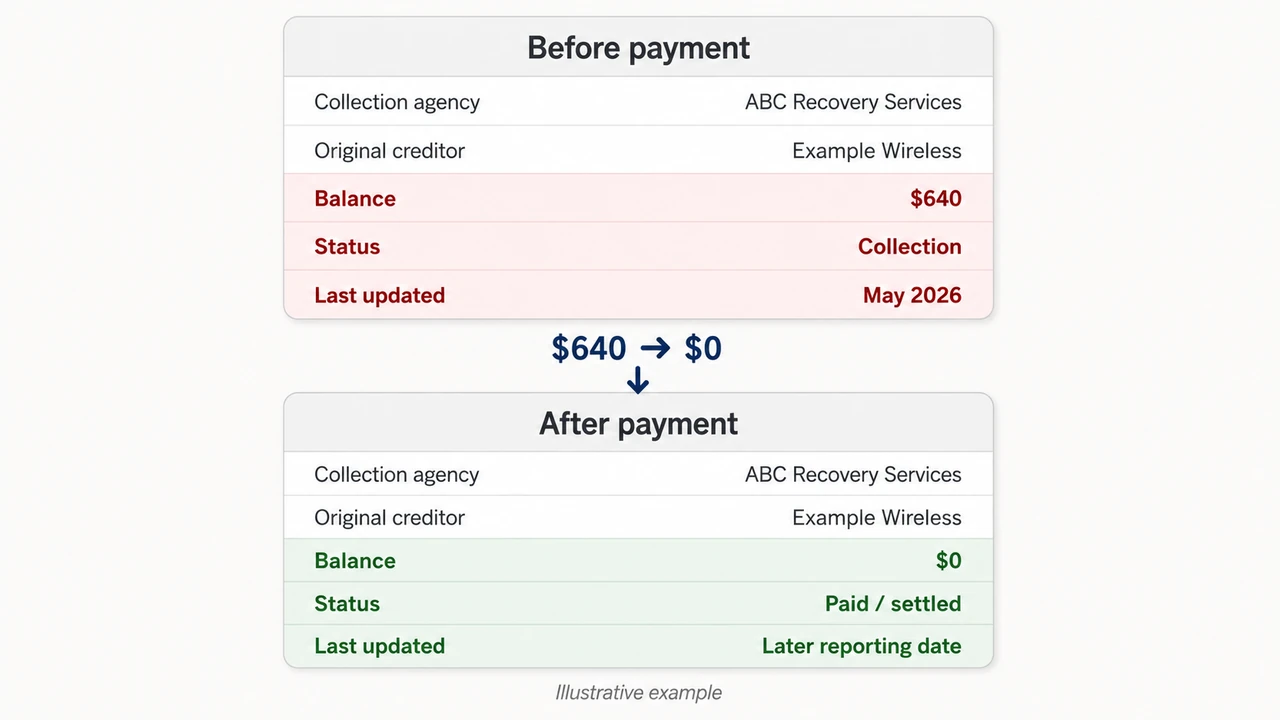
| Field to Check | Before Payment | After Payment | What to Verify |
|---|---|---|---|
| Collection agency | ABC Recovery Services | ABC Recovery Services | The company reporting the collection may remain the same. |
| Original creditor | Example Wireless | Example Wireless | The original creditor normally does not change because the collection was paid. |
| Balance | $640 | $0 | If the debt has been paid or settled, verify that the old amount owed is no longer being reported as the current balance. |
| Status | Collection | May reflect paid, settled, or another status showing the debt has been resolved | Make sure the status accurately reflects what happened to the debt. |
| Last updated | May 2026 | A later reporting date | Check whether the account has been updated since your payment or settlement. |
Check these three fields first
- Balance: Look for a $0 balance after the paid or settled collection has been updated.
- Status: Make sure the account no longer appears to be an unpaid collection if the debt has already been resolved.
- Last-updated date: Check whether the reporting date is later than your payment date. If it is still an older date, you may be looking at information that has not yet been updated.
Does paying off collections improve your credit score?
Paying off accounts in collections can improve some credit scores, but an increase is not guaranteed. The result depends on the credit-scoring model being used, what changes on your credit report after payment, and the rest of the information in your credit file.The scoring model matters because paid collections are not treated the same way by every model. Some newer scoring models disregard paid third-party collections, while older models may still consider them. This is one reason the same paid collection can produce different results depending on which credit score you are checking.What can happen after the collection is paid?
| What You See | What It May Mean | What to Check Next |
|---|---|---|
| Your credit score increases | The updated collection may be treated more favorably by the scoring model, or other positive changes may also have occurred in your credit file. | Confirm that you are comparing the same scoring model, credit bureau, and score source before and after the update. |
| Your credit score stays the same | The scoring model may still consider the collection, or other negative information may continue to affect your score. | Check the scoring model and review the rest of your credit report for other collections, late payments, charge-offs, or high credit utilization. |
| Two credit scores react differently | The scores may use different scoring models, different credit bureau data, or different calculation dates. | Compare like with like rather than treating scores from different sources as the same score. |
Before you decide whether paying the collection helped
- Confirm that the collection has been updated and that the resolved debt is showing a $0 balance.
- Identify the exact credit-scoring model you are viewing, if the source provides it.
- Compare the same scoring model and the same credit bureau whenever possible.
- Check whether anything else changed on your credit report during the same period.
FICO vs. VantageScore: how paid collections are treated
FICO and VantageScore do not treat paid collections the same way across every scoring model. If you paid a collection and your score did not react the way you expected, the first thing to check is which scoring model you are actually viewing.| Scoring Model | How It Treats Paid Collections | What to Check |
|---|---|---|
| FICO Score 8 | Paying a third-party collection does not automatically cause it to be disregarded. FICO Score 8 does disregard third-party collections when the original amount was under $100. | If the collection was $100 or more, do not assume that a $0 balance means the collection no longer affects this score. |
| FICO Score 9 | Third-party collections reported as paid in full are disregarded. A settled third-party collection reported with a $0 balance is also treated as paid. | Confirm that the collection has actually been updated to reflect the resolved debt and a $0 balance. |
| FICO Score 10 and 10 T | The FICO Score 10 suite disregards third-party collections reported as paid in full. Settled third-party collections reported with a $0 balance are treated as paid. | Check the reported balance and status before deciding whether the model should treat the collection as resolved. |
| VantageScore 3.0 | Paid collections are excluded from the score calculation. | Make sure the collection has been updated as paid before comparing your score. |
| VantageScore 4.0 | Paid collections are excluded from the score calculation. | Other information in your credit report can still cause the score to stay the same or move in another direction. |
Why the same paid collection can produce different scores
Suppose a $640 third-party collection is updated to a $0 balance. If you are checking FICO Score 8, the paid collection may still be considered. If you are checking FICO Score 9 or a score from the FICO Score 10 suite, that resolved third-party collection is disregarded. VantageScore 3.0 and 4.0 also exclude paid collections from their calculations.This is why you should not compare two credit scores from different apps or lenders and assume the collection affected both scores in the same way. First compare the scoring model, the credit bureau data being used, and the date each score was calculated.How to identify the score you are looking at
Check the score details provided by your lender, credit card issuer, credit bureau, or credit-monitoring service. Look for a label such as “FICO Score 8,” “FICO Score 9,” “VantageScore 3.0,” or another named model.If the scoring model is not identified, do not use that score alone to decide whether paying the collection helped. Your next step is to compare the account after it updated and then look at how much — if at all — the specific credit score you are tracking changed.How much will my credit score increase after paying off collections?
There is no fixed number of points your credit score will increase after paying off a collection. FICO says paying a collection can result in a score increase, a decrease, or no change at all because the result depends on the information in your entire credit report, not on the collection payment alone.So claims such as “paying a collection will add 50 points” or “your score will jump 100 points” are not reliable. The amount of the collection by itself does not tell you how many points your score will gain. If the collection is later deleted and you want research-backed context for the possible score change, see how much a credit score may increase after collection removal.What determines how much your score changes?
| Factor | Why It Matters | What to Check |
|---|---|---|
| The scoring model | Different credit-scoring models treat paid collections differently, so the same updated account may not have the same effect on every score. | Confirm the exact scoring model you are tracking and compare it with the same model after the account updates. |
| Other negative accounts | If your report still contains unpaid collections, charge-offs, serious late payments, or other derogatory information, paying one collection may not produce a large visible change. | Review the rest of the credit report instead of looking at the paid collection in isolation. |
| Whether the collection updated correctly | Your score cannot reflect the new collection information until the credit report used to calculate that score contains the update. | Confirm the balance, status, and last-updated date before measuring the result. |
| Credit card utilization | A large change in reported credit card balances can affect your score during the same period that the collection is being updated. | Compare your reported card balances and credit limits before and after the score change. |
| Other account changes | A new late payment, new account, hard inquiry, lower balance, or other report change can affect the score at the same time. | Look for changes elsewhere in the report between the two score dates. |
| The score you are comparing | Scores from different bureaus, scoring models, or dates are not an apples-to-apples comparison. | Compare the same scoring model, the same credit bureau, and ideally the same score provider. |
Example: The same $700 collection, two different credit files
Suppose Alex and Jordan each pay a $700 collection, and both collections are later updated to a $0 balance.Alex has no other collection accounts and relatively little other negative information. Jordan still has another unpaid collection, a 90-day late payment, and high credit card utilization.Even though they paid collections for the same amount, they should not expect the same credit-score result. A scoring model evaluates the full credit report, so the rest of each person’s credit file can make the outcome very different.How to measure your own result
- Wait until the collection information has actually updated on the credit report you are checking.
- Confirm that the resolved debt is reported with the correct balance and status.
- Write down the exact scoring model and credit bureau used for your current score, if that information is available.
- Compare that same score after the updated collection appears.
- Check whether credit card balances, late payments, new accounts, inquiries, or other information changed between the two score dates.
How long after paying off collections does your credit score improve?
After you pay or settle a collection, the credit report usually has to update before a newly calculated credit score can reflect the new account information. Experian says it generally takes about one to two months for a paid collection’s status to be updated on credit reports. That is a typical reporting timeframe, not a guarantee that your score will increase or that every bureau will update on the same day.Paid collection update timeline
- You pay or settle the collection. Save the payment receipt, settlement agreement, confirmation email, or other proof showing how the debt was resolved.
- The collector processes the payment. The collector may need time to update its own records before furnishing new information to the credit bureaus.
- Your credit report updates. Check the balance, status, and last-updated date. Experian says the paid status generally takes about one to two months to appear.
- A new credit score is calculated. A credit score uses the credit-report information available when that score is generated. If the report still shows the old collection information, the score cannot yet reflect the updated paid status.
- You compare the result. If the collection is reported correctly but the score still does not increase, check the scoring model and the rest of the credit file rather than assuming the payment was reported incorrectly.
How long does a paid collection take to update?
A one-to-two-month window is a useful expectation for the reporting update, but it is not a legal deadline for a score increase. Different furnishers, credit bureaus, and score providers can update on different schedules.When can your score reflect the update?
There is no universal number of days. The score can reflect the paid collection only after the credit report used for that score contains the updated information. For example, if you paid a collection on August 5 but the report you check on August 12 still shows the old balance and status, that score is not yet using the newly reported paid-collection information.Once the report is correct, compare the same scoring model, the same credit bureau, and ideally the same score source. If the score still does not move, the next step is to troubleshoot the scoring model and the rest of your credit profile.Why didn’t my credit score go up after paying off collections?
If your credit score did not go up after paying off a collection, that does not automatically mean the payment was reported incorrectly. The scoring model may still consider the paid collection, other negative information may still be affecting your score, or another change in your credit report may have offset any improvement.Before you troubleshoot the score itself, confirm that the collection has already been updated correctly. Check the reported balance, account status, and last-updated date. If those details are accurate, use the table below to narrow down what may be keeping your score from increasing.Paid collection troubleshooting matrix
| What You See | What It May Mean | What to Check | What to Do Next |
|---|---|---|---|
| The collection shows a $0 balance, but your score did not increase | The scoring model may still consider the collection, or other information in your credit file may be having a larger effect. | Check the exact scoring model you are viewing and compare it with the FICO vs. VantageScore section above. | If the collection is reported correctly, review the rest of your credit report before assuming there is a reporting error. |
| You paid one collection, but other collections remain | Resolving one collection does not resolve the effect of other collection accounts. | Check whether the remaining collections are unpaid, paid, duplicated, or reporting inaccurate information. | Deal with each remaining account based on what the credit report actually shows. |
| You still have late payments or charge-offs | The paid collection may not be the only serious negative information affecting your credit profile. | Review the payment history, balances, and status of your other negative accounts. | Focus on the remaining negative items instead of repeatedly checking the paid collection. |
| Your credit card balances increased around the same time | Higher credit utilization may affect your score while the collection update is also being reflected. | Compare the reported balances and credit limits on your revolving accounts before and after the score change. | If utilization increased, do not assume the collection payment caused the entire score result. |
| One credit score increased but another did not | The scores may use different scoring models, different credit bureau data, or different calculation dates. | Check the scoring model, credit bureau, score provider, and date for each score. | Compare the same scoring model and bureau over time whenever possible. |
| The collection disappeared from the report completely | The account was deleted rather than simply updated as paid. | Confirm that you are checking the same credit bureau where the collection previously appeared. | Treat this as a collection-removal scenario rather than a normal paid-collection update. |
| The balance, status, dates, or other account information are inaccurate | You may have a credit-reporting problem rather than a scoring problem. | Compare the credit report with your payment confirmation, settlement agreement, account records, and relevant dates. | If the information is inaccurate or incomplete, follow the steps to dispute an error on your credit report. |
Check these six things before you assume the payment did not help
- Confirm that the collection has updated on the credit report you are using.
- Verify that the balance and account status accurately reflect how the debt was resolved.
- Identify the exact scoring model you are checking, if the score provider discloses it.
- Compare the same scoring model and the same credit bureau before and after the update.
- Look for other collections, late payments, charge-offs, new accounts, hard inquiries, or major changes in reported credit card balances.
- Only treat the collection as a reporting problem if the information itself appears inaccurate, incomplete, duplicated, outdated, or otherwise incorrect.
Example: The collection is paid, but the score stays the same
Suppose a $900 collection is updated to show a $0 balance. The same credit report still contains a 90-day late payment and a charge-off, and one credit card is reporting a much higher balance than it did the previous month.In that situation, an unchanged score does not prove that the collection payment had no effect or that the collection is being reported incorrectly. Several pieces of information are being evaluated at the same time, so the next step is to identify what else in the credit file may still be affecting the score.If the collection is now reported correctly but your overall credit profile still needs work, follow the step-by-step plan to rebuild your credit after collections instead of disputing an accurate paid collection simply because your score did not increase.Does a paid collection still hurt your credit score?
It can under a model that still considers that collection. But being visible on the report and being included in a particular score are different things. Use the model comparison above rather than assuming every visible paid collection is still lowering your score. FICO’s collection guidance explains its version-specific treatment. If the model excludes the account, use the troubleshooting matrix above to review other report changes before deciding what to do next.
Why is a paid collection still on your credit report?
A paid collection can still appear on your credit report because paying the debt does not automatically delete an accurate collection account. Payment and removal are separate events. If the collection was reported and you later paid or settled it, the CFPB says the debt should generally be updated to reflect a $0 balance.So if the account still appears after payment, the first question is not “Why wasn’t it deleted?” but “Was it updated correctly?” Check the balance, status, and last-updated date against your payment records.What does your paid collection show?
| What You See | What It May Mean | What to Check Next |
|---|---|---|
| The balance is $0 and the collection is still listed | The account may have been updated as paid or settled rather than removed. | Check whether the status accurately reflects how the debt was resolved and whether the account has a newer update date. |
| The old balance is still showing | The account may not have updated yet, or the balance may be inaccurate. | Compare the reported balance and update date with your payment confirmation or settlement agreement. |
| The balance is $0 but the status still suggests the debt is unpaid | The account information may be incomplete or inaccurate. | Compare the reported status with your payment records before deciding whether further action is needed. |
| The collection disappeared completely | The account was removed rather than simply updated as paid. | Confirm that you are checking the same credit bureau where the collection previously appeared. |
| The account is accurate, paid, and still visible | Its continued appearance does not by itself mean there is a reporting error. | Verify the collection agency, original creditor, balance, status, and relevant dates. |
Does paying a collection remove it from your credit report?
No, not automatically. Under the FCRA’s standard reporting rules, paying or settling a collection does not create a new credit-reporting period and does not by itself erase an otherwise accurate collection. For an account placed for collection, the reporting period is tied to the delinquency that immediately preceded the collection activity; the statute uses a technical 180-day offset when calculating the seven-year period.Payment can change the balance and status once the new information is reported, but it does not restart that federal reporting clock. If the account is accurate but you want to know whether it can be removed before it falls off normally, see whether you can remove a paid collection from your credit report.Do not dispute it just because it is still visible
A paid collection remaining on your report is not, by itself, evidence that the information is wrong. Before considering a dispute, verify the balance, account status, collection agency, original creditor, and dates against your records.If those details are accurate, the next question is whether paying the collection changes how long it can remain on your credit report. That is a separate reporting-period issue.Does paying a collection restart the seven-year reporting period?
No. Under the FCRA’s standard credit-reporting rules, paying or settling a collection does not start a new seven-year reporting period. For an account placed for collection, the reporting period is tied to the delinquency that immediately preceded the collection activity. The statute uses a technical 180-day offset when calculating that period, so a later payment does not create a new federal reporting clock.For example, if the delinquency that led to collection began in 2022 and you pay the collection in 2026, the 2026 payment can update the balance and status, but it does not make 2026 the new starting point for the collection’s federal reporting period.Do not confuse the credit-reporting period with a state statute of limitations for a debt-collection lawsuit. Those are separate rules. In some states, making a payment or acknowledging an old debt may restart or otherwise affect the statute of limitations for legal collection. If you need the full reporting-period explanation, see does paying a collection restart the seven-year period.Are paid medical collections different?
Yes. Paid medical collections are treated differently from most other collection accounts. Under the reporting policies adopted by Equifax, Experian, and TransUnion, medical collection debt that has been paid should no longer appear on consumer credit reports from those three nationwide credit bureaus.What should happen after you pay a medical collection?
| What You Find | What It Means | What to Do Next |
|---|---|---|
| The paid medical collection is gone | This is the expected result under the nationwide credit bureaus’ medical collection reporting policies. | Check each credit report where the collection previously appeared to confirm the removal. |
| The paid medical collection is still showing | The account may not have been removed correctly, or the payment may not yet be reflected in the information being furnished. | Confirm that the debt was paid, save your proof of payment, and compare the collection agency, original provider, balance, and status with your records. |
| The account is actually a credit card collection | The special medical-collection treatment does not apply simply because you originally used the credit card to pay a medical bill. | Check what type of account is being reported before assuming the paid-medical-collection rules apply. |
What if a paid medical collection is still on your credit report?
First verify that the account is identified as medical collection debt and that your payment was completed. Then check each credit report where it appears and document exactly what is still being reported.If a paid medical collection continues to appear, keep your payment confirmation or settlement records and identify the specific reporting problem before taking action. Unlike an accurate paid non-medical collection that may remain on a credit report, a paid medical collection covered by the nationwide bureaus’ reporting policies should no longer be included.These reporting changes are policies adopted by the three nationwide credit bureaus; they should not be confused with a blanket federal ban on medical debt reporting.What should you check after paying off a collection?
After paying off a collection, first check whether the account was updated correctly on your credit reports. A debt that was reported and later paid or settled should generally be reflected with a $0 balance once the new information is reported.Post-payment collection checklist
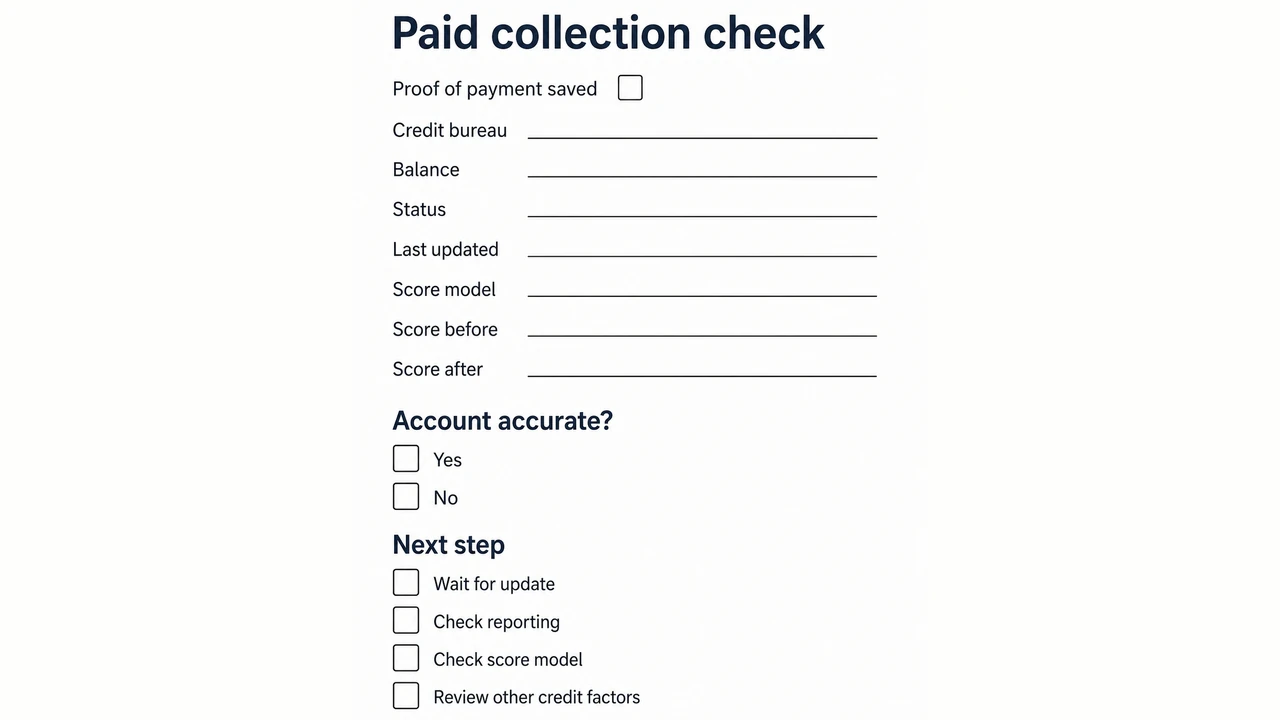
- Save proof that the debt was resolved. Keep your payment receipt, confirmation email, settlement agreement, final statement, or other record showing what you paid and when.
- Check the balance and status. Find the collection account on your credit report and confirm that the balance is $0 and the status accurately reflects how the debt was resolved.
- Check the last-updated date. If the old balance or status is still showing, compare the report’s last-updated date with your payment date. An older update date may mean the payment has not yet been reflected on that report.
- Check every credit report where the collection appeared. Review the account separately on Equifax, Experian, and TransUnion if it appeared on those reports. Credit reports can contain different information, so do not assume an update on one report means the others match.
- Compare the same credit score. If you are measuring what happened to your score after paying the collection, compare the same scoring model and the same credit bureau when possible. Otherwise, differences between scores can make the before-and-after comparison misleading.
Choose your next step based on what you find
| What You Find | What to Do Next |
|---|---|
| The balance is $0 and the account information is accurate | No reporting correction is needed. If your score is still lower than expected, review the other information in your credit file. |
| The old balance or status is still showing | Compare the last-updated date with your payment records. Keep your proof of payment while you determine whether the account is still waiting to update or contains an error. |
| The balance, status, creditor information, or dates are inaccurate | Write down exactly what is wrong and gather documents that show the correct information before taking further action. |
| The collection disappeared but your score did not increase | Check the rest of the credit file for other negative accounts, credit card utilization changes, recent account activity, and whether you are comparing the same type of score. |
| Everything is accurate but your score is still low | Do not try to correct an accurate paid collection simply because the score did not rise. Focus instead on the remaining parts of your credit profile that can still improve. |
After checking the paid collection, choose your next priority with the step-by-step credit improvement plan. If the remaining negative entry belongs to the original creditor, compare what paying a charge-off changes.
Explore related guides on collections.
Sources
- Consumer Financial Protection Bureau — What Is a Paid Collection?
- FICO — How Do Collections Affect Your Credit?
- VantageScore — How Paid Collections Are Treated
- Experian — How Long Before a Collection Account Is Updated?
- Federal Trade Commission — Consumer Reports: What Information Furnishers Need to Know
- Consumer Financial Protection Bureau — How to Dispute an Error on Your Credit Report
- Consumer Financial Protection Bureau — Medical Debt and Credit Reports
- Consumer Financial Protection Bureau — Older Debt and the Statute of Limitations
- U.S. Code — 15 U.S.C. § 1681c, credit-reporting time limits