In this guide
- Quick answer
- Can a collection agency change the date opened?
- Date opened vs. date of first delinquency: what is the difference?
- Does a new collection account date opened restart the seven-year period?
- When is a collection account date opened actually wrong?
- Turn the date mismatch into a specific request
- How to verify the collection account date before filing a dispute
- Send the date-specific dispute and keep a receipt
- What happens after you dispute the collection account date?
- Questions when the records are incomplete
- Bottom line: what to do if the collection account date opened is wrong
- Sources and editorial review
Quick answer
If your collection account date opened is wrong, dispute it only when the date is factually inaccurate or makes the account’s reporting history misleading. A collection agency can report a newer date opened when it received, purchased, or created its own record for the debt. That does not mean it can change the date of first delinquency or legally make the debt look newer than it is.
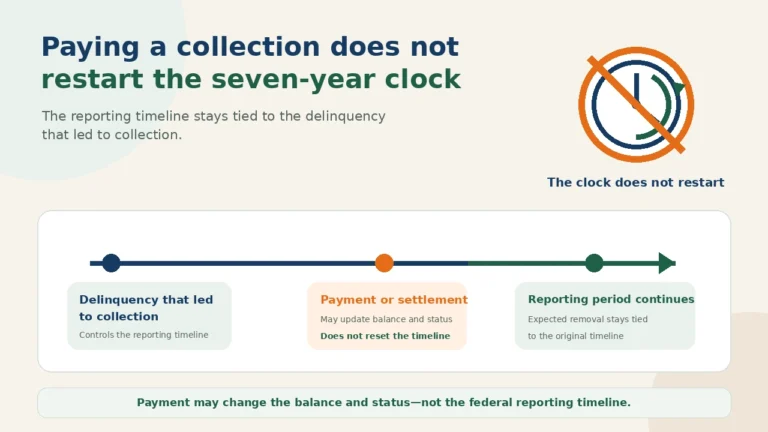
A legitimate collection open date does not restart the federal credit reporting period by itself. Before filing a dispute, compare the date opened with the date of first delinquency and the estimated removal date. For related collection reporting questions, browse the Collections hub.
Can a collection agency change the date opened?
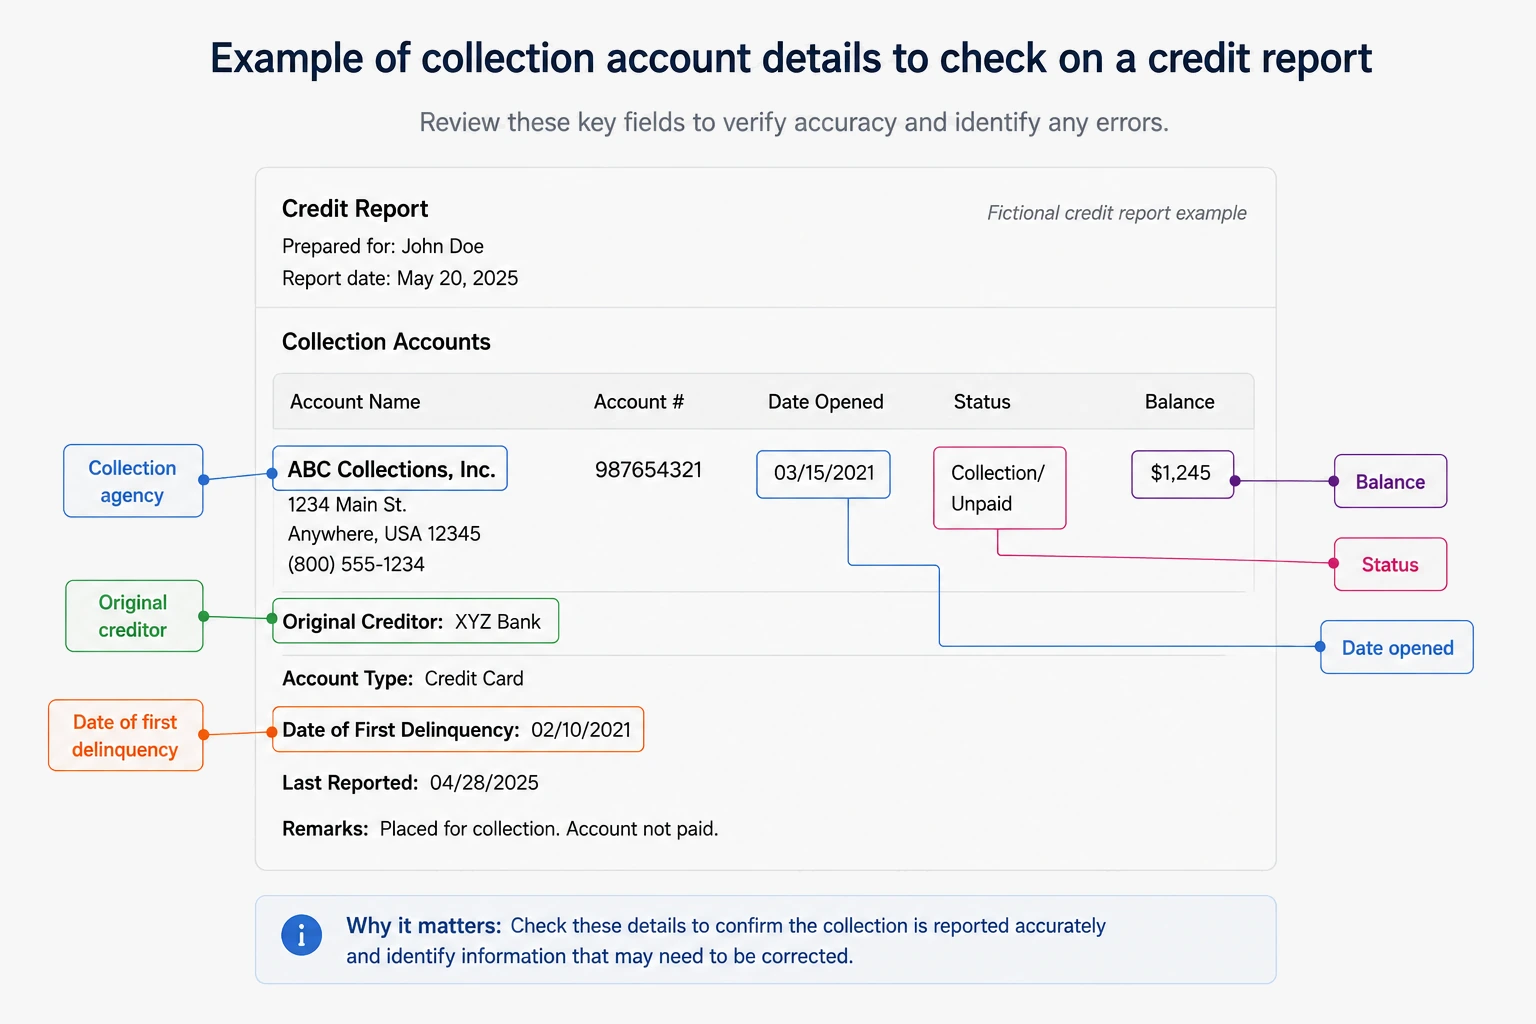
A collection agency can report an open date that reflects when it received, purchased, or created its own record for the account. That date can be newer than the original debt without necessarily being wrong. What deserves closer review is an inaccurate date of first delinquency, an unexpectedly later removal date, or an open date that conflicts with the collector’s own records.
Check these three dates first
- Date opened: When the collection agency opened its record or acquired the debt.
- Date of first delinquency: When the uninterrupted delinquency that led to collection began.
- Estimated removal date: When the collection is expected to leave your credit report.
| What your credit report shows | What it may mean | Should you dispute it? |
|---|---|---|
| A recent date opened | The collector recently received or purchased the debt | Usually no |
| An open date that conflicts with the collector’s records | The reported date may be inaccurate | Yes, if you have supporting evidence |
| A later date of first delinquency | The debt may appear newer than it really is | Yes |
| A later estimated removal date | There may be a reporting error or possible re-aging | Investigate and dispute if inaccurate |
Do not calculate the reporting timeline from the collection agency’s date opened. Learn more about what can and cannot restart the seven-year collection reporting period.
Date opened vs. date of first delinquency: what is the difference?
The date opened and the date of first delinquency are not the same. The date opened may show when a collection agency received the debt or created its own account record. The date of first delinquency identifies when the uninterrupted delinquency that led to the collection or charge-off began.
A recent collection open date does not automatically make an old debt new. When checking how long a collection may remain on your credit reports, the original delinquency history and estimated removal date usually matter more than the collector’s later open date.
| Credit report date | What it usually means | Why it matters |
|---|---|---|
| Date opened | When the collection agency opened its record or acquired the account | It may be years newer than the original debt without being inaccurate |
| Date of first delinquency | When the uninterrupted delinquency that led to collection or charge-off began | It is generally used to determine the federal credit reporting timeline |
| Date updated | When the collector last sent account information to a credit bureau | It can change without restarting the reporting period |
| Estimated removal date | When the credit bureau expects the collection to leave the report | A removal date that becomes unexpectedly later may indicate an error that needs investigation |
Example: an old debt with a recent open date
Suppose you stopped paying an account in March 2021 and never brought it current again. A collection agency acquired the debt in October 2025 and reported October 2025 as the date opened.
The October 2025 open date may be accurate because it reflects when that collector received the account. However, it should not replace the original delinquency that began in March 2021 or create a new credit reporting period.
For a closer look at the reporting timeline, see what can and cannot restart the seven-year collection reporting period.
Does a new collection account date opened restart the seven-year period?
No. A new date opened on a collection account does not, by itself, restart the federal credit reporting period. The date may show when a collection agency received, purchased, or created its record for the debt. It does not replace the original delinquency that immediately preceded the collection or charge-off.
A collector may continue updating the account, and a new debt buyer may report its own date opened. Those later dates do not automatically make the debt new or allow it to remain on your credit report for another seven years.
| Event | Does it restart the credit reporting period? | What to check |
|---|---|---|
| A new collector acquires the debt | No | Compare the original delinquency and estimated removal dates |
| The collection receives a recent date opened | No | Confirm whether the date reflects when the collector opened its record |
| The collector updates the account | No | Do not confuse the date updated with the date of first delinquency |
| The debt is paid or settled | Not by itself | Check whether the balance and status were updated accurately |
| The date of first delinquency is moved forward | It should not create a new reporting period | Investigate and dispute the inaccurate delinquency date |
| The estimated removal date becomes later after a transfer | Not automatically | Compare older reports for a possible reporting error |
Example: a new collector reports an old debt
An account became continuously delinquent in June 2020 and was later placed for collection. A debt buyer acquired the account in January 2026 and reported January 2026 as its date opened.
The January 2026 date may accurately show when the debt buyer opened its collection record. However, it should not replace the delinquency that began in June 2020 or create a new reporting timeline beginning in 2026.
If the newer open date is accompanied by a later date of first delinquency or estimated removal date, compare the account with older credit reports and dispute the specific field that is inaccurate.
See what can and cannot restart the seven-year collection reporting period for a fuller explanation of payments, account updates, debt transfers, and reporting dates.
Changed collector, not necessarily changed debt: Experian explains that a collection account can have a later open date after a transfer without acquiring a new delinquency timeline. If the company name also changed, use the collection-transfer guide. If two collectors now show the debt, compare their roles in the duplicate-collection guide. Then return to the date evidence below.
When is a collection account date opened actually wrong?
A collection account date opened may be wrong when it conflicts with the collector’s records, creates an impossible account timeline, or is connected to an inaccurate date of first delinquency or estimated removal date. A recent open date alone is not enough to prove an error.
Before filing a dispute, compare the reported date with collection notices, older credit reports, the original creditor’s payment history, and the expected removal timeline.
| Warning sign | What it could mean | What to compare |
|---|---|---|
| The collector’s notice shows a different acquisition or placement date | The reported open date may be inaccurate | The collection notice and current credit report |
| The collection appears to have opened before the original account became delinquent | The account timeline may be impossible | The original creditor’s payment history and collection records |
| The date of first delinquency changed to a later month or year | The collection may appear newer than it really is | Older and current credit reports |
| The estimated removal date moved forward after the debt was transferred | The reporting timeline may have been calculated incorrectly | Reports from before and after the transfer |
| Equifax, Experian, and TransUnion show materially different dates | One or more reports may contain inaccurate information | All three full credit reports and supporting records |
| The previous and current collectors both report active balances | Ownership, status, or duplicate reporting may be unclear | Collector names, account numbers, balances, and statuses |
Red flags that deserve closer review
- the reported open date does not match the collector’s letter or account records;
- the collection was supposedly opened before the original debt became delinquent;
- the date of first delinquency became newer after the debt was sold or transferred;
- the estimated removal date is later than older credit reports indicated;
- the account remains after the expected credit reporting period;
- different credit bureaus report conflicting delinquency histories;
- the collection disappeared and returned with a later removal timeline;
- the previous collector and current collector both report the debt as active.
| Probably not an error | Possible reporting error |
|---|---|
| A new collector reports the date it received the debt | The reported date conflicts with the collector’s own records |
| The date opened is newer than the original creditor account | The date of first delinquency was moved forward |
| The account was recently updated | The estimated removal date became unexpectedly later |
| The debt was sold to another collection agency | The account timeline is impossible or internally inconsistent |
| The bureaus display similar information using different field names | The bureaus report materially different delinquency dates |
Example: the collector’s records do not match the credit report
A collection notice states that the agency received the account in April 2024, but the credit report lists December 2025 as the date opened. That difference does not automatically require deletion of the collection, but it gives the consumer a specific factual inconsistency to investigate.
The consumer should compare the collection notice, earlier credit reports, the original date of first delinquency, and the estimated removal date. If the December 2025 date cannot be supported, the dispute should identify that exact field and request a correction.
Once you identify the specific inaccurate field, follow the complete process to dispute errors on your credit report.
Before submitting the dispute, review the documents that can support a credit report dispute and attach only records that directly prove the reported date or timeline is inaccurate.
Turn the date mismatch into a specific request
Use the following hypothetical comparison to distinguish an open-date problem from a delinquency-date problem. It is an editorial worksheet, not a bureau form or a finding that a violation occurred.
| Your record | Current report | Question or correction to identify |
|---|---|---|
| Collector letter: account received in April 2024 | Date opened: December 2025 | Ask which event the reported open date represents. Explain the two dates and request investigation of that field; do not substitute the original lender’s opening date automatically. |
| Older report: continuous delinquency began in May 2020; no later cure in your records | Date of first delinquency: May 2024 | Identify the changed delinquency field and attach the earlier report and payment history. Ask for the timeline to be investigated and corrected if unsupported. |
| Same underlying delinquency before and after a collector transfer | Only the collector’s open date became newer | A later transfer date alone does not establish a reporting error. Check the actual delinquency and removal information. |
Write your own request in this form: On [bureau/report date], [field] says [date]. My [document/date] shows [conflicting event or date]. Please investigate this discrepancy and correct the field if inaccurate. Include enough account information for the official process to identify it. Keep sensitive records private and send copies only to the relevant bureau or furnisher.
The CFPB’s dispute instructions explain how to identify the error and supply evidence. You do not need the collector to agree with you before disputing information you reasonably believe is inaccurate or incomplete.
How to verify the collection account date before filing a dispute
Before disputing a collection account date, compare all three credit reports, the original creditor’s payment history, collection notices, and any older reports you saved. Your goal is to identify the exact field that is inaccurate and build a timeline supported by documents.
Do not rely only on a credit monitoring app. A simplified account summary may omit the date of first delinquency, estimated removal date, or other details available in a full credit report. Start by reviewing how to read your credit report and locate each collection-related field.
Step 1: get all three credit reports
Review your reports from Equifax, Experian, and TransUnion. A collection agency may report to one, two, or all three bureaus, and the dates may not appear identically on every report.
Save a copy of each report before submitting a dispute. You may need the original version to show what was reported before an investigation or correction.
Step 2: find the original creditor account
Locate the account that existed before the debt was placed for collection. Record:
- the original creditor’s name;
- the partial account number;
- the original account opening date;
- the first missed payment;
- the date the account became continuously delinquent;
- the charge-off date, if applicable;
- the balance and account status.
Step 3: find every collection entry connected to the debt
Look for the current collector and any previous collection agencies that reported the same debt. Compare collector names, partial account numbers, original creditor names, balances, statuses, and dates.
A recent date opened may be legitimate if it matches when the current collector received the account. A conflicting delinquency or removal date deserves closer review.
Step 4: build the account timeline
| Information to compare | Original creditor | Collection agency | Credit report |
|---|---|---|---|
| Account number | |||
| Original account opening date | |||
| First missed payment | |||
| Date of first delinquency | |||
| Charge-off date | |||
| Collection acquisition date | |||
| Collection date opened | |||
| Date last updated | |||
| Estimated removal date | |||
| Balance and status |
Step 5: identify the uninterrupted delinquency
Determine when the delinquency that immediately preceded the collection or charge-off began.
If you missed a payment, brought the account fully current, and later became delinquent again, the later uninterrupted delinquency may be relevant. If the account never became current after the first missed payment, transferring the debt to another collector should not create a new date of first delinquency.
Step 6: compare older and current removal dates
Review older credit reports, when available, and compare the estimated removal date with the date shown on the current report.
A later removal date does not automatically prove improper reporting, but it gives you a specific inconsistency to investigate. Check whether the date of first delinquency also changed after the debt was sold or transferred.
Step 7: name the exact field that is wrong
Do not submit a dispute stating only that the collection account date opened is wrong or that “all dates are inaccurate.” Identify:
- the exact field you are disputing;
- the date currently reported;
- the date supported by your records;
- the documents proving the inconsistency;
- the correction you are requesting.
| Weak dispute statement | Stronger dispute statement |
|---|---|
| “The collection dates are wrong.” | “The report lists May 2024 as the date of first delinquency, but the enclosed payment history shows that the uninterrupted delinquency began in May 2021.” |
| “This debt is too old.” | “My earlier report showed an estimated removal date of June 2028, while the current report shows June 2031. Please investigate the changed reporting timeline.” |
| “Delete this collection account.” | “Please correct the inaccurate date or remove the disputed information if it cannot be verified.” |
Before submitting your dispute, review the documents that can prove a credit reporting error and include only records that directly support the correction you are requesting.
Send the date-specific dispute and keep a receipt
Use your timeline and the request example above to identify the collection and the exact date field. Send the dispute to each bureau reporting the error and to the company furnishing that information, using its designated dispute address or accepted channel. Include the report date, the date shown, the conflicting record, and the correction you are requesting. Follow the official identification requirements and send copies, not your only originals. The CFPB’s instructions cover both recipients.
Keep the correction specific. A collector’s wrong acquisition date calls for investigation of that field; an unsupported first-delinquency date calls for investigation of the delinquency timeline. Neither automatically requires deleting the whole account. When your records do not establish the replacement date, explain the discrepancy and what needs investigation rather than inventing one.
Save the exact submission, attachments, confirmation number, and receipt or delivery record. Record a separate case number for each bureau. That record lets you compare the result below with the request you actually sent.
For channel choices, sample letters, and the full filing workflow, use the credit-report dispute guide. For selecting evidence, use the document checklist.
What happens after you dispute the collection account date?
After you dispute a collection account date, the credit bureau generally must investigate within 30 days. The investigation can take up to 45 days in certain circumstances, such as when you provide additional relevant information during the investigation. The bureau generally has five business days after completing the investigation to notify you of the results.
Do not assume that a successful dispute will remove the entire collection. The result may be a corrected date, an updated removal timeline, deletion of information that cannot be verified, or verification of the account without changes.
What the dispute process usually looks like
| Stage | What usually happens | What you should do |
|---|---|---|
| Dispute submitted | The credit bureau records the dispute and forwards relevant information to the company that furnished the account data. | Save the confirmation number, submission date, and copies of everything you sent. |
| Investigation | The bureau and furnisher review the disputed date and supporting documents. | Keep new evidence organized in case the investigator requests more information. |
| Result issued | The bureau sends the investigation result and may provide an updated credit report if information changed. | Read the result carefully instead of checking only whether the collection disappeared. |
| Report updated | The disputed date may be corrected, deleted, or verified without changes. | Compare the updated report with the copy you saved before filing the dispute. |
| Follow-up | Another date, balance, status, or removal timeline may still be inaccurate. | Submit a focused follow-up only when you can identify a remaining error or provide additional evidence. |
Possible dispute results
| Result | What it means | What to do next |
|---|---|---|
| The date is corrected | The bureau or furnisher accepted that the reported field was inaccurate. | Save the result and confirm that the corrected date appears on the updated report. |
| The collection is deleted | The account or disputed information may not have been verified, or the furnisher may have instructed the bureau to remove it. | Check all three credit reports because deletion from one bureau does not prove that every report was updated. |
| The account is verified without changes | The furnisher confirmed the reported information during the investigation. | Review whether your dispute clearly identified the field and included records proving the inconsistency. |
| One bureau corrects the date, but another does not | The bureaus maintain separate consumer files and may reach different results. | Follow up separately with the bureau that continues reporting the inaccurate date. |
| The open date is corrected, but the removal date remains wrong | A second field may still be based on inaccurate delinquency information. | File a focused dispute addressing the remaining field and its supporting evidence. |
| The collection disappears and later returns | The account may have been reinserted after the furnisher verified it. | Compare the new entry with your previous report, including the delinquency and removal dates. |
What to check on the updated credit report
Review every related field instead of looking only for deletion:
- date opened;
- date of first delinquency;
- estimated removal date;
- date last updated;
- collection balance;
- account status;
- collection agency name;
- original creditor name;
- partial account number.
A corrected open date does not guarantee that the date of first delinquency or estimated removal date was also corrected. Compare the entire account timeline with the records you submitted.
What if the wrong date is verified without correction?
- Review your original dispute. Confirm that you identified the exact field, reported date, supported date, and requested correction.
- Check the evidence. Determine whether your documents directly prove the date is inaccurate rather than merely showing that the debt is old.
- Contact the furnisher. Send a direct dispute to the collection agency if you previously disputed only with the credit bureau.
- Provide additional relevant information. Submit another dispute only when you have new evidence or can explain the error more precisely.
- Save every report and response. Keep the version from before the dispute, the investigation result, and the updated report.
- Escalate a documented unresolved error. You may consider submitting a complaint to the Consumer Financial Protection Bureau or speaking with a qualified consumer attorney.
Will a correction improve your credit score?
Correcting a date does not guarantee a credit score increase. The result depends on which field changed, the scoring model, the age of the collection, and the rest of the information in your credit file.
Even if the collection is deleted, other negative information may still affect your scores. Learn why your credit score may not increase after a collection is removed.
Timing and follow-up guidance reviewed using the Consumer Financial Protection Bureau’s information on credit report dispute investigations and disagreeing with dispute results.
Need to check a field name again? Use the date comparison near the start of this guide.
A date correction is not automatic whole-account deletion. The result must match what the investigation establishes: inaccurate, incomplete, or unverifiable information is modified or deleted as appropriate under 15 U.S.C. § 1681i. Use the results table above to check the actual field and timeline. For payment-related removal questions, use the separate paid-collection removal guide; for an unchanged score after deletion, use the score diagnostic. Neither a corrected date nor deletion guarantees a particular point increase.
Questions when the records are incomplete
What if the report does not show the original delinquency date?
Record that the field is not shown instead of replacing it with the collector’s open date. Check an older report, original-creditor statements, and any estimated removal date. Ask the bureau and furnisher what delinquency information supports the timeline. Your dispute can identify a concrete inconsistency without pretending that you know a date you cannot establish.
Do I need every old statement before I can dispute?
No particular worksheet on this website is a legal prerequisite. Explain the specific information you believe is wrong and supply the relevant records you have, following the bureau’s identification requirements. The CFPB’s instructions focus on a clear explanation and supporting copies, not completion of our checklist. Do not manufacture dates or documents to fill a gap.
What if the bureau corrects the open date but not the removal timeline?
Compare the full result with your original request. An acquisition-date correction and a delinquency-date correction are different changes. Identify the remaining disputed field, attach the earlier result and relevant account history, and explain the unresolved mismatch. Do not resend an unchanged demand to delete the whole account solely because one date was corrected.
Bottom line: what to do if the collection account date opened is wrong
A recent collection account open date is not automatically wrong, and it does not restart the federal credit reporting period by itself. Dispute the date when your records show that the reported field is inaccurate, creates an impossible account timeline, or is connected to an incorrect date of first delinquency or estimated removal date.
Before taking action, follow these four steps:
- Compare all three credit reports. Review the collection entry on Equifax, Experian, and TransUnion.
- Identify the relevant fields. Check the date opened, date of first delinquency, date last updated, and estimated removal date.
- Build a documented timeline. Use older credit reports, original creditor records, collection notices, and payment history.
- Dispute the specific error. State which field is wrong, what date is currently reported, what your records show, and what correction you are requesting.
| What you found | What to do |
|---|---|
| A recent date opened, but the delinquency and removal dates remain consistent | Usually do not dispute the open date |
| The open date conflicts with the collector’s records | Dispute the specific open date and attach supporting documents |
| The date of first delinquency became newer after a transfer | Dispute the inaccurate delinquency information |
| The estimated removal date was moved forward | Compare older reports and dispute the documented inconsistency |
| The account or disputed information cannot be verified | Request correction or removal of the unverifiable information |
| The collection information is accurate but negative | Do not dispute it only because it affects your credit score |
Sources and editorial review
Written by: Claire Bennett, Founder & Editor of Fix My Money Life
Last reviewed:
Review standard: This article was reviewed for accuracy, clarity, and consistency with federal credit reporting law and consumer guidance available on the review date.
The examples in this article are illustrative. They show how collection account dates may appear on a credit report but do not represent guaranteed dispute, deletion, or credit score outcomes.
Primary sources
15 U.S.C. § 1681c — requirements relating to information contained in consumer reports
15 U.S.C. § 1681i — procedure when a consumer disputes credit report information
15 U.S.C. § 1681s-2 — responsibilities of companies that furnish information
Consumer Financial Protection Bureau — how to dispute an error on a credit report
Consumer Financial Protection Bureau — how long a credit report dispute investigation may take
Consumer Financial Protection Bureau — what to do if you disagree with dispute results
AnnualCreditReport.com — federally authorized source for credit reports