In this guide
- Reinsertion checker: did the disputed item actually come back?
- What does the FCRA require before deleted information can be reinserted?
- What counts as the same item?
- What should a reinsertion notice contain?
- What should you ask the credit bureau about the reinsertion?
- What evidence should you save before taking action?
- Build a reinsertion timeline
- What to do when a disputed item was removed and then came back
- What if the item came back but you never received a reinsertion notice?
- Can you dispute a reinserted item again?
- What if only one bureau put the item back?
- Will a reinserted item hurt your credit score?
- Four examples that look similar but require different next steps
- Frequently asked questions
- Related guides
- Sources
- About this guide
- Financial and legal disclaimer
Quick answer: If an item was deleted from your credit report after a dispute and the same information later came back, the return may be a formal reinsertion under the Fair Credit Reporting Act. When the FCRA reinsertion rule applies, the furnisher must certify that the information is complete and accurate before the credit reporting company can reinsert it, and the bureau must notify you no later than five business days after the reinsertion.
Do not assume every reappearing account is a legal reinsertion. First prove that the item was actually deleted after a completed dispute, confirm that the same information returned on the same bureau report, and look for the required notice. Then decide whether the problem is the reinsertion procedure, inaccurate account data, or something else.
If a collection disappeared without a completed dispute and later returned, that is a different situation. Use the separate guide on a collection that disappeared and came back to check for transfers, reporting pauses, or a different collector.
The key is the deletion history. The special reinsertion rule in 15 U.S.C. § 1681i(a)(5)(B) applies to information deleted after a credit reporting company reinvestigates a dispute and finds the item inaccurate, incomplete, or unverifiable. An account that merely vanished from a monitoring app, changed status, moved to another collector, or disappeared for another reason may involve a different issue.
Reinsertion checker: did the disputed item actually come back?
Before sending another dispute, classify what happened. A formal reinsertion requires more than “I saw the account disappear and then reappear.” You need a documented deletion after a dispute and a later return of the same information.
| What you see | Is this likely formal reinsertion? | What to check next |
|---|---|---|
| Your bureau dispute result said the item was deleted, and the same tradeline later appears again on that bureau | Possibly yes | Compare furnisher name, partial account number, balance, status, dates, and look for a reinsertion notice |
| The item disappeared only from a credit-monitoring app | Not enough evidence | Get the actual bureau report and the official dispute result |
| The dispute result said “updated” or “verified,” not “deleted” | Usually not a reinsertion issue | Compare which fields changed and whether any current field is inaccurate |
| A different collection agency appears for the same underlying debt | Not necessarily | Determine whether the debt was sold, assigned, or transferred |
| The same account stayed on the report but the balance or status changed | Usually an account update | Compare the changed field with statements and payment records |
| An identity-theft account returned after it had been blocked | A different federal process may apply | Preserve your Identity Theft Report and the bureau’s blocking correspondence |
Fast test: You have the strongest reinsertion fact pattern when you can place three documents side by side: the bureau’s result saying the item was deleted, a later report showing that the item was absent, and a newer report showing the same information again.
An identity-theft block follows § 1681c-2, which has separate grounds for rescinding a block and a notification requirement. Do not automatically treat a rescinded block as an ordinary dispute reinsertion.
Read the original dispute result before using the word “reinserted”
Credit bureau results can use short labels that lead to very different next steps. Do not rely on your memory of what happened. Save the actual result and identify the outcome the bureau reported.
| Result wording | What it usually tells you | Does the reinsertion rule clearly fit? |
|---|---|---|
| Deleted | The item was removed from the file after the reinvestigation | Potentially, if the same information later returns |
| Updated | One or more fields changed but the account may have remained | Not automatically; identify which field changed |
| Verified as accurate | The bureau left the disputed information in place after the investigation | Usually no, because there was no documented deletion |
| No longer reporting / account removed by furnisher | The item may have disappeared for a reason other than the bureau’s reinvestigation deletion | Needs closer review before treating it as § 1681i reinsertion |
This distinction protects you from building a follow-up dispute around the wrong theory. If the bureau only corrected a balance but the account stayed on your report, focus on whether the current balance is accurate. If the result clearly says “deleted” and the same tradeline later returns, the reinsertion questions become much more important.
What does the FCRA require before deleted information can be reinserted?
Under 15 U.S.C. § 1681i(a)(5)(A), a credit reporting company must delete or modify disputed information when its reinvestigation finds the item inaccurate or incomplete or determines that it cannot be verified. If information is deleted under that provision, § 1681i(a)(5)(B) sets conditions for putting it back.
The furnisher must certify that the information is complete and accurate
The credit reporting company may not reinsert information deleted under the reinvestigation rule unless the person that furnished the information certifies that it is complete and accurate.
The furnisher may be a bank, credit card issuer, loan servicer, debt collector, landlord, or another company that supplied the account information to the bureau. Certification is important because the FCRA does not allow previously deleted information to reappear merely because the same data later arrives again without the required basis.
The bureau must notify you within five business days
Under § 1681i(a)(5)(B)(ii)–(iii), the bureau must notify you of reinsertion no later than five business days afterward. The initial notice is written unless you authorized another available method for that purpose. The additional information listed below must still be provided in writing within the same five-business-day period.
The clock starts on the bureau’s actual reinsertion date, not when an app alerts you or you first discover the account. The date you receive a mailed letter may differ from when the bureau provided it. Ask for the reinsertion date and the notice’s date and delivery method before concluding it was late.
This is separate from the dispute investigation deadline, generally 30 days with certain extensions to 45, and from the notice of investigation results due within five business days after completion.
The bureau must have procedures designed to prevent improper reappearance
The FCRA also requires a credit reporting company to maintain reasonable procedures designed to prevent information deleted under the reinvestigation provision from reappearing, except when it is reinserted in accordance with the certification rule.
That means the practical question is not simply, “Did the furnisher send another monthly update?” The important question is whether the information that returned was handled under the reinsertion requirements that apply to previously deleted material.
What counts as the same item?
You do not need every visible field to be identical before you investigate a possible reinsertion. Furnisher names can be abbreviated, account numbers can be masked differently, and balances can change. Instead, compare enough fields to determine whether the returned tradeline is the same underlying information.
| Field | What to compare | Why it matters |
|---|---|---|
| Credit bureau | Experian, Equifax, or TransUnion | A deletion on one bureau does not prove another bureau deleted the same item |
| Furnisher name | Creditor, servicer, collector, or reporting company | A different furnisher may mean a different tradeline or transfer |
| Partial account number | Last four digits or masked identifier | Helps connect the returned item with the deleted entry |
| Original creditor | Especially for collections | Helps identify the underlying debt when a collector changes |
| Balance | Old, deleted, and returned balance | A changed balance may be a legitimate update or a new reporting error |
| Account status | Open, closed, paid, charged off, collection, transferred | Status can reveal whether the returned data is the same account or a changed condition |
| Payment history | Late-payment months and status codes | The specific disputed field may have returned even if the account itself never disappeared |
| Important dates | Date opened, payment dates, delinquency dates, update date | Date differences can distinguish a new furnisher from the same reporting error |
What should a reinsertion notice contain?
For reinsertion covered by § 1681i(a)(5)(B)(iii), the bureau must provide the following information in writing within five business days after reinsertion, either as part of the notice or separately:
Written reinsertion information checklist
- A statement that the disputed information has been reinserted.
- The business name and address of any furnisher the bureau contacted, or that contacted the bureau, in connection with the reinsertion.
- The furnisher’s telephone number, if reasonably available.
- Notice of your right to add a statement to your file disputing the information’s accuracy or completeness.
Authorizing an alternative method for the initial notification does not remove this written-information requirement or extend the deadline. A generic monitoring alert that “an account was added” does not establish that the bureau provided the statutory notice and details. Search your mail, email, bureau account, and dispute portal before reporting a missing notice.
What should you ask the credit bureau about the reinsertion?
If you have a documented deletion and the same information is back, contact the bureau with a narrow set of questions. Your goal is not to argue about your score. Your goal is to establish what the bureau believes happened and which furnisher supported the return of the information.
Questions to ask
- Was this tradeline reinserted after my prior dispute deletion?
- What date does your system show for the reinsertion?
- Which furnisher provided the certification connected with the reinsertion?
- What business name, address, and telephone number do you have for that furnisher?
- When and how was the reinsertion notice sent to me?
- What specific account fields were certified or supplied when the item returned?
Write down the representative’s name or ID if available, the date and time of the contact, and any reference number. If you use an online message system, save screenshots or PDFs of the exchange.
Short phone or written script
“My dispute result dated [date] says account [partial account number] was deleted. The same account appears again on my [bureau] report dated [date]. Please tell me whether this was processed as a reinsertion under 15 U.S.C. § 1681i(a)(5)(B), identify the furnisher associated with the reinsertion, and tell me when and how the reinsertion notice was sent.”
This script does not accuse the bureau of violating the law. It asks for the facts you need to decide what happened.
Can you request the bureau’s investigation procedure?
If a covered reinvestigation leaves you unsure how the bureau checked the item, request the description of its accuracy-and-completeness procedure under § 1681i(a)(6)(B)(iii) and (7). The bureau normally must provide that description within 15 days after receiving your request, including the contacted furnisher’s business name, address, and telephone number if reasonably available. This is a request for a procedure description; the statute does not automatically entitle you to a copy of a signed reinsertion certification.
How to use the bureau’s answer
| Bureau response | What it may mean | Your next step |
|---|---|---|
| “Yes, it was reinserted” and the bureau identifies the furnisher and notice | The bureau is treating the event as formal reinsertion | Compare the returned fields with your records and dispute any current inaccuracies |
| “Yes, it was reinserted,” but the bureau cannot identify when notice was sent | There may be a notice-process issue | Save the response and document that you could not locate the required notice |
| “This was a normal furnisher update, not reinsertion” | The bureau may be distinguishing the event from a prior dispute deletion | Compare the deletion result and returned tradeline carefully; if the same deleted information returned, ask the bureau to explain the difference |
| “The item was never deleted” | Your app or a temporary report view may have created the impression of deletion | Find the official dispute result and post-dispute report before making a reinsertion claim |
| The bureau gives a different furnisher name | The debt or account may have moved to another company | Determine whether this is a transfer, new collector, servicing change, or separate tradeline |
If the bureau’s answer conflicts with documents you already have, preserve both. For example, if your written result says “deleted” but a representative says the item was never deleted, do not discard either record. That discrepancy itself is something to clarify in a documented follow-up.
What evidence should you save before taking action?
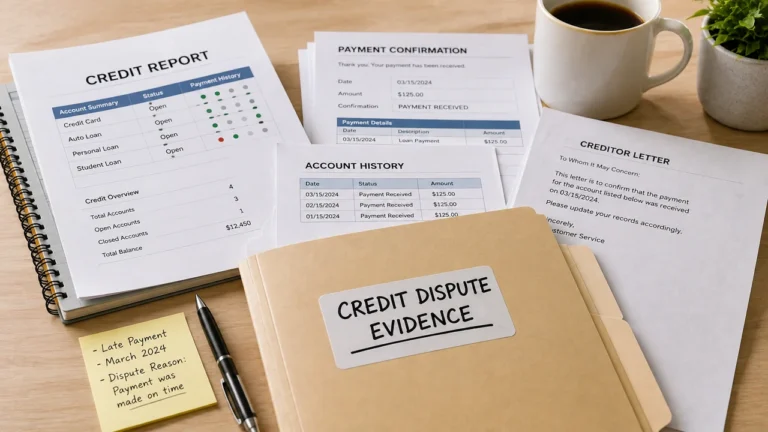
Build a before-and-after file before contacting anyone. The strongest reinsertion dispute is chronological: it shows what was reported, what you disputed, what the bureau deleted, when the item was absent, and exactly what later returned.
| Document | What it proves | Suggested file name |
|---|---|---|
| Original credit report | What the item looked like before the first dispute | 2026-05-01-experian-before-dispute.pdf |
| Original dispute submission | Exactly what you challenged and what evidence you provided | 2026-05-04-experian-dispute.pdf |
| Delivery or online confirmation | When the bureau received or accepted the dispute | 2026-05-04-dispute-confirmation.pdf |
| Investigation result | Whether the bureau said deleted, updated, or verified | 2026-06-02-dispute-result.pdf |
| Report showing the deletion | That the item was absent after the dispute | 2026-06-03-experian-after-deletion.pdf |
| Report showing the return | When and how the information reappeared | 2026-07-12-experian-item-returned.pdf |
| Reinsertion notice | Whether the bureau gave the required notice and identified the furnisher | 2026-07-15-reinsertion-notice.pdf |
| Statements or payment records | Whether the returned balance, status, or payment history is accurate | 2026-07-account-statement.pdf |
The file names above are hypothetical examples; use the dates from your own records.
For a broader evidence list, see what documents you need to dispute a credit report. Keep originals and submit copies when appropriate.
Build a reinsertion timeline
Keep discovery and reinsertion dates separate. Mark an unknown date “unknown”; an account’s last-updated date is not necessarily its reinsertion date.
| Event | Your date | Evidence |
|---|---|---|
| Original dispute submitted and received | ________ | Confirmation or delivery proof |
| Dispute result issued | ________ | Investigation result |
| Item shown as deleted or absent | ________ | Post-dispute report |
| Actual reinsertion date | ________ / unknown | Bureau’s explanation or records |
| Item first seen again | ________ | Dated report or alert |
| Notice and written details provided | ________ / unknown | Dated notice, delivery record, or portal message |
| Notice received or accessed | ________ / none found | Envelope, email, or portal record |
Use the bureau’s actual reinsertion date to assess the five-business-day notice requirement. Keep any envelope or message timestamp so you can distinguish when the bureau provided notice from when you received it.
What to do when a disputed item was removed and then came back
1. Get the actual report from the bureau where the item returned
Do not rely only on a score app or monitoring alert. Save the current credit report from the bureau where you see the returned item. AnnualCreditReport.com is the federally authorized source for reports from the three nationwide credit reporting companies.
If you have reports from all three bureaus, compare them separately. A deletion by Experian does not automatically mean Equifax or TransUnion made the same deletion.
2. Find the original investigation result
Read the result carefully. Look for the exact outcome: deleted, updated, verified, or similar wording.
If the item was never deleted, stop calling the situation “reinsertion.” If the result was verified as accurate and the account later looks different, use the separate guide explaining what “verified as accurate” means after a credit dispute.
3. Confirm that the same information returned
Compare the old and new reports line by line. Do not stop at the creditor name. Check the bureau, furnisher, masked account number, original creditor, balance, status, payment history, and important dates.
If a different collection company now reports the debt, investigate whether the debt was transferred. If the same creditor remains but only the balance changed, the problem may be a balance-update issue rather than reinsertion.
4. Look for the reinsertion notice
Search your mail, email, spam folder, online bureau account, and dispute portal. Record the date you first saw the item back on your report and the date of any notice.
If you received a notice, compare the furnisher named in it with the company shown on the current report. Save the notice even if you believe the account is still inaccurate.
5. Identify the exact current problem
Do not send a follow-up dispute that says only, “You deleted this before, remove it again.” Identify the specific issue you want investigated now.
- The account does not belong to you.
- The balance is wrong.
- The account was paid or settled but still shows money owed.
- A late-payment month is wrong.
- The status is inaccurate or incomplete.
- The same information was reinserted but you cannot find the required notice.
- The furnisher shown on the notice does not match the returned tradeline.
- The account appears to be duplicated or mixed with another consumer’s information.
6. Send a specific, documented follow-up dispute when there is a real problem
If the returned information is inaccurate or incomplete, dispute the exact field and attach the evidence that supports the correction. The CFPB recommends disputing inaccurate information with both the credit reporting company and the company that furnished the information.
For the full filing process, use how to dispute errors on your credit report. Keep the deletion-and-return evidence with your submission.
Educational example of follow-up wording
“My [Experian/Equifax/TransUnion] dispute result dated [date] states that account [partial account number] was deleted. The attached report dated [date] shows the item absent. The same tradeline appears again on my report dated [date]. I have not located a reinsertion notice. The current entry also reports [specific field] as [reported value], but the attached [statement/payment record] shows [correct value]. Please investigate the accuracy of the returned information and provide the information associated with the reinsertion.”
Use only statements that are true for your situation. Remove any sentence you cannot document.
7. Keep the reinsertion issue separate from the account’s accuracy
A missing notice can be important, but it does not automatically prove that you never owed the account. Likewise, a furnisher certification does not prevent you from disputing a specific balance, date, payment status, or ownership error supported by your records.
Track two questions separately:
- Was the reinsertion procedure followed?
- Is the information currently being reported accurate and complete?
8. Check the CFPB complaint instructions before escalating
The CFPB’s current complaint instructions say to dispute inaccurate or incomplete report information directly with the bureau first. The portal requires an attestation that the dispute was filed more than 45 days ago or is no longer pending, and warns against accuracy complaints during an active investigation. Check the current form before filing; this complaint-screening threshold does not extend the bureau’s legal investigation deadline.
If a documented follow-up dispute does not resolve the problem, preserve the full timeline and consider a CFPB complaint when you meet the current eligibility instructions. If the dispute is denied or the bureau again says the information is accurate, see what to do after a credit dispute is denied.
What if the item came back but you never received a reinsertion notice?
Save the deletion result, the report showing the account absent, and the report showing it returned. Record when you discovered it, search all correspondence, then ask the bureau for the actual reinsertion date and when and how it provided the notice and written details. “I cannot find a notice” is useful evidence to document; it does not by itself establish that no notice was provided.
If the bureau’s response does not resolve a documented notice problem, retain its response with your timeline. Separately dispute any inaccurate account fields. Missing notice does not automatically erase a valid debt or guarantee deletion, damages, or a score increase. Consider a consumer law attorney when unresolved reporting is causing significant financial harm.
Can you dispute a reinserted item again?
Yes, when you have a specific accuracy, completeness, identity, duplication, outdated-information, or reinsertion-procedure issue to raise. A second dispute should be more precise than the first, not merely a copy of it.
The FCRA allows a credit reporting company to treat a dispute as frivolous or irrelevant in certain circumstances, including when the consumer does not provide enough information to investigate. CFPB dispute guidance emphasizes identifying the specific information you dispute and supplying supporting documents.
Good reason for a follow-up dispute
Suppose your original report showed a $2,480 balance, you disputed it with a statement showing $0, and the bureau deleted the tradeline. Two months later the same tradeline returns showing $2,480 again. Your strongest follow-up dispute would include the deletion result, the report showing the item gone, the new report showing the balance back, and the $0 statement.
Weak reason for a follow-up dispute
“The account is negative and I want it removed” is not an accuracy dispute. CFPB guidance explains that accurate negative information generally cannot be removed simply because it harms your credit. Do not keep disputing accurate information in hopes that a furnisher will eventually fail to respond.
What if only one bureau put the item back?
That can happen. Experian, Equifax, and TransUnion maintain separate files and can receive or process furnisher data at different times. Treat each bureau report as a separate record.
If Experian deleted the item and later reinserted it while Equifax and TransUnion did not, build the reinsertion timeline from the Experian documents. Do not use the absence from another bureau as proof that Experian’s entry is wrong; instead compare the actual account facts and the deletion history.
Will a reinserted item hurt your credit score?
Focus on the information that returned, rather than assuming a fixed penalty for reinsertion. FICO’s payment-history guidance explains that reported payment history, delinquencies, and collection information can affect scoring. A returned negative item may therefore affect a score calculated from that bureau’s file.
The result depends on the type of information, its age and status, the rest of your credit file, the bureau, and the scoring model. Do not expect a fixed number of points in either direction.
If your main question is whether the dispute process itself lowers your score, use does disputing your credit report hurt your credit score?
Four examples that look similar but require different next steps
Example 1: same tradeline returns with no notice found
Assume Jordan disputes a credit card account with Experian. The result says the tradeline was deleted. Jordan saves a report showing the account gone. Six weeks later the same creditor and masked account number appear again, and Jordan cannot find a reinsertion notice.
Next step: Jordan should preserve the deletion result and both reports, search for the notice, ask Experian about the reinsertion, and dispute any current inaccurate information. Jordan should not assume the underlying debt is invalid solely because no notice was found.
Example 2: a collection disappears and a new collector appears
Assume Taylor sees ABC Collections disappear. Two months later XYZ Recovery reports a debt with the same original creditor but a different account number.
Next step: Taylor should first determine whether the debt was sold or transferred. This may not be the same tradeline being reinserted. The collection-specific guide linked earlier is the better path.
Example 3: the account was never actually deleted
Assume Casey’s monitoring app stops displaying an account for three weeks, but the bureau’s official dispute result says “updated,” and a later full report still contains the tradeline.
Next step: Casey should not claim a reinsertion violation based on the app display. The better question is whether the current account fields are accurate.
Example 4: the account returns with corrected information
Assume Morgan disputes a $4,200 balance, the account is deleted, and it later returns with the correct $420 balance and a reinsertion notice naming the furnisher.
Next step: Morgan should compare every field with current records. The fact that the tradeline returned does not itself create an error if the reinsertion requirements were followed and the reporting is accurate.
Frequently asked questions
Can a deleted item legally come back on your credit report?
Yes. Information deleted after an FCRA reinvestigation may be reinserted if the furnisher certifies that the information is complete and accurate and the credit reporting company follows the applicable notice requirements.
How long does a credit bureau have to notify you of reinsertion?
The FCRA requires notice no later than five business days after the reinsertion for information covered by § 1681i(a)(5)(B).
What if I never received the reinsertion notice?
Document the original deletion, the later return, and your search for the notice. A missing required notice may indicate a reinsertion-procedure problem, but it does not by itself prove that the account is not yours or that the debt is invalid.
Can I dispute the item again after it comes back?
Yes, if you can identify a specific inaccuracy, incomplete field, identity problem, duplicate entry, outdated information, or reinsertion-related issue. Attach evidence and do not simply resend the same unsupported wording.
Does the furnisher certification mean every account detail is correct?
No. Certification is part of the reinsertion requirement, but you may still dispute a specific balance, payment status, date, ownership detail, or other field when your records support a different result.
What if the item came back under a different company name?
Compare the original creditor, masked account numbers, balances, dates, and account status. A different company may indicate a sale, assignment, servicing transfer, or new collection tradeline rather than the exact same item being reinserted.
Does reinsertion restart the seven-year reporting period?
No. Reinsertion does not itself create a new delinquency date. For delinquent accounts placed for collection or charged off, § 1681c(c)(1) ties the federal reporting period to the delinquency that immediately preceded that action, rather than the date of reinsertion. Other information types and statutory exceptions have their own rules.
What if the bureau says the returned item is verified as accurate?
Read the result and identify what the bureau actually verified. If you still have evidence of a factual error, focus the next step on that specific discrepancy. If the information is accurate, do not keep disputing it simply because it is negative.
Related guides
- Credit reports & disputes hub — disputes, reinsertion, evidence, and follow-up guidance.
- What “verified as accurate” means after a credit dispute — understand a verification result.
- Collection account disappeared and came back — a related scenario when a collection returns to a report.
Sources
- GovInfo — 15 U.S.C. § 1681i
- Consumer Financial Protection Bureau — How do I dispute an error on my credit report?
- Consumer Financial Protection Bureau — Is it possible to remove accurate but negative information?
- Consumer Financial Protection Bureau — Credit and consumer reporting complaint notice
- Federal Trade Commission — Disputing errors on your credit reports
- AnnualCreditReport.com — federally authorized credit-report source
Featured illustrative photo: Towfiqu barbhuiya / Unsplash.
About this guide
Source review: October 9, 2026
Claire Bennett is an editorial name used by Fix My Money Life, not a claimed professional credential. Primary sources and procedural instructions were checked on October 9, 2026.
This guide is written for U.S. consumers whose credit report information was deleted after a dispute and later appeared again. It focuses on the FCRA reinsertion rules, how to document the deletion-and-return timeline, and how to separate a reinsertion-procedure problem from an accuracy dispute.
Financial and legal disclaimer
This article is for general educational purposes only and is not legal, financial, credit-repair, or individualized professional advice. Credit-report disputes depend on the facts, the documents, the reporting company, and applicable law. If repeated inaccurate reporting is causing significant financial harm or you need advice about a potential FCRA claim, consider speaking with a qualified consumer law attorney.