In this guide
- Is this monthly charge-off update normal?
- Before vs. after: which change matters?
- Use this quick check before you dispute anything
- Can a creditor keep reporting a charge-off every month?
- Does monthly charge-off reporting restart the seven-year period?
- Is each monthly CO code a new charge-off?
- When should monthly reporting concern you?
- Run this five-step monthly charge-off audit
- What evidence should you save if something looks wrong?
- How to dispute inaccurate monthly charge-off reporting
- Does a charge-off hurt your score again every month?
- Your next step
- Frequently asked questions
- Bottom line
- Related guides
- Sources
Yes. A charge-off can continue to be reported or updated from month to month. That does not usually mean a brand-new charge-off is being created each month, and a newer Date Updated does not by itself restart the federal credit-reporting period. If you need the basic account-status definition first, see what a charge-off means on your credit report.
The useful question is: what changed? Compare the balance, account status, owner or furnisher, date of first delinquency, payment-history codes, and expected removal timeline. If only the update date changed while the underlying account history stayed consistent, that may simply be a routine update. If you are worried that an update changed the seven-year timeline, see how long a charge-off stays on your credit report. If the account has already been paid but still shows a balance, use the paid charge-off balance guide. For related reporting, payment, and removal questions, browse the Charge-offs hub.
Is this monthly charge-off update normal?
Answer these questions using your current report and an older copy. This checker does not decide whether a legal violation occurred; it helps you identify the field that deserves closer review.
Before vs. after: which change matters?
Older report:
Date Updated: May 2026
Date of First Delinquency: March 2021
Newer report:
Date Updated: September 2026
Date of First Delinquency: March 2021
The update date moved, but the underlying delinquency date did not.
Older report:
Date of First Delinquency: March 2021
Newer report:
Date of First Delinquency: March 2023
Now there is a specific date change to compare with older reports and account records.
Use this quick check before you dispute anything
| What you see | What it may mean | What to check next |
|---|---|---|
| Only Date Updated changed | May be a routine account update | Compare the date of first delinquency and removal timeline with an older report |
| “CO” or “charge-off” appears in several months | May be the continuing status of the same account | Confirm the creditor and account identifier match the same tradeline |
| Date of first delinquency became newer | Needs closer review | Compare older reports, statements, and payment history |
| Balance changed | Could reflect payment, settlement, permitted account activity, or an error | Reconcile the amount with your records |
| Expected removal date moved later | Timeline may need review | Check whether the underlying delinquency date also changed |
| You paid it, but a current balance still appears | The update may be delayed or inaccurate | Compare the report with payoff or settlement records |
Can a creditor keep reporting a charge-off every month?
Creditors and other data furnishers can continue sending account information to the credit reporting companies. A later update may reflect a payment, balance change, settlement, dispute notation, sale, transfer, or another account change.
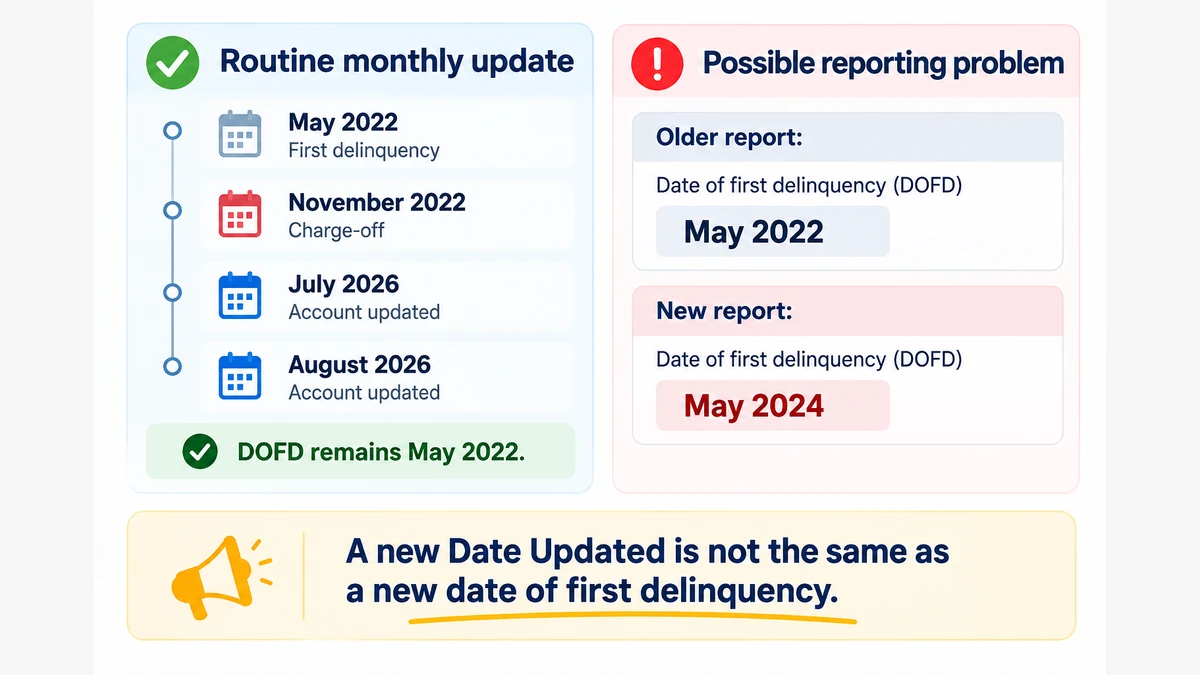
A charged-off account is not a new open account simply because it receives another update. If the same account keeps the same date of first delinquency and historical charge-off information, a newer update date alone does not turn it into a newer charge-off.
Does monthly charge-off reporting restart the seven-year period?
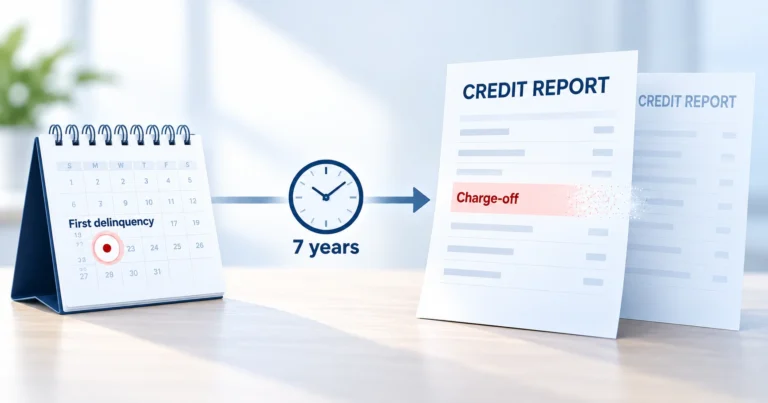
No, not by itself. Federal law ties the reporting-period calculation for charged-off accounts to the delinquency that immediately preceded the charge-off or collection activity. The statute provides that the seven-year period begins after a 180-day period starting from that delinquency.
The FTC has also explained that later events such as sale of the charged-off account, a consumer payment, or a dispute do not change the allowable reporting period. So a fresh monthly update date does not, on its own, reset the clock.
For the full timeline, see how long a charge-off stays on your credit report.
| Field | What it tells you |
|---|---|
| Date Updated | When account information was most recently reported or refreshed |
| Date of first delinquency | The beginning of the continuous delinquency that led to the charge-off |
| Collection account date opened | May reflect when a collector acquired the debt. It is not a replacement for the original delinquency date. |
| Last payment date | Identifies a payment. A later payment does not, by itself, set a new federal credit-reporting period. |
What if your report does not show the original delinquency date?
Do not substitute Date Updated, the collection opening date, or the most recent payment date. Mark the delinquency date as unknown and compare older reports and the original creditor’s payment history. Ask the bureau or furnisher which delinquency date supports the reporting timeline.
Experian explains that a collection’s open date can reflect its acquisition by a collector, while its reporting duration follows the original delinquency. If that specific field looks wrong, use the collection date-opened guide to distinguish the dates before disputing.
Example: a continuous delinquency begins in 2021, a collector acquires the debt in 2024, and the report updates in 2026. Those dates describe different events. The 2026 update alone does not establish a new delinquency in 2026.
Is each monthly CO code a new charge-off?
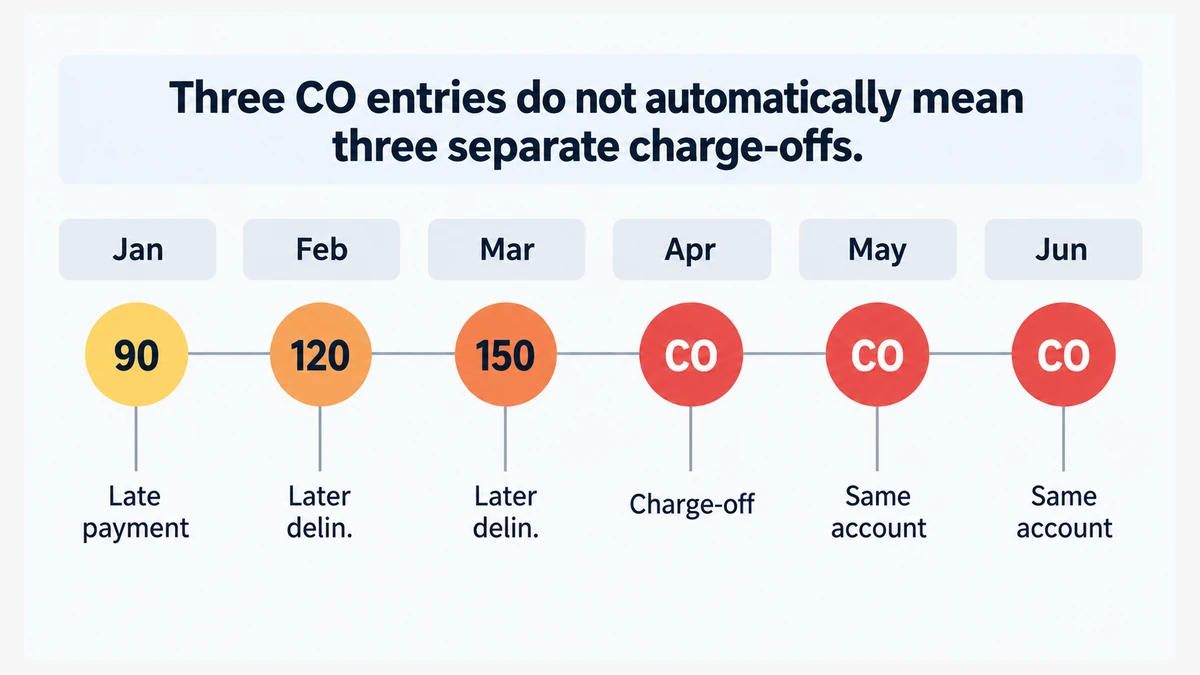
No. A payment-history grid can show “CO,” “C/O,” or a charge-off status in more than one month for the same account. Repeated codes do not automatically mean the creditor created a separate charge-off each month.
To confirm you are looking at one tradeline, compare the creditor or furnisher name, partial account number, balance, account status, date of first delinquency, and payment-history grid.
When should monthly reporting concern you?
Monthly reporting becomes more important when a material field changes in a way that conflicts with your records. The CFPB specifically tells consumers to check for incorrect balances, incorrect account status, incorrect dates of first delinquency, and the same debt being listed more than once.
A changed balance is not automatically an error. Compare the new amount with payments, credits, settlement terms, and other account activity. If you cannot reconcile the amount, document the difference before disputing it. You can also review why a charge-off balance may increase.
Compare the reported balance and status with your payoff confirmation, final statement, or written settlement agreement. If the report still shows a current balance that conflicts with those records, use the paid charge-off balance guide. If the reporting is accurate but you are wondering about deletion, see when a paid charge-off may be removable.
- The date of first delinquency became newer. Compare an older report with the current one.
- The balance is wrong after payment or settlement. Match the report to your final statement or written settlement terms.
- The ownership or status does not fit what happened. Compare it with sale, transfer, or settlement notices.
- The same debt appears in more than one entry. First check whether one entry is the original charged-off account and the other is a collection account. Use charge-off vs. collection to compare the companies’ roles, balances, and ownership before calling it a duplicate.
- The expected removal date moved later. Check whether the underlying delinquency information changed too.
If the account has been paid but still reports a balance, use what to do when a paid charge-off still shows a balance. If you are unsure whether the item can be removed at all, see when a paid charge-off may be removable.
Run this five-step monthly charge-off audit
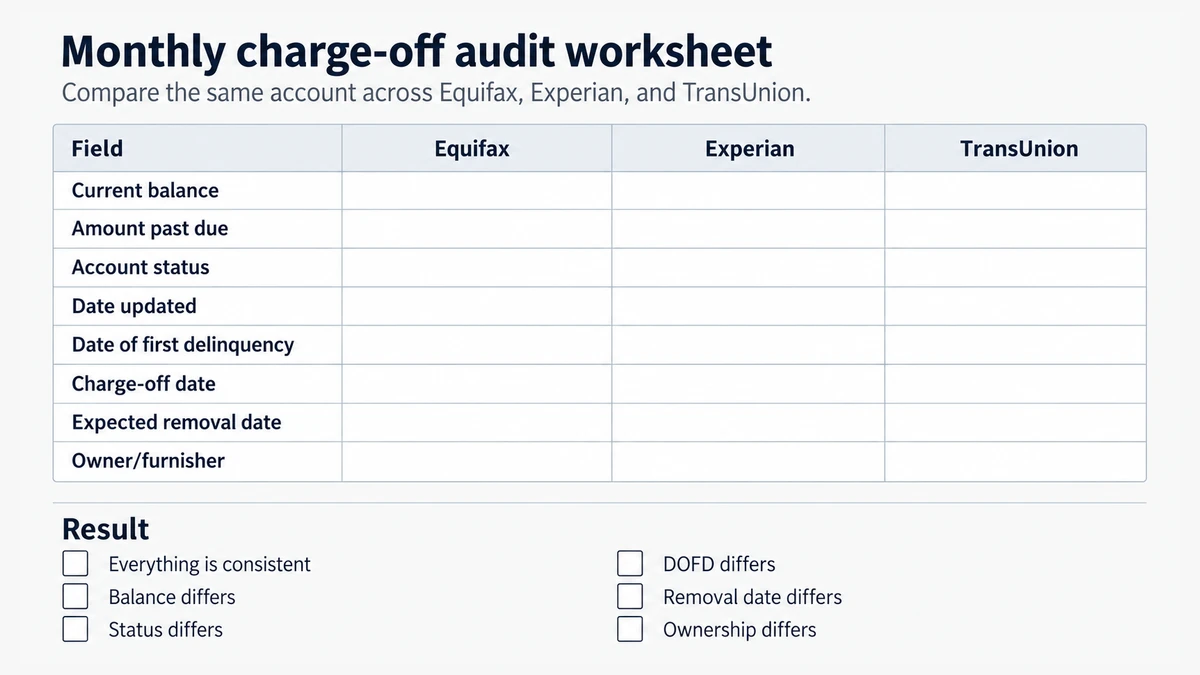
- Pull all three credit reports. Use AnnualCreditReport.com and save dated copies.
- Make sure you are comparing the same tradeline. Match the creditor name and account identifier.
- Record the key fields. Balance, status, owner or furnisher, Date Updated, date of first delinquency, and estimated removal date.
- Compare with an older report. Look for an exact field that changed.
- Classify the result. Routine update, legitimate account change, or a specific discrepancy that needs investigation.
What evidence should you save if something looks wrong?
| Problem | Useful evidence |
|---|---|
| Wrong delinquency date | Older credit reports, statements, payment history |
| Paid balance still reported | Payoff confirmation, final statement, bank or payment record |
| Settlement not reflected correctly | Written settlement agreement and proof of completion |
| Possible duplicate | Copies of both tradelines with names, balances, and identifiers |
| Ownership or status appears wrong | Sale, transfer, settlement, or closing correspondence |
A useful test is to finish this sentence: “My credit report shows ___, but my records show ___.” That identifies a disputeable fact much more clearly than “this charge-off keeps updating.”
How to dispute inaccurate monthly charge-off reporting
If you find a specific inaccurate or incomplete field, dispute that field. The CFPB recommends contacting both the credit reporting company that shows the error and the company that furnished the information.
- Name the exact account and field that is wrong.
- State what the report currently shows.
- State what your records show instead.
- Attach copies of evidence supporting the correction.
- Request the correction that matches the problem.
- Save the dispute, confirmation, and result.
For the complete process, see how to dispute an error on your credit report.
Example of a specific dispute
“My current report shows a date of first delinquency of May 2024 for account ending 4821, but my earlier credit report and account statements show that the continuous delinquency began in May 2022. Please investigate and correct the date of first delinquency based on the attached records.”
Does a charge-off hurt your score again every month?
There is no universal, fixed point penalty applied each time a charged-off account receives an update. A credit score is calculated from the information in the file used at that time, and the effect of any change depends on the rest of the credit profile and the scoring model.
If your score changes after an update, compare the underlying report data rather than assuming the newest Date Updated created another separate score penalty.
Your next step
Save the report and monitor the underlying delinquency date, balance, status, and removal timeline.
Compare it with your account records and document the exact difference before disputing it.
Compare older credit reports and statements and review the charge-off reporting timeline.
Check the reported balance and status against your payoff or settlement records, then use the paid charge-off balance guide if they conflict.
Frequently asked questions
Is a charge-off reported again every month?
A charged-off account can continue receiving monthly updates, but that does not mean a brand-new charge-off is created each month.
Does a newer Date Updated restart the seven-year reporting period?
No. A newer update date by itself does not restart the federal credit-reporting period. The relevant delinquency timeline is separate from routine account updates.
What should I compare if a charge-off keeps updating?
Compare the balance, account status, owner or furnisher, date of first delinquency, payment-history codes, and expected removal timeline.
When should I dispute an update?
Dispute a specific field when it conflicts with reliable records or is otherwise inaccurate or incomplete. Do not dispute an accurate update solely because it is recent.
Bottom line
A charge-off can keep receiving monthly updates without becoming a new charge-off each month. A newer update date does not by itself restart the federal reporting period or prove re-aging.
Compare the actual fields that matter: balance, status, ownership, date of first delinquency, payment history, and expected removal timeline. If a specific field conflicts with your records, document that discrepancy and address it directly.
Related guides
- Charge-offs hub — reporting, payment, balances, and removal questions.
- How long a charge-off stays on your credit report — understand the reporting timeline.
- Paid charge-off still showing a balance — what to check if a paid account still reports money owed.
Sources
Sources checked September 17, 2026.
- Consumer Financial Protection Bureau — Common credit report errors
- Consumer Financial Protection Bureau — How to dispute an error
- 15 U.S.C. § 1681c — Credit-reporting periods
- Federal Trade Commission — Advisory Opinion to Amason
- AnnualCreditReport.com — Federally authorized credit reports
Educational note: This article provides general U.S. credit-reporting information and is not individualized legal, financial, debt-settlement, or credit-repair advice.