In this guide
- What the grace period actually covers
- Minimum payment and interest avoidance are separate goals
- Illustrative example: a normal purchase cycle
- What changes when you carry a balance?
- Cash advances and promotions need their own check
- How to check whether the grace period has returned
- Set up a routine you can sustain
- If the payment was late or the charge seems wrong
- Understand credit card interest charges
- Sources
Quick answer: A credit card grace period can let you avoid interest on purchases when you meet the card’s full-payment conditions. It is not extra time to pay after the due date, and it generally does not protect cash advances. If you carry a balance or lose the purchase grace period, new purchases may begin accruing interest immediately. Check your agreement, the statement balance, and the amount required to preserve or regain the grace period instead of assuming that paying the minimum prevents interest.
What the grace period actually covers
The CFPB describes a grace period as the interval between the billing-cycle end and the payment due date. Cards are not required to offer one, although many provide a purchase grace period. Its interest benefit depends on meeting the applicable payment conditions.
For timing, the CFPB says issuers must have procedures to send or deliver credit card bills at least 21 days before payment is due. This is not a promise of 21 interest-free days after every purchase: the purchase date, statement cycle, and whether your account qualifies for a grace period all matter. Read the actual dates on your statement.
This is different from the due date itself. If your payment is due on the 20th, a purchase grace period does not mean you can wait until the 25th without consequences. Our statement-date versus due-date guide explains how those dates work together.
Find the agreement section describing how to avoid paying interest. Record which transactions qualify and what amount must be paid. Also check whether you already have an interest-bearing or promotional balance, because that can change the answer.
Minimum payment and interest avoidance are separate goals
| Action | What it addresses | What it does not establish |
|---|---|---|
| Pay the required minimum on time. | The minimum contractual payment for that statement. | That purchase interest will be avoided. |
| Pay the statement balance under an applicable grace period. | The card’s purchase-interest avoidance conditions. | That every transaction type receives the same treatment. |
| Pay the current displayed balance. | The amount currently shown in the account. | That all accrued but unbilled interest has been included. |
| Make a payment after the due date. | Reduces the unpaid amount when received. | That the original deadline was met. |
Our minimum-payment versus statement-balance autopay comparison is useful when selecting an automatic payment setting. A setting that prevents a missed minimum is not necessarily a setting that avoids interest.
Illustrative example: a normal purchase cycle
Assume a card has an active purchase grace period, no carried balance, and no complicating promotional or cash-advance transactions. A statement closes with $600 due. The due date on that statement is April 25. Under these assumptions, paying the required full statement balance by that date can avoid interest on those purchases.
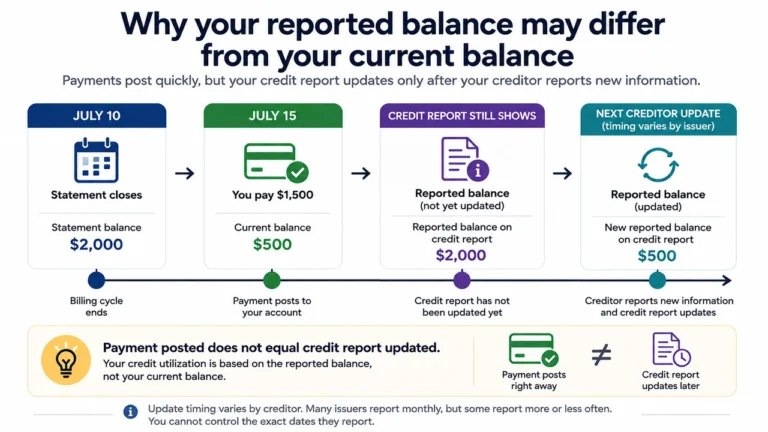
Now imagine the app shows $750 because you made another $150 in purchases after the statement closed. That difference does not automatically mean the $600 statement amount was wrong. Identify which cycle contains the newer purchases and read the statement rather than treating every displayed balance as the amount due that day.
This example assumes the grace period is already available. If you were carrying debt, do not copy its payment strategy without checking how interest applies to your account.
What changes when you carry a balance?
If you are considering leaving part of a bill unpaid to improve your score, read carrying a balance versus paying in full. A reported balance and an unpaid statement remainder are different things.
The CFPB explains that losing the grace period can result in interest on the unpaid amount and on new purchases from their transaction dates. A small unpaid remainder can therefore matter beyond the dollar amount you intentionally left behind.
Suppose you planned to pay $600 but only $550 posted. Investigate the difference: was the payment amount entered incorrectly, was a second payment returned, or did you misunderstand the statement? Confirm the remaining amount and ask the issuer how it affects interest and future purchases.
Do not rely on a score dashboard to detect this problem. Whether an account is charging interest is a billing question. It can matter to your finances before any credit-report change attracts your attention.
Cash advances and promotions need their own check
The cost and reporting consequences are separate. Our cash advance and credit-score guide explains how the added balance can affect utilization and provides a checklist for estimating fees and repayment needs.
Purchase grace periods generally do not apply to cash advances. The CFPB notes that interest on those transactions usually starts immediately. Before withdrawing cash or using a convenience check, read the transaction-specific APR and fees.
A promotional interest offer is also not the same concept as a regular purchase grace period. Read which balances the promotion covers, when it ends, and what happens to new purchases. Do not infer that a low rate on one balance means every transaction on the card is interest-free.
For offers advertised as “no interest if paid in full,” compare deferred interest with true 0% APR. Missing the promotional payoff deadline can add accrued interest from the purchase date, even when only a small balance remains.
If several balance types appear on your statement, check how your payment is divided between purchases, transfers, and cash advances. Paying extra does not necessarily reduce the balance you intended. Ask the issuer what amount satisfies your purchase grace-period conditions.
How to check whether the grace period has returned
The CFPB warns that not paying in full can affect the grace period for that month and the following month. A full payment today therefore does not necessarily restore interest-free purchases immediately. Ask which statement balances must be paid, by which due dates, and when new purchases qualify again; the agreement controls the exact requirements.
My account has been charging interest. What amount must I pay, and by what date, to satisfy the conditions for a purchase grace period again? Are there any balances or accrued interest not included in the amount I currently see? How can I confirm the grace period is active?
Keep the response and review the following statement. The CFPB’s explanation of interest after a payment emphasizes that interest can continue until payment is received and that the card agreement controls the details.
Set up a routine you can sustain
- Read the statement when issued and identify its required payment and due date.
- Confirm whether the purchase grace period applies to the current account.
- Check the payment amount and available bank funds before the withdrawal date.
- Verify the payment posted and was not returned.
- Review the next statement’s interest section instead of assuming the matter is finished.
Our credit-card autopay guide covers the setup and monitoring risks. Autopay is a tool, not confirmation that the correct amount was received. If you pay manually as well, check how the issuer adjusts any scheduled withdrawal.
If the payment was late or the charge seems wrong
Contact the issuer promptly and separate the questions: what remains due, how interest was calculated, and whether any fee or reporting issue occurred. Our guide to a payment less than 30 days late explains why billing consequences and credit-bureau reporting should not be confused.
For a suspected billing error, consult the CFPB’s billing-dispute instructions and preserve the statement and payment records. A telephone conversation may clarify the calculation, but it does not replace every written notice required to preserve applicable rights.
By Claire Bennett, the editorial name used by the site’s founder and editor. Factual guidance checked against the linked official sources. Photo: Manu Del Moral / Unsplash.
Explore related guides on credit cards and utilization.
Understand credit card interest charges
Explore these focused guides for the next question you need to answer:
Sources
- CFPB: credit card grace periods
- CFPB: interest after a balance payment
- CFPB: credit card billing disputes
Sources checked October 13, 2026. General educational information for U.S. readers; not individualized financial or legal advice. Examples are illustrative and do not predict credit scores or lending decisions.