In this guide
- Quick comparison
- Should you pay a charge-off in full or settle?
- Paid charge-off vs. settled charge-off: key differences
- How does a paid vs. settled charge-off appear on your credit report?
- Does paid in full look better than settled to lenders?
- How much can you save by settling a charge-off?
- When does paying a charge-off in full make more sense?
- When does settling a charge-off make more sense?
- What should you get in writing before settling a charge-off?
- What should you do after paying or settling a charge-off?
- Does paying or settling remove a charge-off from your credit report?
- Does paying or settling restart the seven-year reporting period?
- Can settling a charge-off create tax consequences?
- Frequently asked questions about paid vs. settled charge-offs
- Bottom line: should you pay a charge-off in full or settle?
- Sources
Settled charge-off vs paid in full comes down to one main trade-off: paying in full means repaying the entire balance, while settling means the creditor accepts less than the full amount to resolve the debt. If you can afford the full balance without missing current bills or draining essential savings, paying in full is the cleaner repayment outcome. If full payment would strain your finances and you have a meaningful written settlement offer, settling may be more practical.
Neither option automatically removes an accurate charge-off from your credit reports, and neither guarantees a specific credit score increase. The better choice depends on the amount you owe, the settlement offer, what you can realistically afford, and whether you expect to apply for major credit soon. If you first need the account status explained, read what a charge-off means on your credit report. For related payment, balance, and reporting guides, browse the Charge-offs hub.
Quick comparison
| Your situation | Option to compare first |
|---|---|
| You can comfortably afford the full balance | Pay in full |
| Full payment would leave you short for essential bills or necessary savings | Settlement |
| The creditor offers a substantial reduction | Compare the settlement |
| The settlement saves only a small amount | Compare it with paying in full |
| You plan to apply for a mortgage or other major credit soon | Check the lender’s requirements before deciding |
| The debt, balance, or ownership appears incorrect | Verify the account before paying |
Next: Use the written comparison checklist below to compare your actual balance, settlement offer, available cash, and borrowing plans. It is a manual worksheet, not an interactive calculator.
Should you pay a charge-off in full or settle?
Paying in full deserves stronger consideration if the debt is valid and you can afford the entire balance without missing current bills or draining money you need for emergencies. Settlement may be more practical when full payment is not realistic and the creditor or collector agrees to accept less than the full balance.
Use this decision path
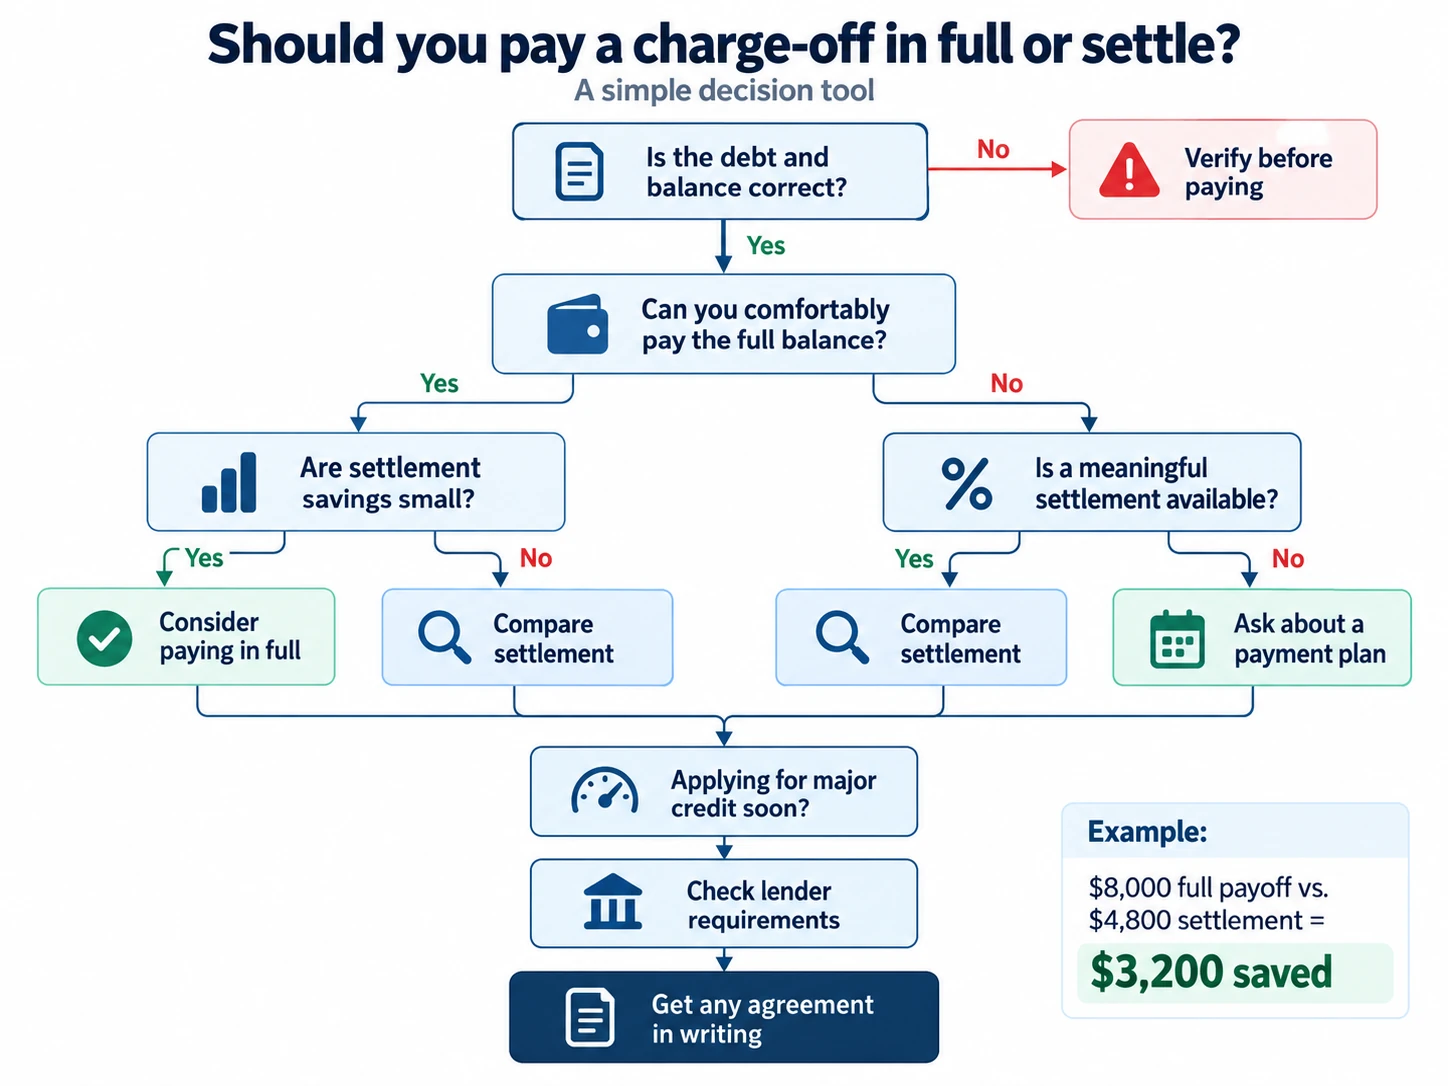
- Verify the debt and balance.
Confirm the creditor or collector name, account ownership, current balance, and account number. If anything looks wrong or you are unsure who owns the debt, verify it before sending money. - Calculate what you can safely afford.
Do not use money needed for rent, utilities, current minimum payments, or other essential expenses just to pay the charge-off in full. If full repayment would create a new financial problem, compare settlement instead. - Calculate the settlement savings.
Subtract the settlement offer from the current balance. For example, if the balance is $8,000 and the creditor agrees to accept $4,800, you would pay $3,200 less than the full balance.$8,000 − $4,800 = $3,200 in settlement savingsThat is a 40% reduction from the current balance. The larger the savings, the more important it becomes to compare the settlement with the financial benefit of paying the account in full. - Consider any major borrowing plans.
If you expect to apply for a mortgage or another major loan soon, ask the lender how it treats unresolved, paid, and settled charge-offs before choosing an option. Do not assume every lender or loan program handles them the same way. - Get settlement terms in writing before paying.
Confirm the settlement amount, payment deadline, account covered by the agreement, whether any balance will remain after completion, and any agreed reporting terms. Do not rely only on a phone promise.
Paid charge-off vs. settled charge-off: key differences
A paid charge-off means you repaid the full outstanding balance. A settled charge-off means the creditor or collector agreed to accept less than the full balance to resolve the debt. The main trade-off is simple: paying in full costs more but shows full repayment, while settlement can reduce the amount you pay.
| What to compare | Paid charge-off | Settled charge-off |
|---|---|---|
| Amount paid | Full outstanding balance | Less than the full balance under the settlement agreement |
| Repayment outcome | Full balance repaid | Creditor accepts less than the full balance |
| Cash required | Higher | Lower when a reduced settlement is accepted |
| Remaining amount under the agreement | No unpaid balance after full payment | No further amount should be due if the settlement agreement fully resolves the debt and is completed as agreed |
| Accurate charge-off automatically deleted? | No | No |
| Potential canceled debt | Generally none from the payoff itself | May exist when part of the balance is forgiven |
Example: Suppose you owe $8,000. Paying $8,000 resolves the full balance. If the creditor agrees in writing to accept $4,800 to settle the account, you pay $3,200 less, but you have resolved the debt for less than the full amount owed.
Neither option guarantees a specific credit score change. If that is your main concern, see how paying a charge-off may affect your credit score.
How does a paid vs. settled charge-off appear on your credit report?
A paid charge-off shows that you repaid the full charged-off balance. A settled charge-off shows that the creditor accepted less than the full amount to resolve the debt. An accurate charge-off can remain on your credit report after either outcome. Exact status labels and field names can vary depending on the credit report you are viewing.
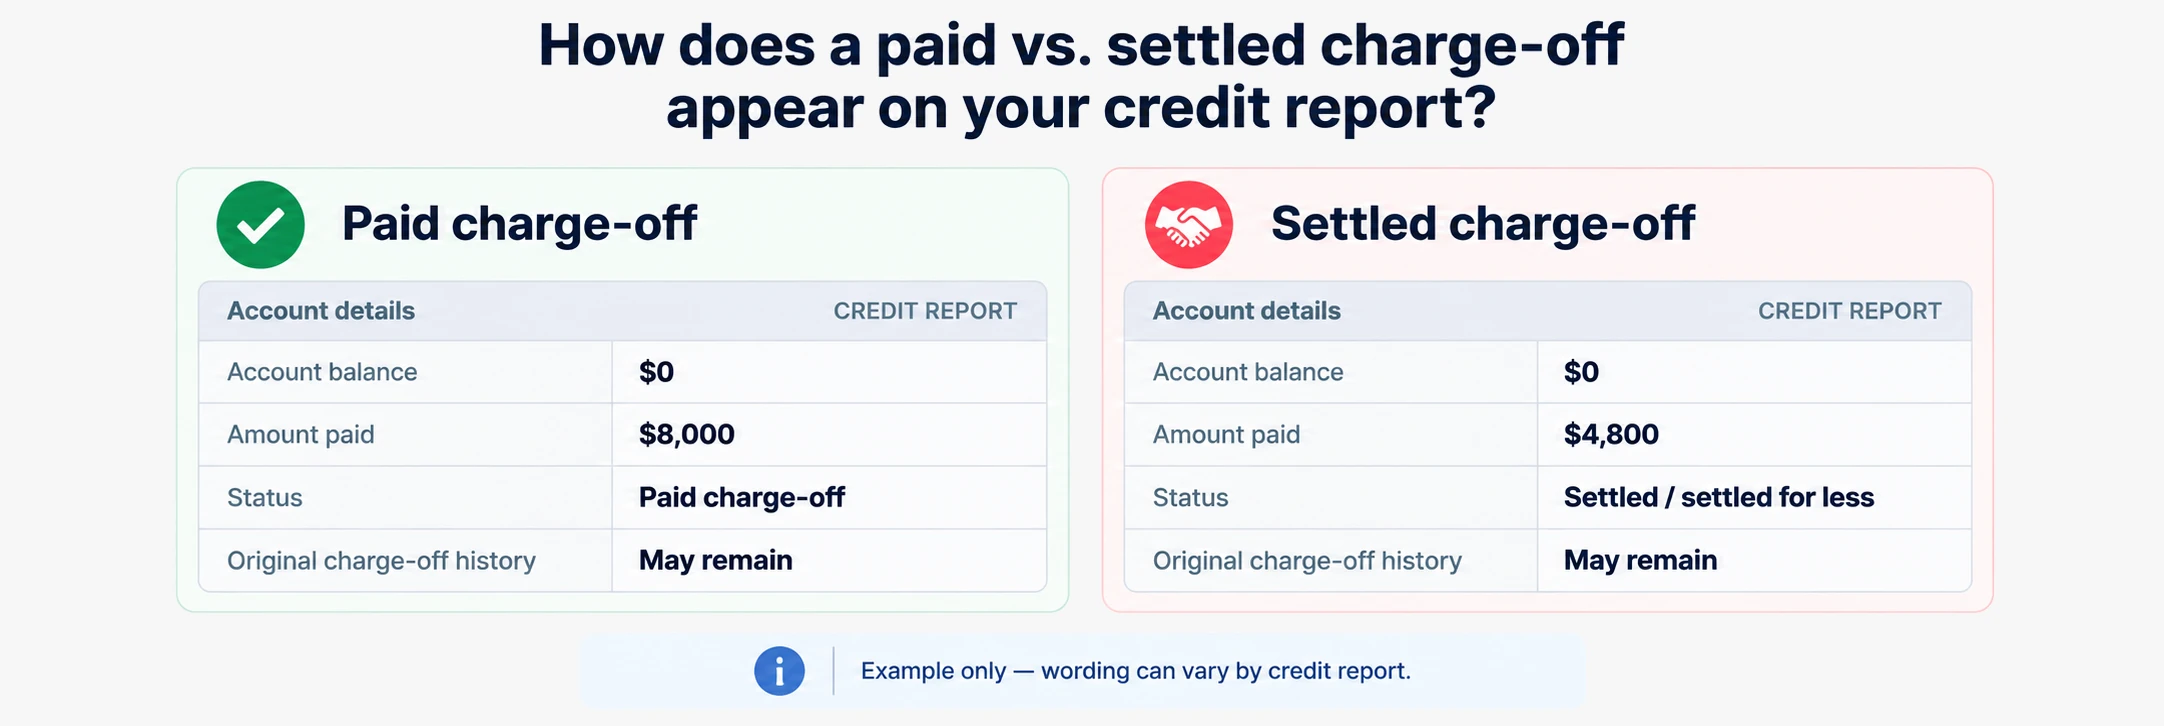
Example of how the account may change
| Credit report field | Before payment | After paying in full | After settlement |
|---|---|---|---|
| Balance | $8,000 | $0 | $0 if the settlement fully resolves the debt |
| Amount repaid | $0 | $8,000 | $4,800 in this example |
| Possible status | Charge-off | Paid charge-off | Settled charge-off or similar settlement wording |
| Original charge-off history | Present | May remain | May remain |
Example only. Credit report layouts, field names, and status wording can differ.
In this example, paying the full $8,000 changes the balance to $0 and shows that the entire charged-off balance was repaid. If the creditor instead accepts $4,800 to settle the $8,000 debt, the balance should be $0 once the settlement is completed, but the account can indicate that less than the full balance was paid.
What to check after the account is updated
- Balance: Check that it shows $0 after a completed full payoff or settlement that resolves the debt.
- Status or remarks: Confirm that the account accurately reflects whether you paid in full or settled.
- Account details: Verify the creditor or collector name and account number so you are checking the debt you actually paid.
- Your records: Compare the report with your payoff letter or settlement agreement and proof of payment.
If you are not sure where these fields appear, see how to read your credit report.
If the account still shows a balance you believe is incorrect after the payment has been reported, see what to do when a paid charge-off still shows a balance.
Does paid in full look better than settled to lenders?
Paying a charge-off in full shows that you repaid the entire balance, while settling shows that the creditor accepted less than the full amount. A lender may consider that difference during underwriting, but paying in full does not guarantee approval and settling does not automatically cause a denial.
How much the difference matters depends on the lender, loan program, whether the charge-off is still outstanding, and the rest of your application. If you are preparing for a mortgage or another major loan, check the requirements for that specific loan before deciding how to resolve the account.
What to check before you pay
| Your situation | What to ask the lender |
|---|---|
| The charge-off is still unpaid | Does this account need to be resolved before approval? |
| You can pay the full balance | Would paying it in full change how this account is treated during underwriting? |
| You have a settlement offer | Will a completed settlement satisfy your requirement for this account? |
| You are applying for a mortgage soon | Are there loan-program-specific requirements for this charge-off? |
Use a specific question: “I have a charged-off account with a balance of $8,000. I can either pay it in full or complete a settlement for $4,800. Does this account need to be resolved for this loan, and would your underwriting treat a full payoff differently from a completed settlement?”
Do not spend an extra $3,200 based only on the assumption that “paid in full” will secure an approval. Find out what the lender or loan program actually requires, then compare that requirement with the cost of each option.
How much can you save by settling a charge-off?
To measure the financial benefit of a settlement, compare the amount you would pay under the settlement with the full charged-off balance. The larger the difference, the more cash you keep, but the savings alone should not determine whether settlement is the better choice.
Calculate your settlement savings
Settlement savings = current balance − settlement amount
Settlement discount = settlement savings ÷ current balance × 100
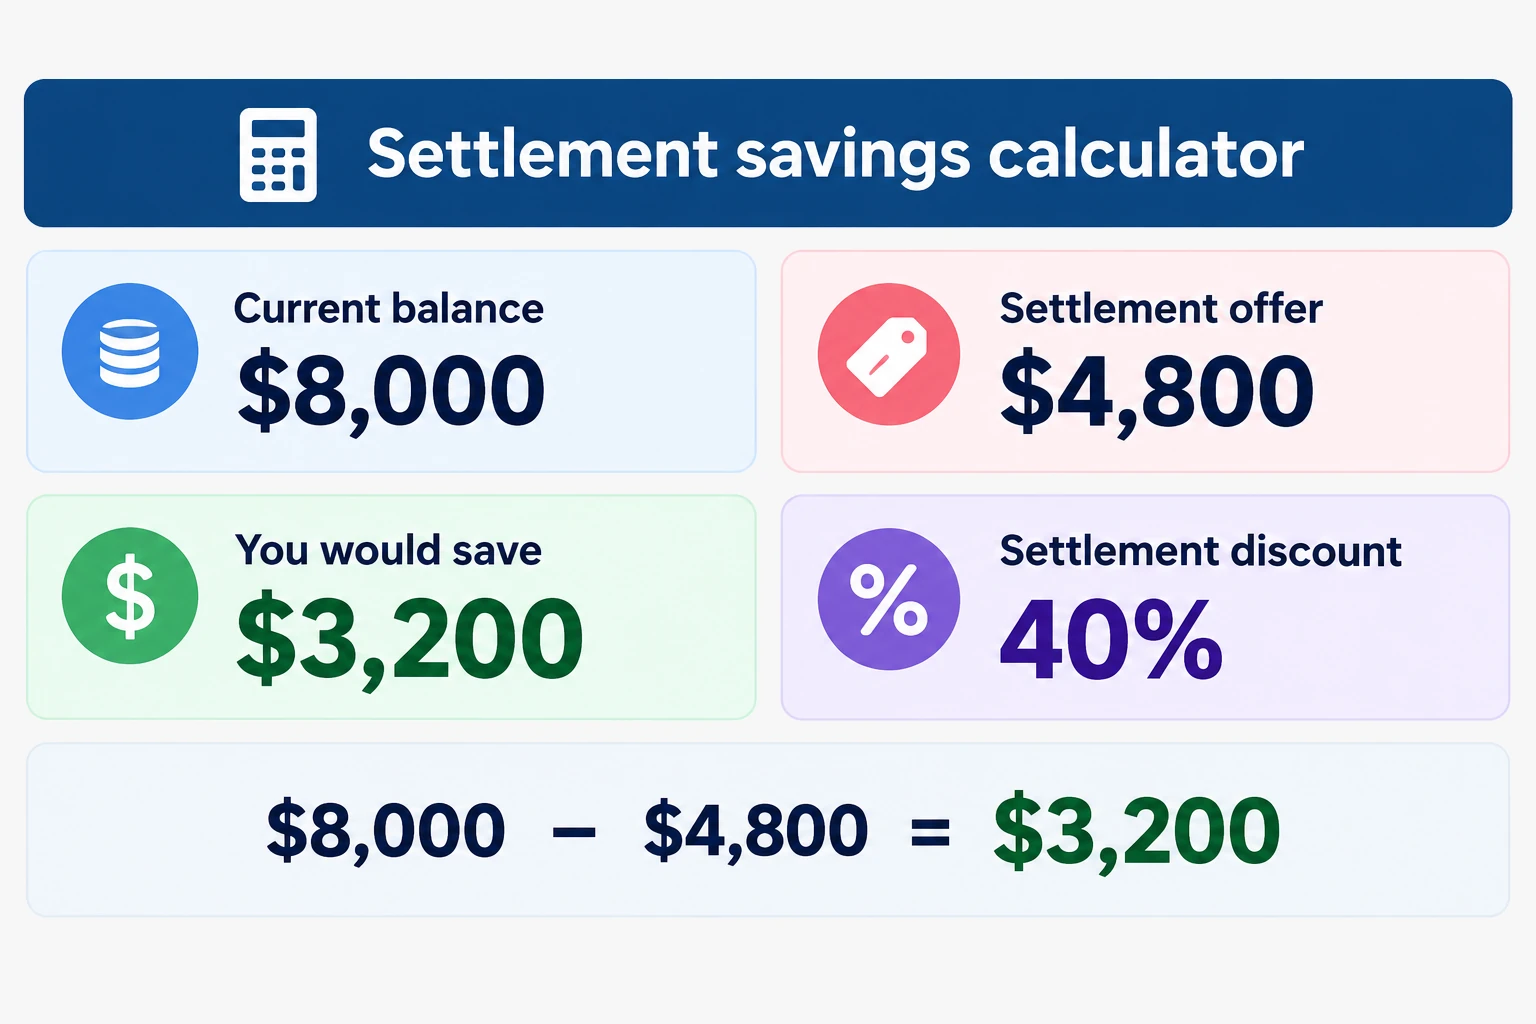
Example: Suppose your current charge-off balance is $8,000 and the creditor agrees to accept $4,800 to resolve the debt.
- Current balance: $8,000
- Settlement amount: $4,800
- Amount saved: $3,200
- Settlement discount: 40%
$8,000 − $4,800 = $3,200 saved
$3,200 ÷ $8,000 × 100 = 40% discount
Compare the cost of paying in full vs. settling
| Option | You pay | You save compared with paying in full |
|---|---|---|
| Pay in full | $8,000 | $0 |
| Settle for $6,400 | $6,400 | $1,600 |
| Settle for $5,600 | $5,600 | $2,400 |
| Settle for $4,800 | $4,800 | $3,200 |
| Settle for $4,000 | $4,000 | $4,000 |
These are hypothetical examples for comparison only. They are not typical or guaranteed settlement offers.
Is the settlement worth it?
Do not judge the offer by the percentage discount alone. Compare the dollar savings with how much cash you would have left after payment, whether paying in full would interfere with essential expenses, any upcoming borrowing plans, and whether the creditor will confirm the complete settlement terms in writing.
Example: If paying $8,000 would leave you with almost no emergency savings but a $4,800 settlement would let you keep $3,200, that difference may be financially significant. If you can comfortably pay the full $8,000 and the settlement saves only a small amount, paying in full may deserve stronger consideration.
When does paying a charge-off in full make more sense?
Paying a valid charge-off in full may make more sense when you can afford the entire balance without missing current payments or using money needed for essential expenses. It may also be worth considering when the settlement saves relatively little or a lender gives you a specific reason to resolve the account in full.
You can afford the full balance
Compare the payoff with the cash you will have left afterward. If paying the charge-off will not interfere with housing, utilities, current minimum payments, or necessary emergency savings, full repayment may be financially manageable.
The settlement saves only a small amount
Look at the dollar difference between the two options.
Example: Suppose your charge-off balance is $8,000 and the creditor offers to settle for $7,400.
| Option | You pay | Difference |
|---|---|---|
| Pay in full | $8,000 | — |
| Settle | $7,400 | $600 less |
If the extra $600 is affordable, paying the full balance may deserve stronger consideration. If the settlement would save several thousand dollars, the trade-off would be different.
A lender gives you a specific requirement
If you expect to apply for a mortgage or another major loan soon, ask the lender whether the charge-off must be resolved and whether a completed settlement would satisfy its underwriting requirements. Do not pay more solely because you assume every lender requires payment in full.
Full repayment fits your priorities
You may prefer to repay the entire balance rather than resolve the account for less. If the additional cost is manageable and does not create a new financial problem, that preference can be part of your decision.
Check these numbers before paying in full
- Current balance: Confirm the amount you actually owe.
- Full payoff amount: Get the amount required to resolve the entire balance.
- Settlement amount: Compare any written settlement offer with the payoff.
- Dollar difference: Calculate how much more full payment would cost.
- Cash remaining: Check what you would have left after each option.
- Upcoming borrowing: Verify any lender-specific requirements before sending payment.
When does settling a charge-off make more sense?
Settling a valid charge-off may make more sense when paying the full balance would strain your current finances and the creditor agrees to accept a meaningfully lower amount to resolve the debt. The settlement should fit your budget, fully resolve the agreed obligation, and be confirmed in writing before you pay.
Paying in full would leave you short on essential expenses
Compare how much money you would have left after each option. If paying the full balance would make it difficult to cover housing, utilities, minimum debt payments, or necessary emergency expenses, settlement may be the more practical choice.
The settlement saves a meaningful amount
Focus on the dollar difference between paying in full and settling.
Example: Suppose your charge-off balance is $8,000 and the creditor agrees to settle the account for $4,800.
| Option | You pay | Cash you keep compared with paying in full |
|---|---|---|
| Pay in full | $8,000 | $0 |
| Settle | $4,800 | $3,200 |
If paying $8,000 would leave you with $500 in available cash but settling for $4,800 would leave you with $3,700, the $3,200 difference may materially affect your ability to handle current expenses or an emergency.
Full repayment is not realistic
If you cannot reasonably pay the full balance but can complete an affordable settlement, resolving the debt for less may be more realistic than agreeing to payments you may not be able to finish.
The agreement clearly resolves the debt
Before sending settlement money, confirm in writing the exact amount you must pay, the payment deadline, the account covered by the agreement, and what will happen to the unpaid portion after you complete the settlement.
Check these details before choosing settlement
- Current balance: Verify how much you actually owe.
- Settlement amount: Confirm the exact amount required to complete the agreement.
- Dollar savings: Subtract the settlement amount from the full balance.
- Cash remaining: Compare how much money you would have left under each option.
- Payment terms: Confirm whether the settlement requires one payment or multiple payments.
- Written confirmation: Make sure the agreement explains what happens once you complete the required payment.
What should you get in writing before settling a charge-off?
Before you make a settlement payment, get a written agreement that identifies the debt, states the exact amount you must pay, and confirms what happens when you complete the agreement. If you are dealing with a debt collector, the CFPB recommends getting the repayment or settlement plan and the collector’s promises in writing before making a payment.
Check these terms before you pay
| What to check | What the written agreement should tell you |
|---|---|
| Company | The creditor or debt collector accepting the settlement |
| Account | The specific debt or account covered by the agreement |
| Settlement amount | The exact dollar amount you must pay |
| Payment terms | Whether you must make one payment or a series of payments |
| Due dates | When each required payment must be received |
| Completion | That completing the required payments satisfies the debt under the settlement agreement |
| Remaining balance | What happens to the portion of the balance you are not paying |
| Collection activity | Any promises about ending collection efforts after you complete the settlement |
| Credit reporting | Any specific reporting-related commitment the creditor or collector has actually agreed to make |
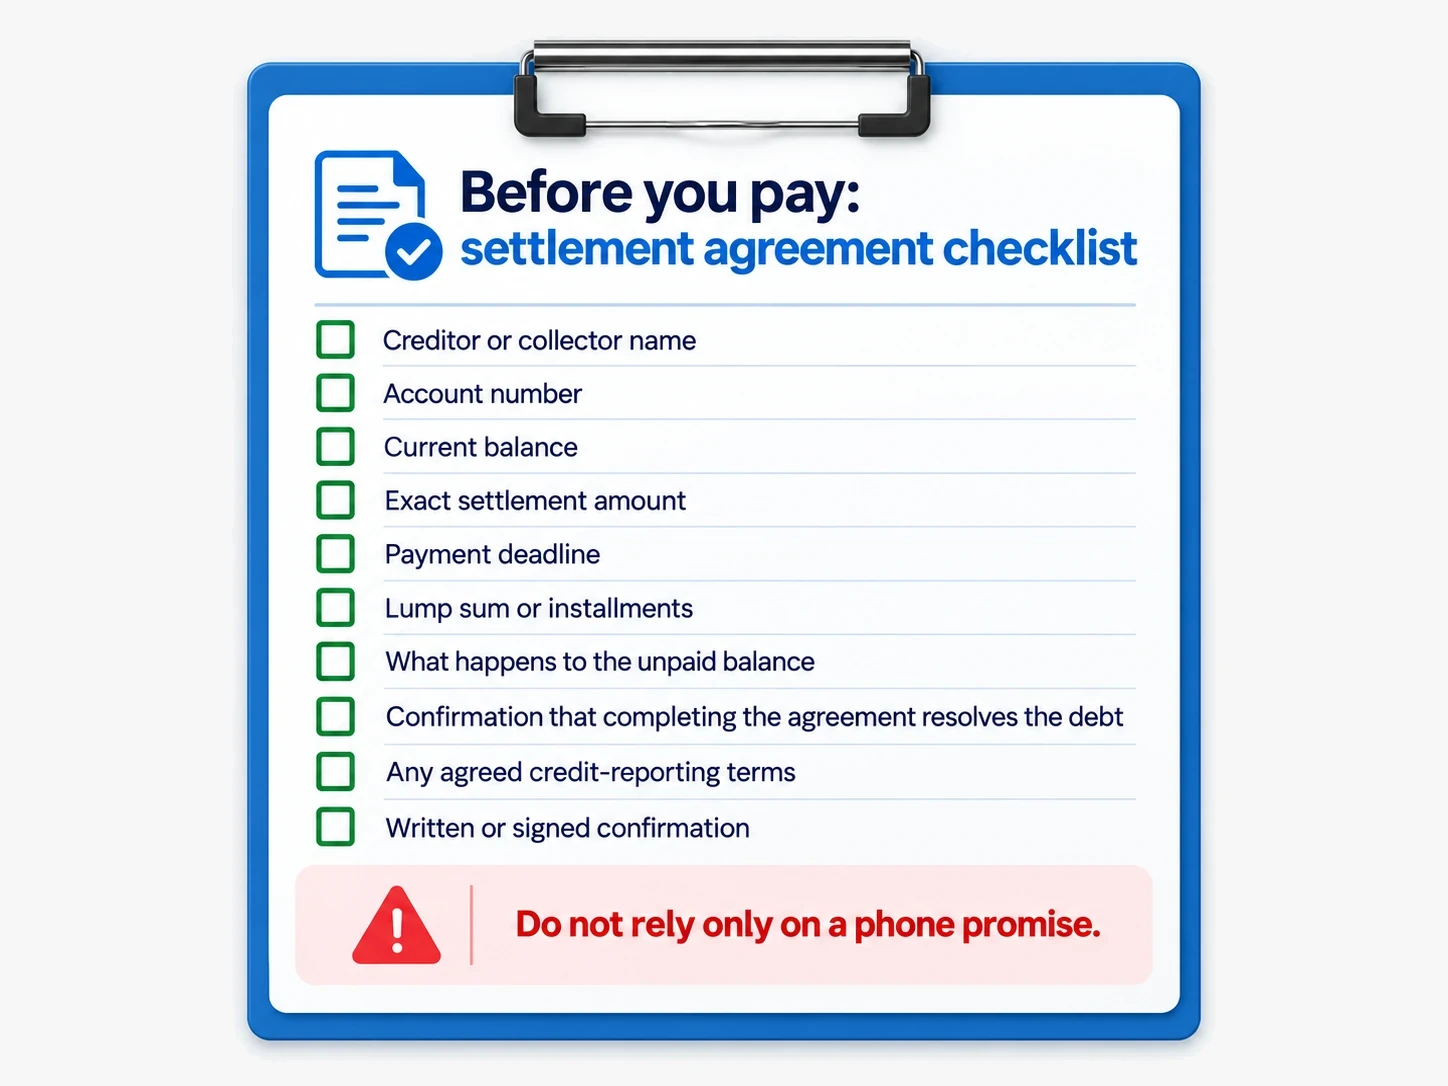
The FTC advises consumers settling with a debt collector to get a signed letter stating that the agreed payment settles the entire debt and that no additional amount will be owed on that debt. Keep that agreement together with proof of every payment you make.
Do not send payment if these points are unclear
- The amount: You do not know exactly how much you must pay.
- The deadline: The agreement does not clearly state when payment is due.
- The debt: You cannot tell which account the settlement covers.
- The remaining balance: The agreement does not explain what happens to the unpaid portion.
- The final outcome: It is unclear whether completing the required payments resolves the debt under the agreement.
- A verbal promise is missing: A term that influenced your decision appears in the phone conversation but not in the written agreement.
Use this script before accepting the settlement
“Before I make a payment, please send me the complete settlement agreement in writing. It should identify the account, state the exact amount and payment deadline, explain what happens to the remaining balance, and confirm that completing the required payments resolves the debt under the agreement.”
If the written agreement differs from what you were told by phone, ask for the document to be corrected before you pay.
Official guidance: CFPB: How do I negotiate a settlement with a debt collector? and FTC: Debt collection FAQs.
What should you do after paying or settling a charge-off?
After you pay or settle a charge-off, save your documents and verify that the account is updated accurately on your credit reports. Focus on the balance, account status, and whether the reported information matches what actually happened.
1. Save proof that the debt was resolved
Keep records that show both the agreement and the completed payment:
- Payoff confirmation or settlement agreement
- Payment receipt or confirmation number
- Bank or card record showing the payment
- Emails or letters from the creditor or collector
- Any written confirmation that the agreement was completed
Do not discard these records after the account updates. You may need them later if the balance or status is reported incorrectly.
2. Check the updated account on your credit reports
Compare the reported account with your payment records. Check the creditor or collector name, account number, current balance, and account status or remarks.
| What to check | After paying in full | After settlement |
|---|---|---|
| Current balance | Should show no remaining balance after full payment is reported | Should show no remaining balance if the completed settlement fully resolved the debt |
| Account status or remarks | Should accurately reflect that the balance was paid | Should accurately reflect that the account was settled |
| Account details | Confirm the correct account was updated | Confirm the correct account was updated |
If you need help finding these fields, see how to read your credit report.
3. Compare the reported information with your agreement
Example: Suppose you settled an $8,000 charge-off for $4,800, and the written agreement states that completing the $4,800 payment resolves the debt. If the account later shows a current balance that does not match the completed agreement, compare the report with your settlement letter and proof of payment.
Do not treat the continued presence of the original charge-off as an error by itself. Paying or settling an accurate charge-off does not automatically erase the negative history.
4. Take action if the balance or status is inaccurate
If the updated balance, payment status, or other account information does not match your records, gather the credit report showing the problem, your payoff or settlement agreement, and proof of payment. You can dispute information that is inaccurate or incomplete with the credit reporting company and the company that furnished the information.
If the specific problem is a remaining balance after the account was resolved, see what to do when a paid charge-off still shows a balance.
Do not dispute an accurate charge-off simply because you want it removed. The dispute process is for information that is inaccurate, incomplete, duplicated, outdated, fraudulent, or otherwise incorrectly reported.
After-payment checklist
- ☐ Save the payoff or settlement agreement
- ☐ Save proof of every payment
- ☐ Check the reported balance
- ☐ Check the account status or remarks
- ☐ Confirm the correct account was updated
- ☐ Compare the report with your written agreement
- ☐ Gather supporting records if anything is reported incorrectly
Does paying or settling remove a charge-off from your credit report?
No. Paying or settling an accurate charge-off does not automatically remove it from your credit report. Resolving the debt can change the current balance and account status, but the earlier charge-off can remain as part of the account history.
Example: Suppose your credit report shows an $8,000 charged-off balance. If you pay the full $8,000, the balance should be updated to reflect that the debt was paid. If you complete a $4,800 settlement that fully resolves the debt, the balance should reflect the completed settlement. In either case, the accurate charge-off itself does not automatically disappear.
What should change after payment or settlement?
| Credit report information | What to expect |
|---|---|
| Current balance | Should reflect the completed payoff or settlement |
| Account status or remarks | Should accurately reflect whether the account was paid or settled |
| Original charge-off history | May remain if it is accurate and still reportable |
When is the reported charge-off worth checking?
Check the account more closely if the balance, payment status, account ownership, dates, or other reported details do not match your records. Do not dispute an accurate charge-off only because you paid or settled it.
Example: If the report correctly shows that the account was previously charged off but still shows an $8,000 current balance after you paid the full amount, the balance may be the issue to investigate. The historical charge-off is a separate question.
For a full explanation of when removal may be possible, see whether a paid charge-off can be removed from your credit report.
Does paying or settling restart the seven-year reporting period?
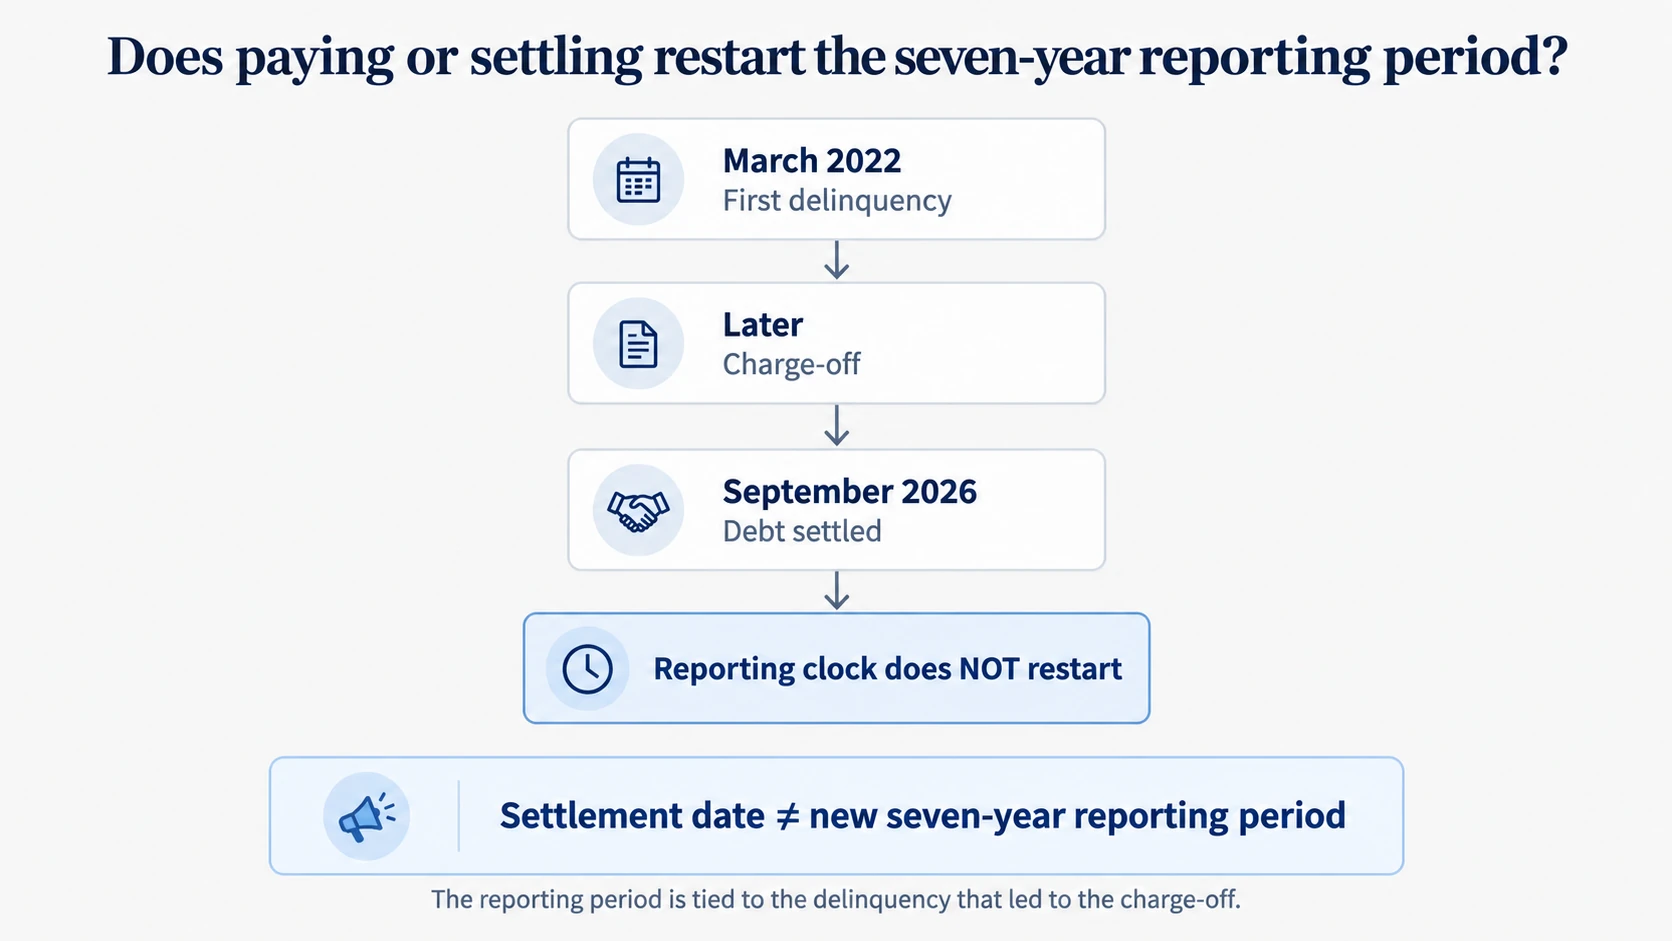
No. Paying or settling a charge-off does not restart the federal credit reporting period for the original charge-off. The Fair Credit Reporting Act ties the reporting period to the delinquency that led to the charge-off, not to a later payoff or settlement date.
For a delinquent account that is charged off, placed for collection, or subjected to similar action, the FCRA provides that the seven-year period begins after a 180-day period measured from the start of the delinquency that immediately preceded that action.
Example
Suppose an account first became delinquent in March 2022, was later charged off, and you settled it in September 2026. The September 2026 settlement does not create a new seven-year reporting period for the original charge-off.
| What happens later | Does it restart the reporting period? |
|---|---|
| You pay the charge-off in full | No |
| You settle the charge-off for less | No |
| The balance updates to $0 | No |
| The account status updates to paid or settled | No |
Payment can change the current balance and account status, but it does not give the original charge-off a new federal reporting period.
Do not confuse credit reporting time limits with the statute of limitations for collecting or suing over a debt. Those are separate issues, and debt-collection limitation periods can depend on state law and the type of debt.
For the full timeline, see how long a charge-off stays on your credit report.
Official source: 15 U.S.C. § 1681c — Fair Credit Reporting Act reporting limits.
Can settling a charge-off create tax consequences?
Yes. If you settle a charge-off for less than the amount you owe, the canceled portion of the debt may be taxable income. However, canceled debt is not automatically taxable in every case because IRS exceptions and exclusions may apply, including bankruptcy and insolvency.
Calculate the potentially canceled amount
Canceled amount = balance before settlement − amount paid
Example: Suppose you owe $8,000 and the creditor agrees to accept $4,800 to fully settle the debt.
$8,000 − $4,800 = $3,200 potentially canceled debt
The $3,200 difference is the amount to review for possible tax consequences. It does not mean you automatically owe tax on $3,200.
What should you check after the settlement?
- Balance before settlement: Confirm how much you owed before the agreement.
- Amount paid: Keep proof of the amount you actually paid.
- Amount canceled: Compare the unpaid portion with your settlement records.
- Form 1099-C: If you receive one, compare the canceled-debt amount with your records.
- Possible exclusions: Check whether an IRS rule, such as the bankruptcy or insolvency exclusion, applies to your situation.
If you receive a Form 1099-C with information that does not match your records, review it against your settlement documents and contact the creditor about any apparent error. Do not assume that receiving the form means the entire amount shown is necessarily taxable.
Official source: IRS Publication 4681: Canceled debts, foreclosures, repossessions, and abandonments.
Frequently asked questions about paid vs. settled charge-offs
Can you settle a charge-off after it has been sold to a debt collector?
Yes, a settlement may still be possible, but first confirm who currently owns the debt and who is authorized to accept payment. Review the collector’s validation information, including the creditor name, amount claimed, and account details, before negotiating or sending money.
If the original creditor sold the debt, the collector or debt buyer may now be the party you need to deal with. If you are unsure how the two accounts relate, see the difference between a charge-off and a collection account.
Can you pay a charge-off in installments?
Possibly. A creditor or debt collector may agree to a repayment or settlement plan with multiple payments instead of one lump sum. Before making the first payment, get the amount of each payment, due dates, total amount required, and what happens after the final payment in writing.
Can a creditor refuse to settle a charge-off?
Yes. A creditor or debt collector can decline your settlement proposal or offer different terms. Do not assume that a specific discount is available. If your offer is rejected, ask what repayment or settlement options are available and compare the total cost with what you can realistically afford.
Can you negotiate a charge-off settlement yourself?
Yes. You can contact the creditor or debt collector yourself and make a repayment or settlement proposal. Before negotiating, confirm that you owe the debt, verify the current balance, decide the maximum amount you can afford, and keep notes of the offer and response.
If an agreement is reached, ask for the complete terms in writing before making a payment. Do not rely only on a verbal promise that a certain payment will resolve the debt.
What if you cannot afford to pay in full or settle?
Do not commit to a payment that would leave you unable to cover essential current expenses. Calculate what you can realistically afford, ask whether a lower payment arrangement or different settlement option is available, and compare the total amount required before agreeing.
If no workable option is available, avoid promising payments you cannot complete. Keep records of the account and any offers you receive while you evaluate your next step.
Bottom line: should you pay a charge-off in full or settle?
If you can afford the full balance without falling behind on current bills or draining essential savings, paying a valid charge-off in full shows that you repaid the entire debt. If paying in full would put your finances under pressure and you have a meaningful written settlement offer, settling may be the more practical choice.
Compare the options in actual dollars before deciding. Check the full payoff amount, the settlement amount, how much the settlement would save you, and how much money you would have left after each option.
- Pay in full first if you can comfortably afford it and the settlement would save only a small amount.
- Compare settlement first if full repayment would leave you short for essential expenses or the settlement would save a meaningful amount.
- Check with the lender first if you plan to apply for a mortgage or another major loan soon and the treatment of the charge-off could affect underwriting.
Before sending money, verify that the debt and balance are correct and get any settlement agreement in writing. Do not choose the more expensive option based only on the assumption that it will produce a particular credit score or loan-approval result.
Sources
- Consumer Financial Protection Bureau: How do I negotiate a settlement with a debt collector?
- Consumer Financial Protection Bureau: Is it possible to remove accurate but negative information from my credit report?
- Consumer Financial Protection Bureau: How do I dispute an error on my credit report?
- Federal Trade Commission: Debt collection FAQs
- 15 U.S.C. § 1681c: Requirements relating to information contained in consumer reports
- IRS Publication 4681: Canceled debts, foreclosures, repossessions, and abandonments
This article is for general educational purposes and is not legal, tax, or individualized financial advice. Lending requirements, debt-collection rules, and tax treatment can depend on your circumstances.