In this guide
- Quick answer: which balance should be reported?
- Example: one debt reported under two tradelines
- First determine whether the debt was sold or assigned
- Compare the two tradelines field by field
- Red flags that one of the reported balances may be wrong
- What documents should you gather before disputing a balance?
- What to do if one of the reported balances is wrong
- What if the disputed balance is verified?
- Who should you pay when both companies report a balance?
- Can paying one company update both credit report entries?
- How long should you wait for both balances to update?
- Does the same debt count twice against your credit score?
- Frequently asked questions
- Sources and review
An original creditor and collection agency can both report the same debt, but that does not mean you owe it twice. If the debt was sold, the original creditor’s current balance should generally be $0; the buyer or its collector reports the unpaid debt. If the creditor only hired a collection agency, it may still own the debt and report a balance.
The key is to distinguish two account entries from two separate amounts you owe. Check ownership, balance labels, and reporting dates before paying anyone or disputing a record. This guide focuses on an original creditor plus a collector. For two collection agencies reporting the same debt, see duplicate collection accounts.
Quick answer: which balance should be reported?
| Situation | Original creditor’s current balance | Collection entry | Your next check |
|---|---|---|---|
| The debt was sold | Generally $0 once the sale is reflected | The unpaid amount owed to the buyer, if reported | Match the sale notice to the seller’s balance and transfer status. |
| A collector was hired; the creditor still owns the debt | An unpaid balance may remain | May describe collection of that same obligation | Confirm the agency’s role. Two entries do not establish two separate debts. |
| The debt was paid in full or an agreed settlement completed | $0 once the completed payment or settlement is reflected; a sold account should already show $0 | $0 once the completed payment or settlement is reflected | Compare receipts, settlement conditions, and each entry’s reporting date. Accurate history may remain. |
| Ownership is unclear | The amount alone does not identify the owner | The company name alone does not prove it bought the debt | Check the current creditor named in the validation notice and ask for written clarification. |
Experian explains that a sold charged-off account updates to a zero balance with the original creditor. A charge-off by itself is different: it does not show that a sale occurred or that the debt was forgiven.
Example: one debt reported under two tradelines
Suppose a credit card issuer charges off a $2,400 balance and later sells the account to a debt buyer. The credit report may show two tradelines connected to the same underlying debt:
| Reported account | Account status | Current balance | What the entry represents |
|---|---|---|---|
| Original credit card issuer | Charged off and sold | $0 | The payment history and final status of the original credit account |
| Debt buyer or collection agency | Open collection | $2,400 | The balance currently owned or collected by the new creditor |
In this example, the two entries do not normally mean that the consumer owes $4,800. Both tradelines relate to the same $2,400 obligation. The original creditor reports the history of the account, while the debt buyer or collection agency reports the balance that remains subject to collection.
The situation needs closer review when both companies report a current balance, claim ownership, or request separate payments. Before paying either company, determine whether the original creditor retained the debt, assigned it for collection, or sold it to another owner.
For a detailed explanation of how the two account types differ, review the difference between a charge-off and a collection account.
First determine whether the debt was sold or assigned
When the original creditor and collection agency both report a balance, first determine who currently owns the debt. The original creditor may have kept the account, assigned collection work to another company, or sold the debt to a buyer. Those arrangements can produce different reporting and payment instructions.
The original creditor retained the debt
If the original creditor still owns the account, it may continue reporting the unpaid balance and collect directly through its own staff. In this situation, the creditor remains the company to which the debt is owed.
The debt was assigned for collection
An outside collection agency may collect on behalf of the original creditor without owning the account. The creditor may continue reporting the balance, while the agency handles collection communications or accepts an authorized payment. The appearance of a collection company does not, by itself, prove that the debt was sold.
The debt was sold to a debt buyer
After a sale, the debt buyer becomes the current creditor and may collect directly or hire another collection agency. The original creditor’s tradeline may remain as account history, but it commonly shows a zero current balance because the unpaid amount is now owed to the buyer.
Example: a collector was hired, but the debt was not sold
Suppose the card issuer confirms that it still owns the same $2,400 debt and a collection agency is acting for it. The creditor’s unpaid balance is not automatically an error simply because the collector also appears. If both entries show $2,400, investigate whether they accurately describe one obligation; do not assume you owe $4,800 or that the creditor must show $0 without a sale or payment.
The CFPB distinguishes hiring a collector from selling a debt. Ask: Who is the current creditor, and are you collecting for that company or as the debt’s owner? Use the answer alongside the notice and account records.

Review the account status, balance labels, creditor names, and transfer remarks together rather than relying on one field. The guide to reading your credit report explains where to find those details before you contact either company.
Once you identify who currently owns the debt, compare the two tradelines field by field to determine whether the balances, account statuses, dates, and ownership details are consistent.
Compare the two tradelines field by field
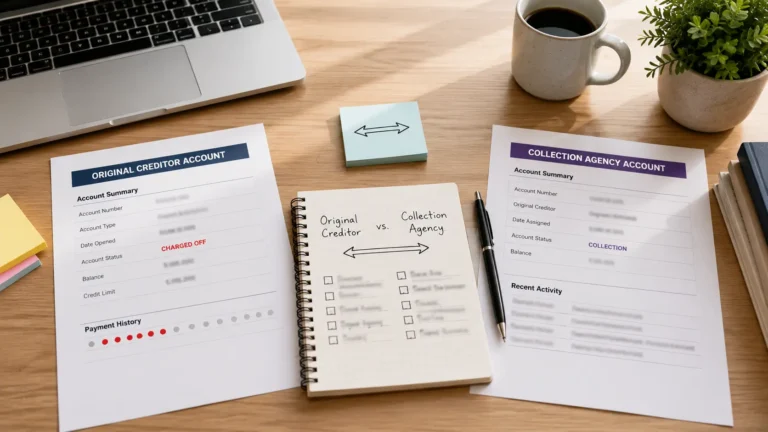
Compare the original creditor account and collection account using several identifying fields, not just the balances. A matching amount may suggest that both entries relate to the same debt, but the creditor name, account status, dates, remarks, and payment instructions provide the context needed to evaluate the reporting.
| Field to compare | What should be consistent | What may legitimately differ | What needs closer review |
|---|---|---|---|
| Original creditor name | The collection entry or collection notice should identify the creditor connected to the original account | The debt buyer or collection agency may appear under a different company name | The collector identifies an unrelated creditor or cannot connect the account to the original debt |
| Account number | Available digits or other identifiers should help connect the two entries | A collector may assign its own account or reference number | The numbers, creditor name, balance, and account type do not establish a reasonable match |
| Current balance—not high balance or original amount | The reported amount should be consistent with statements, payments, credits, and any itemized collection balance | Reporting dates, permitted interest, authorized fees, payments, or credits may produce different amounts | Both companies demand separate payment of the full balance or a reported amount cannot be supported |
| Account status | The statuses should reflect different stages of the same account, such as a charged-off original account and an open collection | The original account and collection account do not need to use identical status labels | The original creditor reports an active amount owed to it after records show that the debt was sold |
| Ownership and transfer remarks | Remarks such as sold, transferred, assigned, or purchased should be consistent with the current creditor’s identity | Not every credit report uses the same wording or displays the same remarks | The remarks conflict with the company claiming ownership or requesting payment |
| Dates | The timeline should connect the original delinquency, charge-off, transfer, and collection activity | The collection account’s date opened may reflect when the collector received or created its account | A newer collection date is presented as a new delinquency or is used to obscure the original delinquency timeline |
| Payment recipient | The company requesting payment should identify the current creditor and explain its role | An authorized collection agency may accept payment for a creditor that still owns the debt | Two companies request separate full payments or provide conflicting payment instructions |
Do not treat a different collection account number or a newer date opened as proof that the entries describe separate debts. Collection agencies often use their own reference numbers, and the date they received an account is not the same as the date of first delinquency. Transferring or selling the debt does not create a new credit reporting period for the underlying delinquency.
A historical amount is not a second current balance. A report can retain a high balance, original loan amount, or amount charged off even when the current balance is $0. In the $2,400 example, a historical charge-off amount of $2,400 beside a $0 current balance is different from a claim that you still owe the original creditor $2,400.
Example: the balances differ because a payment is missing
Suppose a collector received and credited a $500 payment against the $2,400 debt. Assuming no further interest, fees, or adjustments, the remaining amount is $1,900. Compare the dates before treating a $2,400 entry and a $1,900 entry as contradictory: the larger amount may be a snapshot from before the payment.
If a later update still omits the credited payment, identify the $500 discrepancy and attach the receipt. If the creditor sold the account, its current balance should generally be $0, rather than $1,900. Ownership and payment history answer different parts of the problem.
After comparing the fields, look for specific warning signs that one of the reported balances may be inaccurate, outdated, or attributed to the wrong company.
Red flags that one of the reported balances may be wrong
Match the suspected error to evidence. A second company name or a newer collection opening date is not enough, by itself, to establish inaccurate reporting.
- A sold debt still has a current balance with the seller. Compare the sale notice with the original creditor’s current-balance field, not its historical charge-off amount.
- A payment is missing. Match the receipt and account reference to the reporting date. An entry from before payment may be an older snapshot.
- A completed settlement still shows money owed. Check whether you satisfied every condition of the written agreement; a partial payment is not necessarily a completed settlement.
- The amount has unexplained additions. Ask for itemized interest, fees, payments, and credits. A difference between the two entries is a reason to investigate, not automatic proof of an error.
- The creditor, account, or delinquency timeline does not match. A collector’s internal reference number can differ, but the underlying debt should be identifiable.
- Two companies claim separate full payments for one obligation. Ask who owns the debt and who is acting as an agent before agreeing to payment.
Keep each issue separate. For example, a correct collection balance does not resolve an incorrect current balance reported by the original creditor after a sale.
What documents should you gather before disputing a balance?
Create a separate record for each affected bureau and each company reporting an entry. Save:
- The report date, bureau, furnisher name, and available account-number digits.
- The pages displaying both entries, with the disputed field clearly marked.
- The validation notice and any sale, transfer, or ownership correspondence.
- Statements, itemized balances, payment receipts, and completed settlement records.
- Copies of your submissions, attachments, case numbers, and delivery confirmations.
| Example discrepancy | Useful evidence | Specific correction to request |
|---|---|---|
| Seller still reports $2,400 currently owed after a sale | Sale notice identifying the buyer and the affected report page | Investigate and correct the seller’s current balance and transfer status |
| Collector omits a $500 credited payment | Receipt and account statement identifying that payment | Apply the missing credit to the reported balance |
| Completed settlement still shows the original balance | Settlement agreement and proof its payment conditions were met | Update the balance and settlement status |
Send copies and keep the originals. A bank withdrawal alone may not show which collection account received the money, so include the account reference or receipt when available.
What to do if one of the reported balances is wrong
The CFPB recommends disputing credit report errors with the bureau and the company that supplied the information. For this problem, identify which of the two entries contains the incorrect field.
- Identify the exact field. State the reported balance, the balance you believe is correct, and why. Do not describe both accounts as duplicates when your evidence only shows a sold account with an incorrect current balance.
- Check all affected reports. Review Equifax, Experian, and TransUnion separately. Submit to each bureau displaying the error; do not assume one bureau’s result fixes every report.
- Explain the evidence. Connect the sale notice, payment receipt, or settlement agreement to the account and requested correction. Attach the relevant report page.
- Contact the responsible furnisher. Use its designated credit-reporting dispute address when provided. If both entries have different errors, describe each error separately to the company responsible.
- Save submission records and review the result. Keep a receipt date and case number for each dispute. Compare the corrected field with the evidence, even if the response says the account was verified.
A request to clarify debt ownership does not prevent you from disputing a documented reporting error now. You do not have to buy credit repair services to exercise your dispute rights.
Sample wording when a sold debt still shows a creditor balance
Adapt this example only if your records actually show a sale. It is an example of a factual explanation, not a guaranteed deletion letter.
I dispute the current balance reported by [original creditor] for account ending [digits] on my [bureau] report dated [date]. It shows a current balance of [$amount]. The attached [sale notice/creditor letter] dated [date] states that the account was sold to [buyer]. Please investigate and correct the original creditor’s current balance to $0 and its transfer status as appropriate. I am disputing the current balance after the sale, not requesting removal of accurate payment history merely because a collection account also appears. Enclosed are copies of the relevant report page and supporting records. Please send the investigation results in writing.
Use the bureau’s required identifying information and submission instructions. If you have no proof of a sale, explain the actual discrepancy and request an investigation rather than asserting that a sale occurred.
Debt validation and credit reporting disputes have different deadlines
A bureau dispute challenges an entry on your report. A written debt dispute sent to the collector within the validation period can trigger a pause in collection of the disputed amount until the collector provides verification. These are separate processes; a bureau dispute alone is not the same request.
Check the deadline on the notice. The CFPB describes a 30-day period for disputing the debt in writing. Missing that period does not automatically establish that the debt is yours or erase your ability to dispute credit reporting errors.
What if the disputed balance is verified?
Compare the result with the particular field you challenged. A response about the collector’s balance may not resolve your separate objection to the original creditor’s current balance after a sale. Match the case number, furnisher, account identifier, disputed field, and new report before deciding whether the response answers your question.
If the basis remains unclear, you may request a description of the reinvestigation procedure, including the furnisher contacted. An unresolved dispute can also be accompanied by a brief consumer statement; that statement is not itself a balance correction. These options are addressed in FCRA section 1681i(a)(6)–(7) and (b). Provide new relevant evidence when available instead of resending the same unsupported allegation.
For a complaint about inaccurate or incomplete reporting, the CFPB portal requires a prior dispute with the credit reporting agency and asks whether it is no longer pending or was submitted more than 45 days ago. Check those conditions before filing. This is not an extra waiting period for your original dispute or for seeking legal help. Obtain qualified advice for conflicting ownership claims or a legal deadline; do not let a reporting investigation replace a required response to court papers.
Who should you pay when both companies report a balance?
Pay only the current creditor or a collector authorized to receive payment for it, after verifying the account and payment instructions. If the creditor still owns the debt, ask whether it accepts payment directly or requires payment through its collector. If it sold the debt, identify the buyer and any authorized collection agency.
Get the account reference, agreed amount, deadline, payment recipient, and terms of any settlement in writing. Confirm how payment will be credited and which companies will update their entries. The number of tradelines does not determine how many debts you owe.
Our guide to paying the collection agency or original creditor covers the payment decision in detail. For an old debt or conflicting ownership claims, obtain individualized advice before agreeing to new payment terms.
Can paying one company update both credit report entries?
It can lead to updates, but the entries are maintained separately. If the original creditor still owns the debt, its collector may need to communicate the payment before the creditor updates its reporting. If the debt was sold, the original creditor’s current balance should already reflect the sale; paying the buyer does not remove the seller’s payment history.
After payment in full or satisfaction of an agreed settlement, check the reported balance and paid or settled status. Keep the agreement and final receipt. For a collector that still reports money owed, follow the guide to a paid collection still showing a balance.
Balance correction, account deletion, and a score change are three different outcomes. Payment does not automatically entitle you to all three.
How long should you wait for both balances to update?
Track the two entries separately. Record the payment date, the balance and status each company says it furnished, and each account’s reporting date. An entry dated before payment may be an earlier snapshot; one corrected entry does not prove the other is correct.
A normal reporting cycle is not a required delay before a factual dispute. When a field conflicts with your records, explain the discrepancy to each affected bureau and its furnisher using the CFPB’s instructions. A call asking when the company reports can help, but you do not need its permission or a new letter before disputing.
Keep a separate receipt date and case number for each dispute. Bureau investigations generally run for 30 days from receipt, up to 45 in specified circumstances; notice follows within five business days after completion. Those investigation periods are not ordinary payment-reporting deadlines and do not guarantee a correction or deletion.
Does the same debt count twice against your credit score?
Two entries do not mean a fixed double penalty. Your original account’s missed payments or charge-off and a collection can appear in the credit history, but the score impact depends on the scoring model and the rest of your report. Correcting a balance is worthwhile even when no particular score increase can be predicted.
FICO’s collection guidance makes an important distinction: third-party collection balances do not enter FICO credit-utilization calculations, while first-party collection balances may. Do not add a collector’s balance to your credit-card balances and assume that gives your FICO utilization.
FICO Score 9 and the FICO Score 10 suite also disregard paid third-party collections, including settled collections reported with a zero balance. That does not mean those models erase the original creditor’s late-payment or charge-off history, and lenders may use different versions.
Frequently asked questions
Is it illegal for the original creditor and collector to both report?
Not simply because both appear. The entries may describe the original account and later collection activity. The dispute should identify inaccurate information, such as a current balance that conflicts with a documented sale, rather than assume two entries are automatically unlawful.
Why does the original creditor show $0 while the collector shows a balance?
A sale may explain that combination: you no longer owe the seller, but the buyer still claims the debt. A zero balance on the original account does not by itself mean that you paid the debt or that it was forgiven.
Can both accounts remain after I pay?
Yes, accurate negative history can remain for the applicable reporting period. Verify that the reported balances and payment statuses reflect what happened. An updated balance does not guarantee deletion or a particular score increase.
Does a collector’s new opening date restart the reporting period?
No. A collector may use the date it received or opened its collection record. That does not restart the reporting period tied to the underlying delinquency. Check the original delinquency timeline and estimated removal date rather than treating every later opening date as re-aging.
What if both companies want full payment?
Ask each company to identify the current creditor and its authority to collect. Compare the answers with the notice and account records. Do not assume the same underlying obligation requires two full payments; get help if conflicting demands remain unresolved.
Explore related guides on collections.
Sources and review
Updated October 5, 2026. The worked examples and dispute wording above are illustrative; they do not describe a real reader’s account or guarantee an outcome.
- Experian: Balances and ownership after a charged-off account is sold
- CFPB: Original creditors and debt collectors
- CFPB: Debt validation information
- CFPB: Disputing credit report errors
- CFPB: Investigation time limits
- FICO: Collections, utilization, and scoring versions
- 15 U.S.C. § 1681i: Disputed accuracy and investigation results
Disclaimer: This article provides general educational information, not individualized legal, financial, or credit repair advice. Account facts, state law, and the scoring model can affect your options and outcomes.