In this guide
- When does a rapid rescore make sense?
- How long does a rapid rescore take?
- How much does a rapid rescore cost, and who pays?
- What documents do you need for a rapid rescore?
- A worked example: the balance changes, but the score is unknown
- Rapid rescore vs. a credit report dispute
- Why did my rapid rescore not increase my score?
- Questions to ask your lender before agreeing
- Frequently asked questions
- Sources and editorial notes
A rapid rescore is an expedited credit-report update arranged by a lender, usually during a mortgage application. It lets the lender request an update supported by documents, such as a lower credit card balance, and then obtain a score based on the updated information. You cannot order the service yourself from a credit bureau, and a higher score is not guaranteed. Experian explains the lender-requested process.
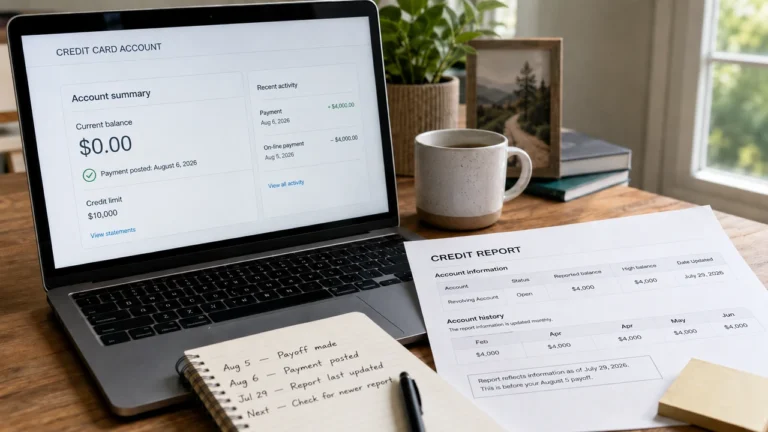
If you have already paid down a card but your lender’s report still shows the old balance, start with this question: “Would updating this account change anything about my application, and what proof do you need?”
At a glance
- Who arranges it: your lender; availability varies.
- Typical timing: several days after a complete request is submitted. Capital One cites three to five business days.
- What you provide: evidence of the specific account change, in the format the lender accepts.
- What you should not expect: a promised point increase, automatic removal of accurate negative information, or guaranteed mortgage approval.
When does a rapid rescore make sense?
Consider discussing it when a time-sensitive mortgage decision depends on information that has changed since the lender’s credit report was obtained. The practical issue is whether a documented update could matter to that particular loan.
Chase notes that not every lender offers rapid rescoring and that credit is only one part of a mortgage decision. Ask about availability before planning around it.
| Your situation | What to ask | What to establish first |
|---|---|---|
| A cleared payment has reduced a card balance. | Would updating this balance matter to my application? | The new balance and acceptable proof. |
| A creditor has confirmed a reporting correction. | Can your provider process this documented correction? | Exactly what the creditor agreed to change. |
| You believe a late payment is wrong, but no correction is confirmed. | Which dispute or verification step is still needed? | Whether there is an error and evidence supporting it. |
| Your app score differs from the lender’s score. | Are we comparing the same bureau, model and date? | Whether any account information is actually outdated. |
| You are monitoring credit without an urgent application. | When will ordinary reporting reflect my payment? | The creditor’s reporting schedule. |
If your main concern is an unexplained delay, our guide to why a credit report is not updating covers the checks to make before pursuing an expedited update.
How long does a rapid rescore take?
Capital One cites a typical processing time of three to five business days. Your lender should confirm its provider’s current estimate. Treat that as processing time, not a promise measured from the moment you click “pay” on a credit card.
Use this sequence to identify where your request stands:
- The payment or correction is completed. Confirm the account shows the change, not merely a pending transaction.
- Acceptable proof becomes available. Ask whether you need a current statement, creditor letter or another document.
- The lender confirms the packet is complete. Record that confirmation date.
- The request is submitted and processed. Ask for the submission date and expected completion window.
- The lender reviews the result. Ask whether the report has updated and whether the loan decision or terms have changed.
For example, suppose you make a payment on Thursday, receive the requested creditor document on Monday, and your lender submits the complete request on Tuesday. A processing estimate beginning Tuesday does not mean the request has been running since Thursday. This is an illustrative sequence, not a promised turnaround.
If a rate lock or purchase deadline is close, give your loan officer the exact date. Ask what the backup plan is if the update arrives later. Leave room for the lender’s review after the credit information changes.
Without a time-sensitive mortgage decision, start with when credit scores update after a credit card payment.
How much does a rapid rescore cost, and who pays?
There is no single fee that applies to every request. ISC Credit, a mortgage credit-reporting provider, describes fees based on the bureau and account item being updated. Its pricing structure is an example of provider billing, not a consumer price list.
Experian says lenders cannot directly pass their rapid-rescore fees to borrowers, while noting that costs may be reflected indirectly in overall loan pricing. Do not assume an unexplained “credit fee” is necessarily the same service. Ask for an itemized explanation before agreeing to a charge.
- What service does this charge cover: a report, an update, a simulation or something else?
- Who pays the provider’s rapid-rescore fee?
- Will any quoted loan costs change if we proceed?
Compare the complete loan offer. The CFPB’s Loan Estimate explainer shows how to review origination charges, other services, interest and estimated cash to close. A “free rescore” does not tell you whether the overall mortgage is competitive.
What documents do you need for a rapid rescore?
Get the lender’s checklist first. CIC Credit’s documentation guidance, for example, calls for creditor-issued evidence identifying the account and requested change, with dates and creditor contact details. Its rules also illustrate why a bank transfer receipt alone may not be enough. Requirements can vary by provider and request.
Before submitting your packet, check:
- Identity and account: does the document identify the correct borrower and account?
- Changed information: does it state the new balance, status or correction clearly?
- Timing: is the document current enough for the lender’s provider?
- Source: was it issued by the creditor or another source the provider accepts?
- Verification: are the requested contact details included?
- Delivery: are you using the lender’s approved secure channel?
Do not edit a creditor document to make it appear to say something different. If a detail is missing, ask the issuer for a corrected or more specific document. Ask your lender before redacting account information it needs for matching.
A script for requesting the right creditor document
“My mortgage lender needs current documentation for account ending [last four digits]. Your system now shows [balance or correction]. Can you issue a dated document confirming that information and include the account details and contact information my lender requires? Please tell me when it will be available.”
This is a request script, not a substitute for the creditor’s document. Keep a copy of what you receive and note when the lender confirms it has everything needed.
A worked example: the balance changes, but the score is unknown
Imagine a borrower with two credit cards. Card A has a $3,000 limit and a reported $1,800 balance. Card B has a $6,000 limit and a $1,200 balance. The borrower pays $1,200 toward Card A, bringing that account’s balance to $600.
| Measure | Before | After |
|---|---|---|
| Card A balance | $1,800 | $600 |
| Card A utilization | $1,800 ÷ $3,000 = 60% | $600 ÷ $3,000 = 20% |
| Card B balance | $1,200 | $1,200 |
| Combined balances | $3,000 | $1,800 |
| Combined utilization | $3,000 ÷ $9,000 ≈ 33.3% | $1,800 ÷ $9,000 = 20% |
| Credit score change | Cannot be calculated from these figures alone. | |
The example assumes both limits and Card B’s balance stay unchanged, with no additional charges or interest. It demonstrates the credit utilization calculation, not a recommended target or a scoring threshold.
A useful request identifies the missing fact: the lender’s report still shows $1,800, while the creditor’s acceptable document shows $600. The lender can evaluate whether expediting that update serves the application. “Please add 20 points” does not identify a change that can be verified.
Check your available cash before making the payment
Now suppose the same borrower has $8,000 in available cash and needs an estimated $7,500 for closing. Paying $1,200 would leave $6,800—$700 short of that estimate, before considering other needs. Lower utilization would not solve that cash shortfall.
This is why the payment should be discussed before it is made. Ask the lender to review cash to close and any reserve requirements alongside the proposed credit update. Our debt-to-income versus utilization guide explains another distinction: a balance ratio and required monthly debt payments measure different things.
Rapid rescore vs. a credit report dispute
A rapid rescore focuses on expediting a supported account update for the lender’s purposes. A credit report dispute challenges information you believe is inaccurate or incomplete. Do not treat an unresolved allegation as an already-confirmed correction.
The CFPB says credit reporting companies generally have 30 days to investigate a dispute, with up to 45 days in certain circumstances. That investigation timeline is different from an expedited update estimate.
If a creditor has already acknowledged an error, show the lender its response and ask what can be processed. If the creditor has not established a correction, ask which evidence or investigation step is missing. Keep the dispute records and the mortgage update request separate so you can track both.
Capital One also explains that rapid rescoring does not simply erase accurate negative history. Paying an account and removing its historical late payments are different outcomes; make sure the requested change says precisely which fact is being updated.
Why did my rapid rescore not increase my score?
Start by separating two results: did the requested account information update, and did the lender’s score or decision change? A completed data update does not establish that a higher score must follow.
Use this troubleshooting checklist with your loan officer:
- Compare the actual account field. Is the requested balance or status now correct?
- Check the bureau. Which report was updated, and which report are you viewing?
- Check the scoring model. Is your app displaying the same model the lender uses?
- Check the dates. Does the score you are viewing use information from after the update?
- Review other changes. Ask the lender to explain any other differences between the earlier and later reports.
- Ask what this means for the loan. Can the application proceed, and have any terms changed?
FICO explains that multiple score versions exist and lenders may use different versions. Comparing an older app score with a newer lender score cannot isolate the effect of one payment. See our explanation of why scores differ across apps and bureaus.
If the data is still wrong, ask what document or verification remains outstanding. If it is correct but the outcome disappoints, request the lender’s explanation before making another large payment or ordering another update.
Questions to ask your lender before agreeing
You can copy this checklist into your notes:
- Which exact account, field and bureau need updating?
- Is the objective eligibility, pricing or satisfying a condition?
- What document will your provider accept?
- Would the proposed payment leave enough for closing and reserves?
- When will you submit the complete request, and when should I follow up?
- Will obtaining a refreshed credit report involve another hard inquiry?
- Who pays, and will any loan charges change?
- What happens if the update is late or the score does not improve?
Ask for the answers in writing. Record the named contact, submission date and next follow-up date in one place rather than relying on several disconnected phone calls.
Frequently asked questions
Can I request a rapid rescore myself?
No. Ask your lender whether it offers the service. Reviewing your own report or submitting a dispute directly is a different process.
Does a rapid rescore update all three credit bureaus?
Do not assume every request covers all three. ISC describes bureau-specific updates and pricing. Ask which bureaus and accounts are included, then check those particular results.
Can a rapid rescore hurt my credit?
It is not a promise that your score will rise. An updated file can produce a different result than expected. Also ask whether the lender will obtain a new report through a hard inquiry; do not assume every step in the mortgage process has the same scoring effect.
What if my lender does not offer rapid rescoring?
Ask whether normal reporting will update the file in time and how the lender can evaluate the documented change. Do not switch lenders solely for this feature without comparing costs, terms and the effect on your closing timeline.
Explore related guides on credit scores.
To understand the entries and statuses behind your score, use our credit report reading checklist before deciding what to do next.
Sources and editorial notes
Source pages checked October 5, 2026. Timing estimates and document requirements can change; your lender must confirm the process for your file. Provider materials below illustrate operational requirements and are not endorsements.
- Experian: What is a rapid rescore?
- Capital One: Rapid rescore—what to know
- Chase: Rapid rescoring and lender availability
- CIC Credit: Documentation requirements
- ISC Credit: Process, fees and bureau coverage
- CFPB: Credit report dispute investigation timelines
- CFPB: Reviewing a Loan Estimate
- FICO: Credit score versions
Claire Bennett is the site’s editorial name. Illustrative calculations are not customer results or predictions.
Educational information only, not individualized financial or legal advice. Mortgage eligibility and terms depend on the lender, loan program and your circumstances.
Photo: laura adai / Unsplash. Illustrative photograph; not a customer story or testimonial.