In this guide
- Why did a collection disappear from my credit report?
- Collection comeback checker: figure out what happened
- Why a collection may disappear before it comes back
- Did the same collection return or did a new collector report the debt?
- Can a collection be reinserted after a dispute?
- Does a collection coming back restart the seven-year reporting period?
- What if a paid collection comes back?
- What if two collectors are reporting the same debt?
- Should you dispute a collection that came back?
- How can a returned collection affect your credit score?
- How to monitor a collection that came back
- Frequently asked questions
- What to do when a collection disappears and comes back: final checklist
- What if a debt disappeared from your credit report?
- Related guides
- Sources
Why did a collection disappear from my credit report?
A collection can disappear from your credit report because it was removed after a dispute, reporting temporarily stopped, the account was transferred, or a bureau no longer had the tradeline in its current file. If it later comes back, it may have been reinserted, reporting may have resumed, or another collector may be reporting the same underlying debt. A collection disappearing does not necessarily mean the debt was deleted permanently, and its return does not automatically mean the reporting is inaccurate.
Your first step is to determine whether the same collection tradeline returned or a different collector began reporting the same underlying debt. Compare the collector name, partial account number, original creditor, balance, account status, date opened, date of first delinquency, and estimated removal date on the old and new reports. If you are not sure where to find these details, use this guide to read and compare your credit reports.
| What you see | What may have happened | What to check next |
|---|---|---|
| The same collector and matching account details returned | The same tradeline may have been reinserted or reporting may have resumed | Previous dispute results, any reinsertion notice, balance, status, and reporting dates |
| A different collection agency appeared | The debt may have been sold, assigned, or transferred | Original creditor, current collector, balance, delinquency history, and whether the previous collector still reports the debt |
| The collection returned on only one credit report | The credit bureaus may have received updates at different times | Compare your Experian, Equifax, and TransUnion reports separately |
| The collection came back with a newer date opened | A new collector may be reporting the date it received the account | Check the date of first delinquency and estimated removal date instead of relying on the date opened alone |
| A paid or settled collection returned with a balance | The payment or settlement may not have been reported correctly | Compare the reported balance and status with your payment or settlement records |
| Two collectors now report the same debt | The debt may have been transferred, or the reporting may need closer review | Check which company currently owns or handles the debt and whether both tradelines show an active balance |
Do not file another dispute just because the collection came back. First identify a specific problem you can verify, such as an incorrect balance, wrong payment status, duplicate reporting, inaccurate date of first delinquency, or an account that does not belong to you.
Next step: Use the collection comeback checker below to determine which situation matches your reports and what to do next.
More collection guidance: Browse the Collections hub for payment, reporting, removal, and dispute guides.
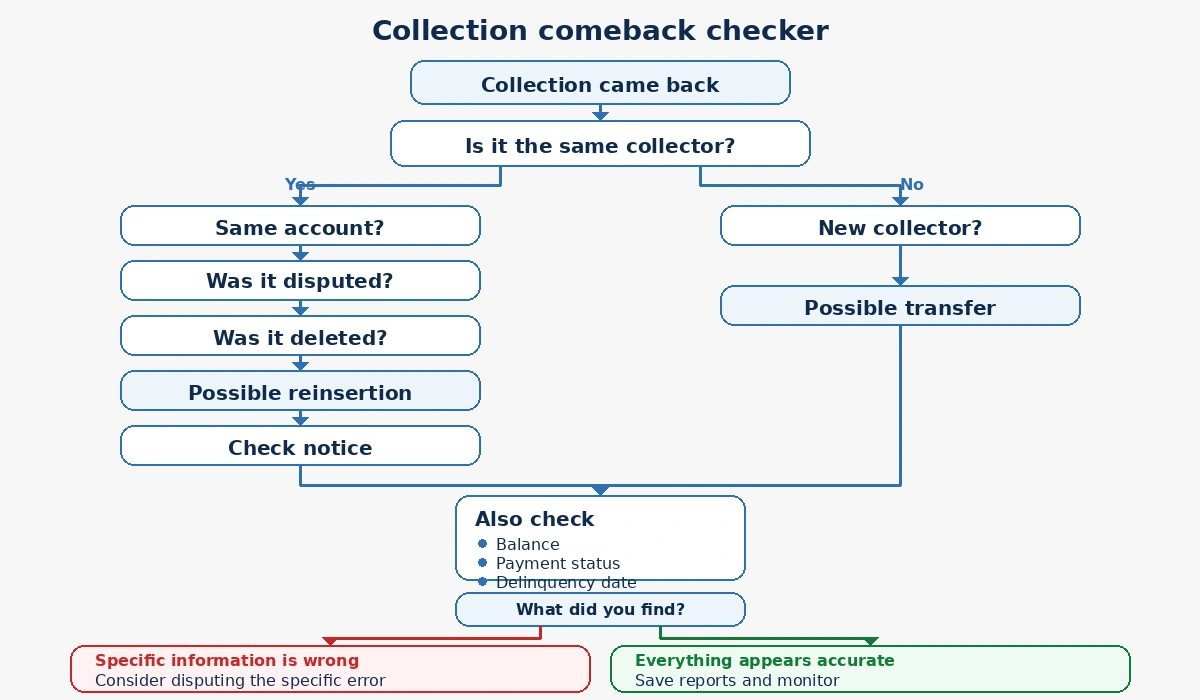
Collection comeback checker: figure out what happened
Use the questions below to identify why the collection returned and whether there is actually something you need to correct. Compare the credit report where the collection was missing with the report where it reappeared.
1. Is the same collection agency reporting the account?
Yes: Compare the partial account number, original creditor, balance, account status, and reporting dates. If those details also match, the same tradeline may have returned.
No: The debt may have been sold, assigned, or transferred to another collection agency. A new collector may use a different company name, internal account number, and date opened even when the underlying debt is the same.
2. Did you dispute the collection before it disappeared?
Yes: Find your original dispute confirmation and investigation results. If the same deleted tradeline returned, also check whether you received a reinsertion notice from the credit bureau.
No: Check whether the collector changed, whether reporting temporarily stopped, or whether the collection disappeared from only one credit bureau before returning.
3. Did the balance or payment status change?
Compare the returned tradeline with your payment and settlement records. Look more closely if:
- a paid collection now shows an outstanding balance;
- a settled account is reported as unpaid;
- the reported balance does not match your records; or
- a transferred collection is still reported as active by the previous collector.
4. Did an important reporting date change?
Compare the date opened, date updated, date of first delinquency, and estimated removal date, if shown.
A newer date opened does not by itself mean the debt was re-aged. A new collector may report the date it received the account. The more important question is whether the original date of first delinquency and the resulting reporting timeline remain accurate.
If the problem appears to involve the collector’s date opened, see what to do when a collection account has the wrong date opened.
5. Is another collector reporting the same debt?
If two collection tradelines appear to involve the same original debt, compare the original creditor, balances, partial account numbers, ownership information, and account status on both entries.
Two related tradelines are not automatically inaccurate, especially during a transfer. But if the reporting makes one underlying debt appear to be two separate active obligations, review the steps for a collection that appears twice on your credit report.
6. Is the returned information actually inaccurate?
| What you found | What it may mean | What to do next |
|---|---|---|
| Same collector, same account details, and no inaccurate information | The tradeline may have resumed reporting or been reinserted | Save the reports and continue monitoring the account |
| Same collection returned after a dispute | Possible reinsertion | Review the dispute results and any reinsertion notice |
| A different collector now reports the debt | Possible sale, assignment, or transfer | Compare the original creditor, balance, and delinquency history |
| A paid or settled collection shows an outstanding balance | Possible balance or payment-status error | Compare the report with your payment or settlement records |
| The date of first delinquency or estimated removal date changed | Possible reporting-date error | Compare the returned tradeline with older reports and account records |
| Two collectors report the same debt as active | Possible duplicate or misleading reporting | Determine which company currently owns or handles the debt and compare both balances |
| The account does not belong to you | Possible identity or account-matching error | Dispute ownership of the specific account |
| No inaccurate information is apparent | The fact that the collection returned may not itself be an error | Keep copies of the reports and monitor future updates |
If you identify an actual error, dispute the specific information that is wrong rather than simply stating that the collection disappeared and came back. Identify the incorrect balance, payment status, ownership detail, duplicate tradeline, or reporting date and support your request with records.
Why a collection may disappear before it comes back
A collection can disappear from your credit report without being permanently removed. This may happen after a dispute, during a temporary reporting interruption, when the debt is transferred to another collector, or when one credit bureau updates its file before the others.
If it disappeared after a dispute: the credit bureau may have deleted the information during or after its reinvestigation. If the same tradeline later returns, check whether it was reinserted and whether you received a reinsertion notice when one was required.
If you did not dispute it: the collector may have stopped reporting temporarily, returned the debt to the original creditor, or transferred it to another collection agency. The old tradeline may disappear before the new collector begins reporting the same underlying debt.
If it disappeared from only one credit report: that does not necessarily mean the collection was permanently removed. Experian, Equifax, and TransUnion maintain separate credit files and may receive account updates at different times.
The disappearance itself does not show that the debt was canceled or that the collection can never return. Once it reappears, the key question is whether the same tradeline came back or a different collector began reporting the debt.
Did the same collection return or did a new collector report the debt?
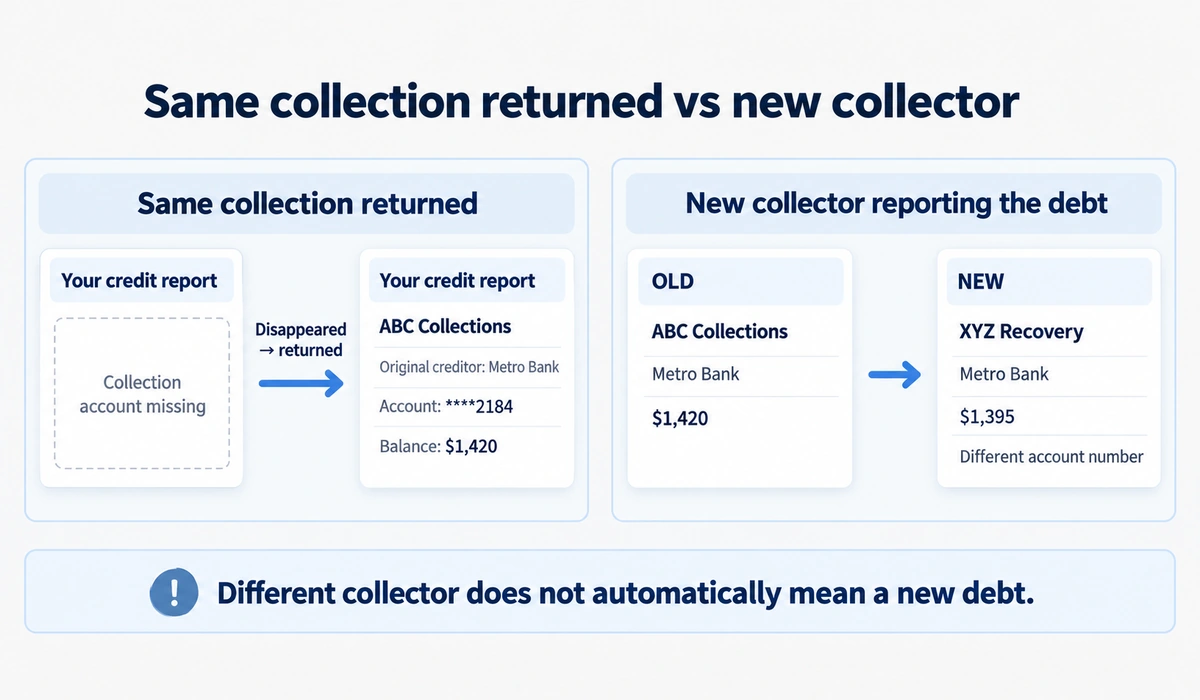
Compare the old and new tradelines before assuming the same collection was added back. If the collector name and key account details match, the same tradeline may have returned. If a different collection agency appears, the debt may have been sold, assigned, or transferred.
| What to compare | Same collection returned | New collector may be reporting |
|---|---|---|
| Collector name | Usually the same | Different company name |
| Partial account number | Often matches | May be different because the new collector can use its own internal account number |
| Original creditor | Usually matches | Should still point to the same underlying debt or original creditor |
| Balance | May be the same or reflect a legitimate update | Should still be consistent with the amount actually owed |
| Date opened | May match the earlier tradeline | May be newer because the new collector received the account later |
| Date of first delinquency | Should remain tied to the original delinquency | Should not become newer simply because the debt changed collectors |
Signs that the same collection returned
The same collector name, matching partial account number, same original creditor, and similar balance and account status are signs that the previously reported tradeline may have returned.
If it disappeared after a dispute, compare the returned account with your dispute results and any reinsertion notice. A changed balance or date updated does not necessarily mean it is a different account because those fields can change when new information is furnished.
Signs that a new collector began reporting the debt
A different collector name, different internal account number, and newer date opened may indicate that another company received or acquired the debt. That does not create a new underlying delinquency simply because a different collection agency is now reporting it.
For example, suppose ABC Collections appeared on your report with Metro Bank listed as the original creditor and later disappeared. Two months later, XYZ Recovery appears with the same original creditor and a similar balance but a different account number. That pattern is more consistent with a transfer or sale than with the exact same tradeline being reinserted.
What if you still cannot tell?
Use the original creditor and delinquency history as your strongest cross-checks. Compare the balance, account status, date of first delinquency, and any payment or settlement records with both tradelines.
If the same collector and account details returned after a dispute, the next step is to determine whether the collection was reinserted under the applicable credit reporting rules.
Can a collection be reinserted after a dispute?
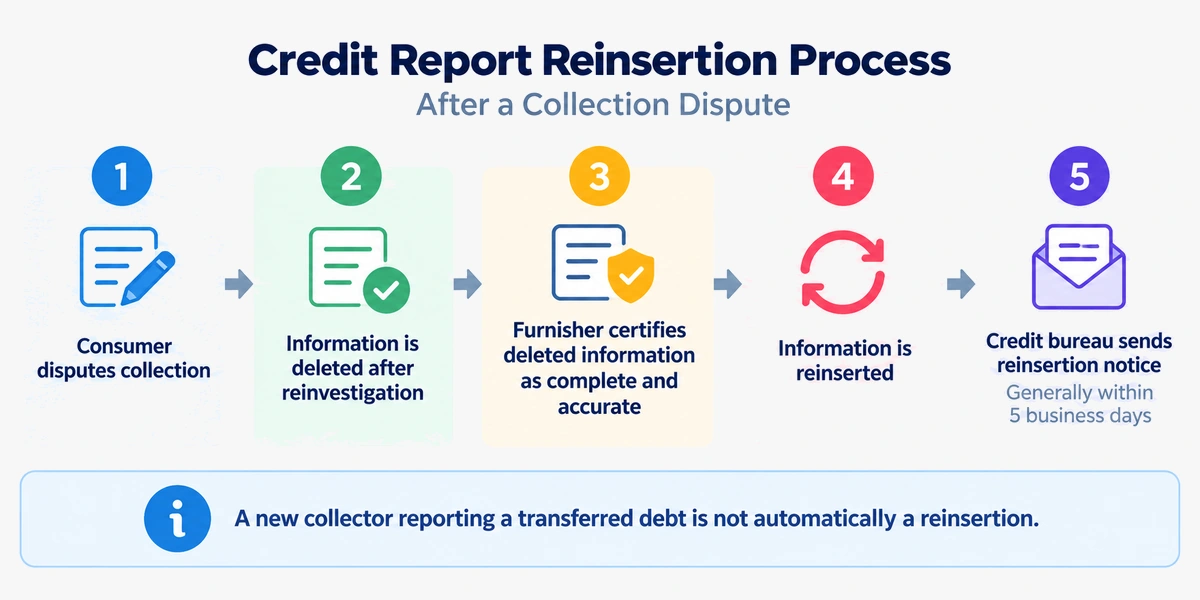
Yes, subject to the applicable rules. First find the bureau’s completed dispute result: did it actually say that the information was deleted? A temporary absence from an app, a new collector name, or an updated field is not enough on its own to establish formal reinsertion.
For information deleted under the FCRA reinvestigation provision, section 1681i(a)(5)(B) requires furnisher certification before reinsertion and notice to the consumer within five business days afterward. Preserve the deletion result, later report and any notice. A notice problem and whether the underlying debt is valid are separate questions.
Documented dispute deletion followed by the same information returning? Use the dedicated reinsertion guide for the notice checklist, evidence timeline and follow-up wording. Without that history, continue this guide’s collector-transfer, balance and date checks rather than assuming every reappearance follows the reinsertion process.
Does a collection coming back restart the seven-year reporting period?
No. If the same continuously delinquent debt disappears and later returns to your credit report, its return does not restart the federal credit reporting period. A new collector, a new account number, a dispute, a payment, a settlement, or reinsertion of previously deleted information does not create a new reporting timeline for the same delinquency.
For an account placed for collection, the Fair Credit Reporting Act ties the reporting period to the delinquency that immediately preceded the collection activity or charge-off. The seven-year period is measured beginning 180 days after that delinquency, not from the date a collector opened, updated, purchased, or re-reported the account.
Which date matters?
Do not judge the age of a returned collection by the newest date on the tradeline. Several dates can appear on a credit report, but they do not all control how long the collection can be reported.
| Reported date | What it generally means | Does it start a new reporting period? |
|---|---|---|
| Date of first delinquency | The delinquency that immediately preceded the collection or charge-off | This is the key delinquency date used to determine the reporting timeline |
| Date opened | When the collector opened or received the account in its system | No |
| Date updated | When the furnisher most recently reported or changed account information | No |
| Date of last payment | When the creditor or collector received the most recent payment | No, not for the federal credit reporting period |
What does not restart the reporting period?
- The debt is sold or assigned to another collector.
- A different collection agency begins reporting the debt.
- The new collector uses a different account number.
- The collector updates the balance, status, or date updated.
- You dispute the collection.
- The collection is deleted and later reinserted.
- You make a payment or settle the debt.
A payment or settlement does not restart the federal credit reporting period for the same delinquency. The statute of limitations for a debt-collection lawsuit is a separate timeline and can depend on state law and the circumstances. For a more detailed explanation, see does paying a collection restart the seven-year period?
What if the collection comes back with a newer date?
A newer date opened or date updated does not by itself mean the collection was re-aged. A new collector may report the date it received the account even though the underlying delinquency began years earlier.
For example, suppose an account became continuously delinquent in March 2021 and was transferred to a new collector in August 2025. The new collector may report an August 2025 date opened, but that does not turn the 2021 delinquency into a new delinquency for federal credit reporting purposes.
Compare the returned tradeline with an older credit report or account statement. Focus on whether the original delinquency information and estimated removal date, if shown, still line up with when the continuous delinquency began.
What if the reporting period should already have expired?
A new collector, new account number, updated tradeline, or reinsertion does not give the same continuously delinquent debt a fresh federal reporting period. If an old collection reappears after you believe its reporting period should have expired, verify the underlying dates before taking action.
Check:
- the delinquency that immediately preceded the collection activity;
- the estimated removal date, if shown on your credit report;
- the original creditor;
- the collector name and partial account number;
- the date opened and date updated; and
- older credit reports or statements showing when the continuous delinquency began.
If the delinquency date or resulting reporting timeline appears inaccurate, save the old and new reports and identify the exact date you believe is wrong. Do not dispute the account only by saying that it is “more than seven years old.” Explain which reported date is inaccurate and provide records that support the earlier delinquency date.
What if a paid collection comes back?
A paid or settled collection can reappear on your credit report, but the balance and payment status should accurately reflect what happened. The fact that the tradeline returned does not automatically mean it is being reported incorrectly.
Start by checking the reported balance, account status, collector name, and the date the account was last updated. Then compare those details with your receipt, settlement agreement, bank record, or paid-in-full confirmation.
If the collection came back with a $0 balance
A returned collection showing a $0 balance may be accurate if the debt was paid or settled. Payment does not automatically require an otherwise accurate collection tradeline to disappear from your credit report.
Check that the account does not show money still owed and that the payment or settlement status matches your records. Also confirm that the original delinquency information and estimated removal date, if shown, have not been changed incorrectly.
If the collection came back with an outstanding balance
If you already paid or settled the debt but the returned tradeline shows a balance greater than $0, compare the report with your proof of payment before disputing anything.
Check:
- the amount you paid;
- the date the payment cleared;
- whether the payment was for the full balance or an agreed settlement;
- which company received the payment;
- the balance currently reported by the collector; and
- whether the account is reported as paid, settled, unpaid, or still in collection.
If the reported balance or payment status does not match your records, see what to do when a paid collection is still showing a balance.
What if a different collector reports a balance after you paid?
First confirm who received your payment and whether the debt was transferred before or after you paid it. A new collector may not be the same company that accepted your payment, so keep the settlement agreement, payment confirmation, and any correspondence showing which account the payment satisfied.
If the new collector reports an amount that conflicts with those records, identify the specific balance or payment-status error rather than disputing the account simply because a different company is now reporting it.
| What you see | What it may mean | What to do next |
|---|---|---|
| Paid collection with a $0 balance | The reporting may be accurate | Check the payment status and reporting dates |
| Settled collection with a $0 balance | The reporting may be accurate | Confirm that the settlement status matches your records |
| Paid collection with an outstanding balance | Possible balance or payment-status error | Compare the tradeline with your payment evidence |
| Different collector reports a balance after payment | The payment may not have been reflected correctly after a transfer | Verify who received the payment and which debt it satisfied |
Do not dispute a paid collection simply because it reappeared. Dispute the specific balance, payment status, ownership detail, or other information that does not match your records.
What if two collectors are reporting the same debt?
Two collection accounts tied to the same debt are not automatically a reporting error. This can happen when a debt is transferred or sold and the previous collector remains on your credit report while a new collector begins reporting it. The key question is whether both tradelines accurately describe the current status of the debt.
Compare both collection tradelines
Check the two entries side by side and compare:
- the original creditor;
- the partial account numbers;
- the balances;
- the account status;
- the collector names;
- the date opened;
- the date of first delinquency; and
- any remarks showing that an account was transferred, sold, closed, or returned to the creditor.
A different collector name or account number does not necessarily mean you have two separate debts. Collection agencies can assign their own internal account numbers when they receive an account.
When two collection accounts may need closer review
Look more closely if both collectors appear to demand the full unpaid balance, if the previous collector still reports the account as active after transferring it, or if the two tradelines make one debt appear to be two separate obligations.
| What you see | What it may mean | What to check next |
|---|---|---|
| Old collector shows $0 or a transferred status and new collector shows the current balance | The reporting may reflect a transfer | Confirm the original creditor and account history match |
| Both collectors show the full balance as currently owed | Possible duplicate or misleading reporting | Verify which company currently owns or handles the debt |
| Different collector names and account numbers but the same original creditor | The debt may have changed collectors | Compare the delinquency history, balance, and transfer dates |
| The two accounts have different original creditors | They may be separate debts | Do not assume they are duplicates until you compare the underlying accounts |
What to do if both collectors show an active balance
Start by confirming which company currently owns or services the debt. Review recent collection letters, account statements, transfer notices, and any correspondence from the original creditor. If needed, contact the companies and ask each one to identify its current role and the balance it claims you owe.
For example, suppose ABC Collections disappeared from your report and XYZ Recovery appeared two months later. If ABC still shows a $1,400 active balance and XYZ also reports $1,400 as currently owed, verify whether ABC transferred the account and whether its tradeline should still show an outstanding balance.
Do not dispute both accounts simply because they relate to the same debt. Identify the specific tradeline, balance, ownership detail, or account status that appears inaccurate and support the correction with your records.
Should you dispute a collection that came back?
Do not dispute a collection simply because it disappeared and later came back. A dispute is appropriate when you can identify specific information that is inaccurate, incomplete, duplicated, outdated, or does not belong to you.
Before filing a dispute, compare the returned tradeline with your older credit reports and account records. Focus on the exact field that appears wrong rather than challenging the entire collection without a specific reason.
When a dispute may be appropriate
Consider disputing the returned collection if you find a specific problem such as:
- the account does not belong to you;
- the reported balance is incorrect;
- a paid or settled collection still shows an amount owed;
- the payment or account status is inaccurate;
- the same debt is being reported in a duplicate or misleading way;
- the delinquency date or other important reporting date is inaccurate;
- the collection appears to be reported beyond the applicable federal reporting period; or
- previously deleted information was reinserted after a dispute and the reinsertion procedure appears not to have been followed correctly.
When you should not dispute it
The collection’s return by itself is not evidence of an error. A dispute generally is not appropriate solely because:
- the collection disappeared and later returned;
- a different collector began reporting the same debt after a transfer;
- the information is negative but appears accurate;
- a paid or settled collection reappeared with a $0 balance and accurate status; or
- you want an accurate collection removed to improve your credit score.
What exactly should you dispute?
| Problem you found | What to dispute | What can help support it |
|---|---|---|
| Wrong balance | The specific balance being reported | Statements, payment confirmations, or settlement records |
| Wrong payment status | The reported paid, settled, or unpaid status | Receipts, bank records, or written confirmation from the collector |
| Wrong delinquency date | The specific date you believe is inaccurate | Older credit reports, creditor statements, or account records |
| Account is not yours | Ownership or account identity | Records showing the account does not belong to you |
| Duplicate or misleading reporting | The specific tradeline, balance, or status creating the duplication | Credit reports showing both entries and any transfer information |
| Collection appears too old to report | The delinquency date or reporting timeline | Older reports and records showing when the delinquency began |
| Same information returned after a dispute | The inaccurate information or the specific reinsertion issue | Dispute results, old and new reports, and any reinsertion notice |
What evidence should you save?
Keep copies of the documents that show what changed and why you believe the returned information is wrong:
- the credit report showing the collection before it disappeared;
- the report showing the collection was removed, if available;
- the current report showing that it returned;
- previous dispute results;
- payment or settlement records;
- account statements and collector correspondence; and
- any reinsertion notice you received.
Dispute the specific error, not simply the fact that the collection came back. For example, instead of writing, “This collection was removed and came back,” identify the problem: “This account shows a $740 balance, but the attached settlement confirmation shows the account was settled and the remaining balance was $0.”
If the returned collection appears accurate after you compare the account details, dates, balance, and status, there may be nothing to dispute. Save the reports and continue monitoring the tradeline for later changes.
How can a returned collection affect your credit score?
A collection that reappears on your credit report can affect your credit score, but there is no fixed number of points your score will gain or lose. The impact depends on the scoring model, the age and status of the collection, and the rest of your credit file.
Can your score drop when the collection comes back?
Yes. If the returned collection is considered by the scoring model and was not present when your previous score was calculated, its return may contribute to a lower score.
That does not mean every score drop after a collection reappears was caused entirely by that account. Credit card balances, new late payments, new accounts, hard inquiries, and other changes can affect your score at the same time.
Why might your score stay the same?
A collection can return without causing an obvious score change. Different credit scoring models treat collection accounts differently, and the age, balance, payment status, and other information in your credit file can affect the result.
| What happened | What it may mean |
|---|---|
| The collection returned and your score dropped | The returned collection may have contributed, but other credit report changes may also be involved |
| The collection returned and your score stayed about the same | The scoring model, age of the collection, or other information in your file may have limited the effect |
| The collection returned while another account also changed | You cannot reliably attribute the entire score change to the collection alone |
| A paid collection returned | Its effect can depend on the scoring model and the rest of your credit profile |
How to check whether the returned collection contributed to the change
Compare the credit report from before the score changed with the report from afterward. Check whether the collection was the only meaningful difference.
Also look for:
- new late payments;
- higher reported credit card balances;
- new accounts or hard inquiries;
- accounts that were added or removed;
- changes in account balances or limits; and
- other negative information that appeared around the same time.
Make sure you are comparing the same type of credit score as well. Consumers can have multiple credit scores, and a lender may use a different scoring model or credit bureau than the score you monitor yourself.
Do not dispute an accurate collection simply because your score changed after it returned. If the returned tradeline contains an incorrect balance, status, date, ownership detail, or other error, focus on correcting that specific information instead.
How to monitor a collection that came back
Save the credit report showing the returned collection and compare the same account details each time you review your reports. The goal is to catch a wrong balance, status, date, ownership detail, or duplicate entry rather than simply checking whether the collection is still visible.
What to save now
Keep the records that show what happened before and after the collection returned:
- the current credit report showing the collection;
- an older report showing that the collection was missing, if available;
- previous dispute results, if you disputed the account;
- any reinsertion notice you received;
- payment or settlement records; and
- letters or other correspondence from the collector or original creditor.
Save copies of the actual credit reports when possible. A monitoring alert may tell you that an account changed without showing enough detail to compare the old and new tradelines.
What to check on future reports
Compare the same fields each time:
- collector name;
- original creditor;
- partial account number;
- reported balance;
- payment or collection status;
- date opened and date updated;
- delinquency information and estimated removal date, if shown; and
- whether another collector begins reporting the same debt.
When should you check again?
If the collection is being disputed, corrected, paid, settled, or transferred, check your report again after you receive the dispute result or after the account is updated. Then compare the same fields with the report you saved earlier.
If there is no active dispute or correction in progress, continue checking your reports periodically. You do not need to file a new dispute every time the collection remains visible if the information being reported is accurate.
| What changes | What to check | What to do next |
|---|---|---|
| The balance changes unexpectedly | Compare it with payment records, statements, or a settlement agreement | Identify whether the reported balance is actually inaccurate before disputing it |
| A different collector appears | Compare the original creditor, balance, and account history | Determine whether the debt was sold, assigned, or transferred |
| The same debt appears under two collectors | Check which collector currently owns or handles the account and what balance each tradeline reports | Investigate whether one tradeline is duplicate, outdated, or misleading |
| The delinquency or expected removal timing changes | Compare the dates with older reports and records showing when the delinquency began | Identify the specific date that appears inaccurate |
| The status changes after payment or settlement | Compare the balance and status with your payment or settlement records | Act if the report still shows money owed or another incorrect status |
| Nothing inaccurate changes | Confirm that the balance, status, dates, and ownership information remain consistent | Keep your records and continue monitoring |
The goal is not to keep disputing the collection until it disappears. The goal is to make sure the information that remains on your credit report is accurate, complete, current, and tied to the correct debt.
Frequently asked questions
Can a collection disappear and come back without a dispute?
Yes. A collection can disappear even if you never disputed it. Reporting may stop temporarily, the debt may be transferred to another collector, or one credit bureau may update its file before another. If the account later returns, compare the collector name, original creditor, balance, partial account number, and dates to determine whether the same tradeline returned or a new collector began reporting the debt.
Why did the collection come back on only one credit report?
Experian, Equifax, and TransUnion maintain separate credit files, so the same collection may not appear or update at the same time on all three. A collector also may not furnish information to every bureau. Compare all three reports before assuming the account was permanently removed elsewhere.
Can a collection keep disappearing and reappearing?
Yes. That can happen if reporting stops and later resumes, the debt changes collectors, or previously deleted information is later reinserted. The pattern alone does not prove the account is inaccurate. Compare the balance, status, collector name, ownership details, and reporting dates each time it returns.
Can the same collection appear under a different company name?
Yes. If the debt is sold, assigned, or transferred, a different collection agency may begin reporting it and may use a different account number. Compare the original creditor, balance, and delinquency history to determine whether the new tradeline relates to the same underlying debt.
What if the collection comes back after I thought it was permanently removed?
First determine why it disappeared. If it was deleted after a dispute, check whether the same information was reinserted and whether the reinsertion requirements apply. If a different collector appeared, verify whether the debt was transferred. If you believe the account is too old to report, compare the delinquency information with older credit reports and account records before disputing a specific date or reporting error.
What to do when a collection disappears and comes back: final checklist
Do not start with another dispute. Start by identifying exactly what returned and whether any information is actually wrong.
- Save the current credit report. Keep a copy showing the returned collection before anything changes again.
- Find an older report for comparison. Use a report from when the collection was missing or from before it disappeared.
- Determine whether the same collector returned. Compare the collector name, original creditor, partial account number, balance, status, and reporting dates.
- Check whether the debt changed collectors. If a different agency appears, determine whether the account was sold, assigned, or transferred.
- Review any previous dispute. If the same information was deleted after a reinvestigation and later returned, check your dispute results and any reinsertion notice.
- Verify the balance and payment status. If you paid or settled the debt, compare the tradeline with your payment confirmation, settlement agreement, or bank records.
- Check the delinquency timeline. Do not rely on a newer date opened or date updated. Compare the underlying delinquency information and estimated removal date, if shown.
- Look for duplicate or misleading reporting. If two collectors appear, determine which company currently owns or handles the debt and what balance each tradeline reports.
- Identify the exact error before disputing. Dispute an incorrect balance, status, date, ownership detail, duplicate entry, outdated information, or an account that is not yours—not simply the fact that the collection came back.
- Keep monitoring the account. Save later reports so you can see whether the balance, status, dates, collector, or ownership information changes again.
If everything matches your records and the returned collection is being reported accurately, its reappearance alone may not require any action.
What if a debt disappeared from your credit report?
If a debt or other item disappears from a credit report, do not assume the debt was forgiven or that it can never return. The entry may have aged off, been removed after a dispute, moved to a different collector, stopped being furnished, or temporarily disappeared while information changed. Compare older and current reports, check whether the debt appears under another company name, and keep any payment or dispute records.
If something was removed from your credit report after a dispute and later reappears, use our guide on reinsertion after a dispute. If the debt simply vanished without a dispute, verify ownership and reporting before making assumptions about the legal obligation.
Related guides
- Collections hub — reporting, balances, dates, disputes, and payment questions.
- Disputed item removed, then came back — what reinsertion can mean after a dispute.
- Can the same collection appear twice? — how to distinguish a duplicate from legitimate separate reporting.
Sources
- 15 U.S.C. § 1681i — Procedure in case of disputed accuracy
- 15 U.S.C. § 1681c — Requirements relating to information contained in consumer reports
- Consumer Financial Protection Bureau — How do I dispute an error on my credit report?
- Federal Trade Commission — Disputing errors on your credit reports
- AnnualCreditReport.com — Official site for free credit reports
Editorial note: Credit reporting and debt-collection situations can depend on the facts of the account and applicable law. This article is for general educational purposes and is not legal advice. If you are dealing with a lawsuit, identity theft, or a complex dispute about your legal rights, consider getting advice from a qualified consumer-law attorney.