In this guide
- Check three labels before comparing numbers
- A comparison worksheet you can use
- When should you inspect the reports?
- Which score should you trust?
- What should you do next?
- A message to send when the labels do not explain the gap
- Work through a score gap one variable at a time
- Why an industry-specific score may look unfamiliar
- Build a progress log you can interpret later
- Download the private worksheet
- Sources
Quick answer: Different credit scores can use different credit reports, scoring models, model versions, or calculation dates. A gap between two apps does not automatically mean one is wrong. Write down the model, bureau, and date beside each score before comparing the numbers. If those details match and you still see an unexplained difference, ask the providers to clarify the calculation and review the underlying account information.
Check three labels before comparing numbers
The CFPB explains that you have multiple credit scores, with differences tied to the bureau data, model, loan product, and calculation date. The name of the app is not a complete score description.
| Label to find | What to record | What a mismatch suggests |
|---|---|---|
| Scoring model | Model family and version, if displayed. | The formulas may treat the same report differently. |
| Credit bureau | Equifax, Experian, or TransUnion. | The underlying account information may differ. |
| Calculation date | The date the score was generated, not merely the day you opened the app. | One score may reflect a more recent report update. |
| Score purpose or range | Any industry-specific label and the stated range. | You may be comparing scores built for different uses. |
If a label is absent, check the provider’s explanation or ask its support team. Do not fill the gap by assuming that every free app shows one particular model.
Model version also matters when interpreting credit card balances. Most FICO Score versions calculate utilization from the latest reported information, while FICO Score 10 T and VantageScore 4.0 also use historical trends. Our comparison of credit utilization and scoring-model memory explains the distinction and links to the model developers’ documentation.
A comparison worksheet you can use
Copy the following fields into a private note. Avoid storing full account numbers or your Social Security number in it.
| Field | Score A | Score B |
|---|---|---|
| Provider and displayed score | Write here | Write here |
| Model and version | Write here | Write here |
| Bureau | Write here | Write here |
| Calculation date | Write here | Write here |
| Recent report changes | Write here | Write here |
Illustrative example: Score A was calculated from one bureau’s report before a card payment appeared; Score B came from another bureau after an update. The difference alone cannot tell you how many points that payment caused. Several variables changed together.
When should you inspect the reports?
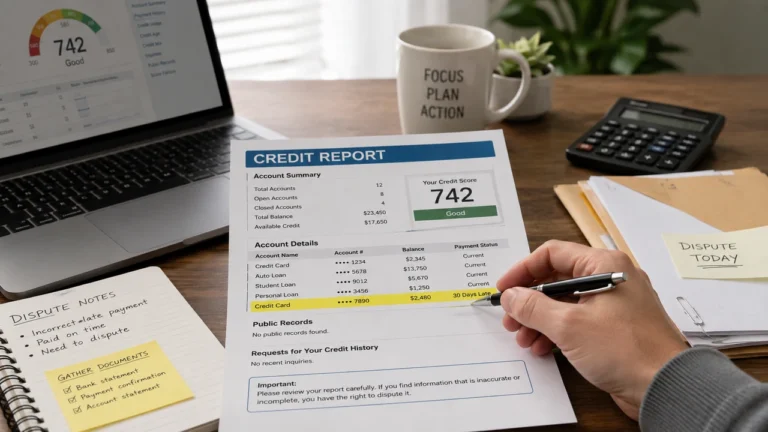
Inspect the reports when you notice an unfamiliar account, conflicting balances for the same reporting period, or information that does not match your records. The FTC recommends reviewing reports from all three bureaus because their information may differ.
Compare the date last reported before treating a balance mismatch as an error. A current lender dashboard and an older credit report are not necessarily describing the same moment.
If the underlying information is inaccurate, document the entry and the evidence for correction. Our credit report dispute guide explains that process. Asking a bureau to make its score equal another app’s score is not the same as identifying a report error.
Which score should you trust?
When a lender turns you down, our adverse action notice checklist helps separate score factors from the lender’s actual reasons for the decision.
Use the score whose model, data source, and date you understand for the question you are trying to answer. For progress tracking, follow a consistent score series. For a loan decision, ask the lender which score or scores it uses; your dashboard number may not be the one used for that application.
Our Credit Karma vs. Experian guide compares two common services, while how often credit scores update explains why display timing can complicate comparisons.
What should you do next?
Complete the worksheet before paying for another score. If the labels explain the gap and the reports look accurate, there may be no reporting error to correct. If the labels match but the result remains unclear, send the providers the model, bureau, date, and a redacted screenshot and ask them to explain the difference. Never send a full credit report through an unverified support channel.
A message to send when the labels do not explain the gap
You can adapt this request for a provider’s verified support channel: “Your service shows [score] calculated on [date]. Please confirm the scoring model and version, credit bureau, and calculation date. I am comparing it with another score and want to check that both use the same information.”
Leave the brackets in your private copy until you are ready to contact the provider. Include only the information needed for that question; do not attach an entire credit report to a general support message. If a provider cannot identify the model or date, mark that comparison as unresolved instead of declaring either score inaccurate. Review the difference between the report and the score before starting a dispute.
Work through a score gap one variable at a time
Illustrative comparison: App A shows 704 and App B shows 731. These made-up numbers illustrate a review process; they are not a normal or expected gap between any two products.
- Compare models. If one uses a different model or version, record that difference before drawing conclusions from the numbers.
- Compare bureaus. If the reports come from different bureaus, check whether the same accounts, balances, and payment statuses appear.
- Compare dates. If one score predates an account update, save both calculation dates and find when that entry changed.
- Identify what remains unknown. A missing version or date means you cannot yet make a complete comparison. Ask the provider rather than inventing the label.
Suppose the providers use different models and different bureaus. Finding one updated balance does not prove it explains all 27 points. Your conclusion should be limited to the evidence: the numbers are based on different inputs, and the account information either matches your records or needs further investigation.
Why an industry-specific score may look unfamiliar
FICO offers multiple score versions, including versions designed for particular lending uses. A score labeled for auto lending or bankcards should not automatically be treated as the same product as a general-purpose score in a consumer dashboard. Read the displayed score range as well as the version.
If a lender shares a score with you, save the accompanying explanation. Ask which bureau and score version it used and whether the number was generated for this application. That creates a useful comparison record without assuming that the app with the highest score is more accurate.
Build a progress log you can interpret later
Pick one consistently identified score for routine tracking. Add a new row when it updates, with the calculation date and a short note about any verified report change. Keep separately labeled scores in separate columns rather than treating them as consecutive readings from one measurement.
If your service changes its model or bureau, mark that point in the log. A difference across that change should not be described as a pure improvement or decline in your credit history. For application planning, return to the lender’s requirements and your reports; a tidy tracking chart cannot establish approval or the interest rate you will receive.
Download the private worksheet
Download the three-page credit review and freeze worksheet pack (PDF). Start with page 1 to compare score labels and record report questions. Print the relevant page and complete it offline. This organizer is not a bureau request form; keep identifying numbers and passwords out of it.
By Claire Bennett, the editorial name used by the site’s founder and editor. Factual guidance checked against the official sources below. Cover photograph: laura adai / Unsplash.
Explore related guides on credit scores.
To understand the entries and statuses behind your score, use our credit report reading checklist before deciding what to do next.
Sources
Sources checked October 3, 2026. This article provides general educational information for U.S. readers, not individualized financial or legal advice.