In this guide
Most people should start with free credit reports and a free security freeze before paying for credit monitoring. A subscription can still be useful if you want automatic alerts, coverage across the bureaus you care about, or help after an identity-theft event. It cannot prevent every form of fraud or repair an inaccurate report for you.
This is a decision guide, not a ranking of companies. Product prices, alert timing, bureau coverage, cancellation terms, and included scores change. Check the provider’s current terms before signing up.
Free vs. paid: what are you buying?
| Option | What it helps you do | What it does not do | Cost to check |
|---|---|---|---|
| Free reports from AnnualCreditReport.com | Read a report from each of Equifax, Experian, and TransUnion, currently available free weekly | Does not continuously alert you or necessarily include a score | $0 for the authorized reports |
| Free security freeze at each bureau | Restrict access to your report for many new-credit applications | Does not stop misuse of existing accounts; you may need to lift it to apply | $0 to place or lift |
| Free bank, issuer, or bureau alerts | May notify you about selected account or report changes | Coverage and timing can be limited; “free” offers may lead to an optional paid tier | Read the exact plan terms |
| Paid credit monitoring | Automates alerts for changes covered by its plan, possibly at several bureaus | Does not block a new account by itself, prove a report is accurate, or guarantee identity protection | Monthly or annual fee, renewal, cancellation, and extras |
The CFPB describes credit monitoring as a service that watches reports and alerts you to changes. It also points to free weekly reports, freezes, and fraud alerts as alternatives. A credit freeze is preventive for many new-account attempts; monitoring is mainly a way to notice certain changes. Neither replaces checking your bank and card statements.
When paying may be worth considering
- You want automatic alerts: You will act on a new-account or inquiry alert sooner than you would notice a change through manual report checks.
- You need coverage at multiple bureaus: Verify exactly which bureaus and types of changes the plan watches. “Three-bureau” marketing can refer to reports, scores, monitoring, or some combination; read the details.
- A data breach includes a free offer: Check the offer and its end date before paying for overlapping coverage. The FTC notes that free monitoring after a breach can be useful.
- You value assistance after an incident: Read the actual identity-restoration and insurance terms, exclusions, limits, and claim process. Do not assume an advertised coverage amount is money paid automatically.
Seven questions before you buy
- Which of Equifax, Experian, and TransUnion are monitored, and how often is each checked?
- Which changes trigger alerts: new accounts, hard inquiries, address changes, balances, collections, or public records? What is excluded?
- Which credit score, model, bureau, and update frequency are included? Will it match a lender’s score? Usually you cannot assume that.
- What is the introductory price, renewal price, billing frequency, and total first-year cost? At $20 monthly, the simple annual cost is $240 before any change or tax.
- How do you cancel, and does a trial convert automatically to a paid subscription?
- What personal data must you provide, and what does the privacy policy say about its use and sharing?
- What does the service actually do if fraud appears, and what action remains yours?
Choose a path based on your actual problem
| Your situation | Useful first step |
|---|---|
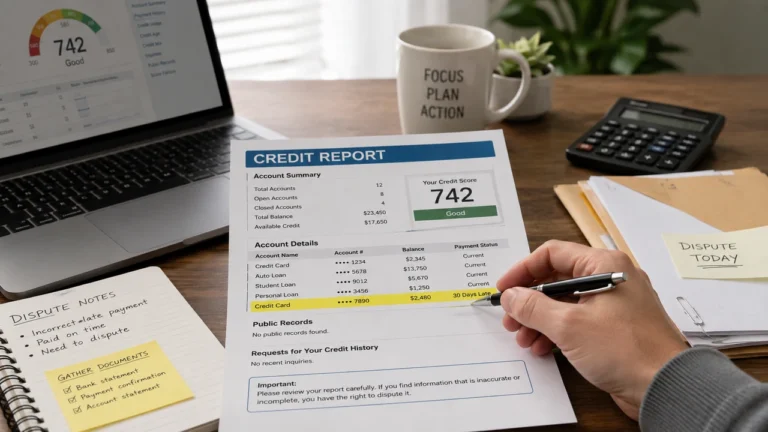
| You only want to check whether an old collection or charge-off updated correctly | Get the free reports and compare the balance, status, dates, and bureau; an ongoing paid subscription may be unnecessary |
| You see a specific incorrect item | Save the relevant report and evidence, then use the appropriate dispute process; a monitoring alert is not a dispute |
| You suspect someone may open credit in your name | Consider a free freeze at each bureau and review reports; if identity theft occurred, use IdentityTheft.gov |
| You want hands-off alerts after a breach | Check any free breach offer first, then compare paid plans by bureau coverage, cost, and response features |
What monitoring cannot fix
Monitoring cannot promise to raise a score, remove accurate negative information, or stop a thief from using an existing card. If your goal is to dispute an error, start with the underlying report and evidence. If you want to understand a score change, use our score-update guide and compare the same score model and bureau over time.
For a narrower coverage decision, compare one-bureau and three-bureau alerts. If a bundle promises broader help, read identity theft protection vs. credit monitoring before paying.
Our comparison standard
We have not hands-on tested or ranked paid monitoring plans for this guide. If we later recommend a specific product and receive compensation, we will put a plain-language notice near the recommendation. Read our Affiliate Disclosure.
Check what you can do without a subscription
Start by requesting your free reports from the official service. Checking your own score does not lower it, whether or not you pay for a plan. If a subscription includes a lock, compare credit locks with free security freezes before deciding what coverage you need.
Explore related guides on credit scores.
To understand the entries and statuses behind your score, use our credit report reading checklist before deciding what to do next.
Sources
Last reviewed: September 28, 2026. This guide is for general education, not individualized financial or legal advice. Check provider terms when making a purchase.